



TL;DR
Crypto markets remain under pressure as Bitcoin returns to price levels last seen in April and Ethereum continues to lag. The drop has been driven mainly by spot selling from large holders and sustained outflows from exchange-traded products. Demand is fragile even though leverage has largely been flushed out. Importantly, the decline has been driven primarily by spot selling rather than forced liquidation, which signals weak demand rather than systemic stress. This increases the possibility of seller exhaustion.
Macro remains the main driver. The United States data blackout created uncertainty just as the Federal Reserve approaches a finely balanced decision in December. Markets now lean toward expecting no cut, but tariff effects, high-frequency inflation estimates, and private labour data suggest that this pricing may be too hawkish.
Despite the volatility, long-term structural progress continues to strengthen. Payment infrastructure built on Bitcoin and Solana is expanding, sovereign wealth funds have increased their exposure, and regulatory work is advancing. The long-term trajectory remains constructive even though near-term caution continues to be warranted.
In this week’s note
Macro View
Market Movers & Events – Last Week
Key Macro Drivers – The Week Ahead
Market Outlook
1. Macro View
Macro is still in control
Macro continues to dominate digital asset performance. The delayed nonfarm payrolls print for September showed stronger than expected hiring, but the data is outdated and followed another revision to previous months. Because official inflation and labour data for October cannot be published retroactively, the Federal Reserve has limited visibility ahead of the December meeting.
The absence of updated weak data has supported the United States dollar. A stronger dollar increases pressure on risk assets, including crypto. The end of quantitative tightening on the first of December should stabilize the Federal Reserve balance sheet near six and a half trillion United States dollars, which may help cap dollar strength later in the quarter.
Rate cut or pause
Futures markets have moved from expecting a cut in December to expecting a pause. This shift has been driven by fears of persistent inflation. The minutes of the October Federal Open Market Committee meeting revealed a divided Committee. Many members supported holding policy steady. Others preferred another cut. A smaller group wanted more caution because inflation remains above target.
In my view, several factors suggest the market may be mispricing the decision.
Research from the Federal Reserve Bank of San Francisco shows that tariff increases behave like negative demand shocks and tend to reduce inflation in the short term. High-frequency PCE estimates from Truflation point to mild cooling rather than renewed acceleration. Private labour indicators, including ADP, job cuts, vacancies, and wage data, show weakening momentum even if headline payrolls appear firm.
Taken together, these signals support the case for another insurance cut unless official inflation data surprises significantly to the upside.
2. Market Movers & Events – Last Week (Nov 17 – 23)
Price action
Bitcoin moved below important moving averages and returned to levels last seen in April. The speed of the pullback created psychological stress, but the magnitude remains consistent with previous post-FTX corrections. Ethereum underperformed due to deeper liquidations and heavier outflows from exchange-traded products. Global markets shifted into a risk-off posture. Nvidia earnings triggered profit-taking in semiconductor and artificial intelligence related equities. The dollar strengthened on firm labour data and yen weakness. Gold failed to gain momentum due to dollar pressure. Bond yields moved lower as traders reassessed Federal Reserve policy.
FOMC Minutes of November 19
The minutes reinforced uncertainty. The Committee remains divided. Many members supported holding rates. Others favoured another cut due to softening labour conditions. A smaller group remained concerned about inflation. The tone suggested that policymakers are operating with limited visibility and prioritising risk management. Markets interpreted the minutes as modestly hawkish, which added pressure to crypto.
PMI Release of November 21
The PMI report showed ongoing contraction in manufacturing and slower growth in services. This supported the narrative of cooling demand. The report had a limited immediate effect because inflation data remains the main input for the December decision. Combined with the minutes, the PMI release contributed to a cautious environment across risk assets.
Flows and positioning
Flows continue to reflect ongoing de-risking. Large Bitcoin holders sold nearly six billion dollars worth of BTC over the past month. Holders with ten thousand to one hundred thousand BTC added approximately three billion dollars over the same period. Since the October twenty ninth Federal Reserve meeting, Bitcoin exchange-traded products recorded roughly five billion dollars in outflows and remain on track for their worst month since launch. Ethereum products saw more than two billion dollars in redemptions.
Infrastructure and adoption
Lightspark uses the Lightning Network to enable instant multi currency payments for fintech platforms. Western Union is integrating Solana for stablecoin based remittances. Cash App is adding stablecoin transfers for millions of users. The Abu Dhabi sovereign wealth fund increased its Bitcoin exposure which reinforces long term institutional adoption.
Policy and regulation
United States lawmakers advanced work on a digital asset market structure framework. The White House proposed new rules for reporting foreign digital asset accounts which exclude decentralised finance from some requirements. Kraken confidentially filed to go public after resolving previous regulatory issues.
Key Headlines
Kraken finally going public: Kraken filed confidentially with the United States Securities and Exchange Commission to go public after an eight hundred million dollar funding round. The valuation reached about twenty billion dollars and the decision follows the resolution of a staking related lawsuit.
The end of United States crypto expatriation: The White House proposed legislation requiring United States taxpayers to report foreign based digital asset accounts to reduce offshore activity. A one hundred and sixty eight page policy report outlined a broader cross border reporting framework while excluding decentralised finance from some requirements.
Abu Dhabi deep in Bitcoin: Abu Dhabi’s sovereign wealth fund tripled its exposure to Bitcoin through the IBIT exchange traded fund during the third quarter. The fund described Bitcoin as a digital store of value and reinforced the Middle East’s growing presence in digital assets.
3. Key Macro Drivers – The Week Ahead (Nov 24 – 30)
November 25
United States producer price index
United States retail sales
November 26
United States PCE inflation
November 28
United States crypto term futures expiration
View: PCE inflation is the most important release this week. A softer reading would support the case for a December cut. A stronger reading would reinforce the pause scenario. Retail sales and producer prices will help determine whether consumer demand is beginning to weaken. If both soften, this will support the idea that tariffs and slower labour momentum are already tightening conditions. The expiration of United States crypto term futures on November 28 may generate short-lived volatility. Broader direction will continue to depend on private labour indicators until official data resumes in early December.
4. Market Outlook
Liquidity and Positioning
Crypto market capitalisation continues to fall. Trading volumes remain high and focused on selling. Stablecoin supply remains under pressure with net outflows from USDC.
Bitcoin (BTC)
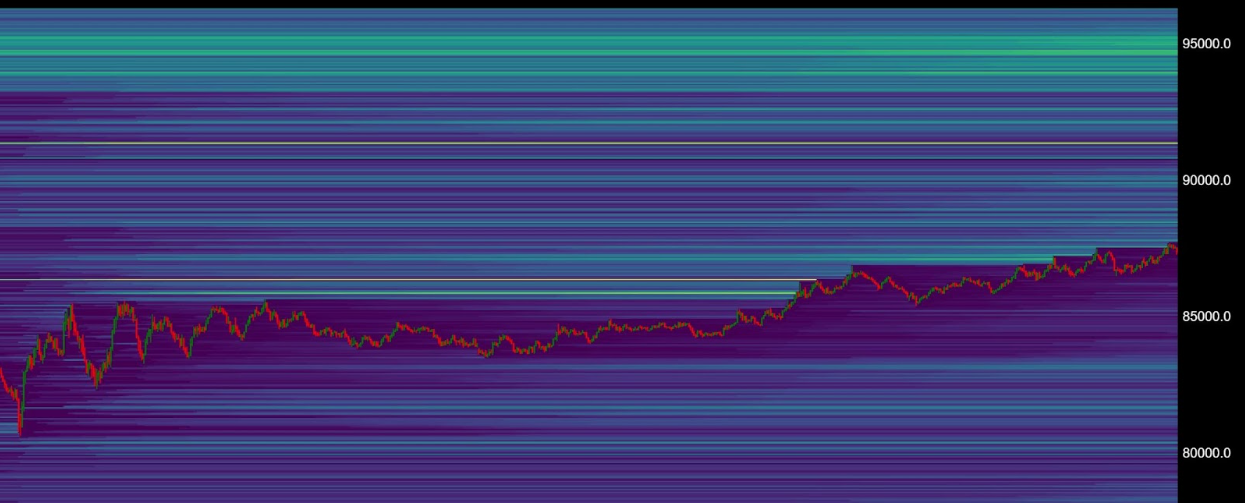
Bitcoin has returned to price levels from earlier this year. Supply is fixed, and network security continues to rise. The current phase reflects a rotation in ownership. Early holders have been selling while smaller institutional and long-term buyers have been accumulating.
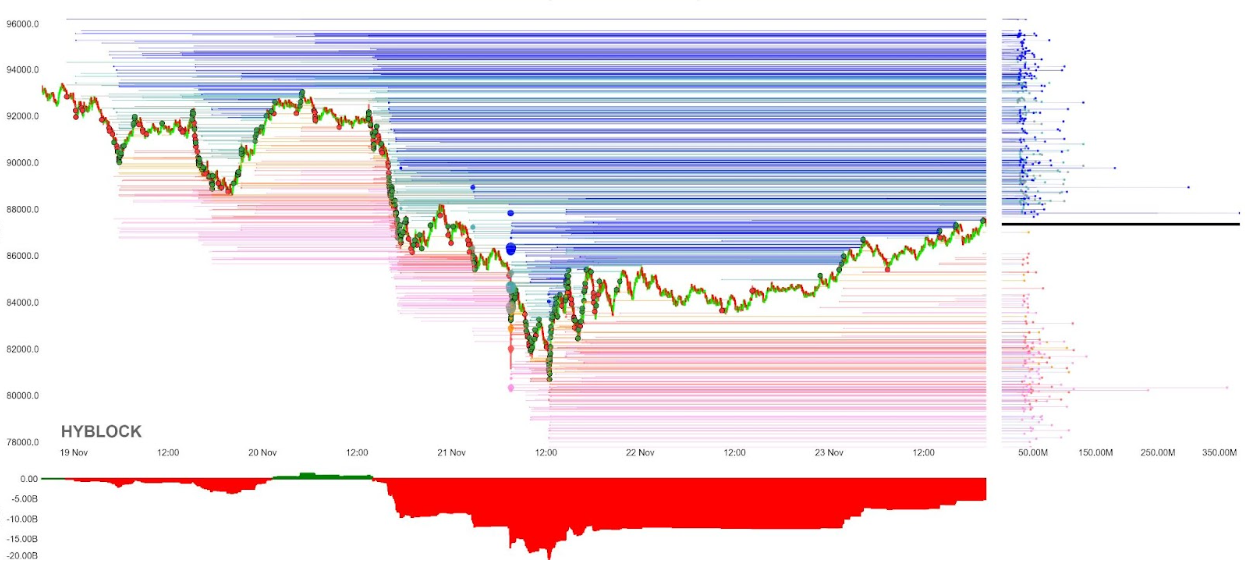
The recovery from Friday's lows below 81000 USD has reset most leveraged shorts. The chart suggests a retest of the 4-hour 50 EMA near 89750 USD. Short-term targets are 89500 USD and 91500 USD. A sustained recovery above this zone is required to rebuild confidence. A retest of the 82000 USD zone remains the most probable scenario.
Ethereum (ETH)
Ethereum continues to lag due to significant outflows and a deeper leverage unwind. The current decline remains within its historical pattern. Long term fundamentals remain supported by continued development in scaling, staking and ecosystem activity. Short term performance will depend heavily on Bitcoin, macro data and exchange traded product flows.
Altcoins
Altcoins remain under pressure due to weak liquidity and limited risk appetite. Solana and XRP are likely to be the best relative opportunities this week. Recently launched Solana and XRP exchange traded products recorded net inflows of 300.46 million dollars and 410 million dollars respectively.
Hyperliquid could be an outside bet after a significant drop over the weekend linked to an upcoming token unlock. The project continues to announce integrations and fee reductions aimed at supporting long term adoption.

Copyright © 2026 Rain Management W.L.L.