


Weekly Crypto Outlook - June 29, 2026
Crypto markets weakened as accelerating ETF outflows, shrinking stablecoin liquidity, and extreme fear continued to pressure risk assets. Bitcoin rebounded from $58,000, but a sustained move above $61,000 is needed before the short-term outlook becomes more constructive.

TL;DR
Crypto markets weakened again last week as macro pressure, ETF outflows, and poor sentiment continued to weigh on risk assets.
Total crypto market cap moved lower to around $2.10T to $2.14T, down roughly 2.3% from last week. Bitcoin dominance slipped slightly to 58.2%, while Ethereum dominance fell to 9.3%.
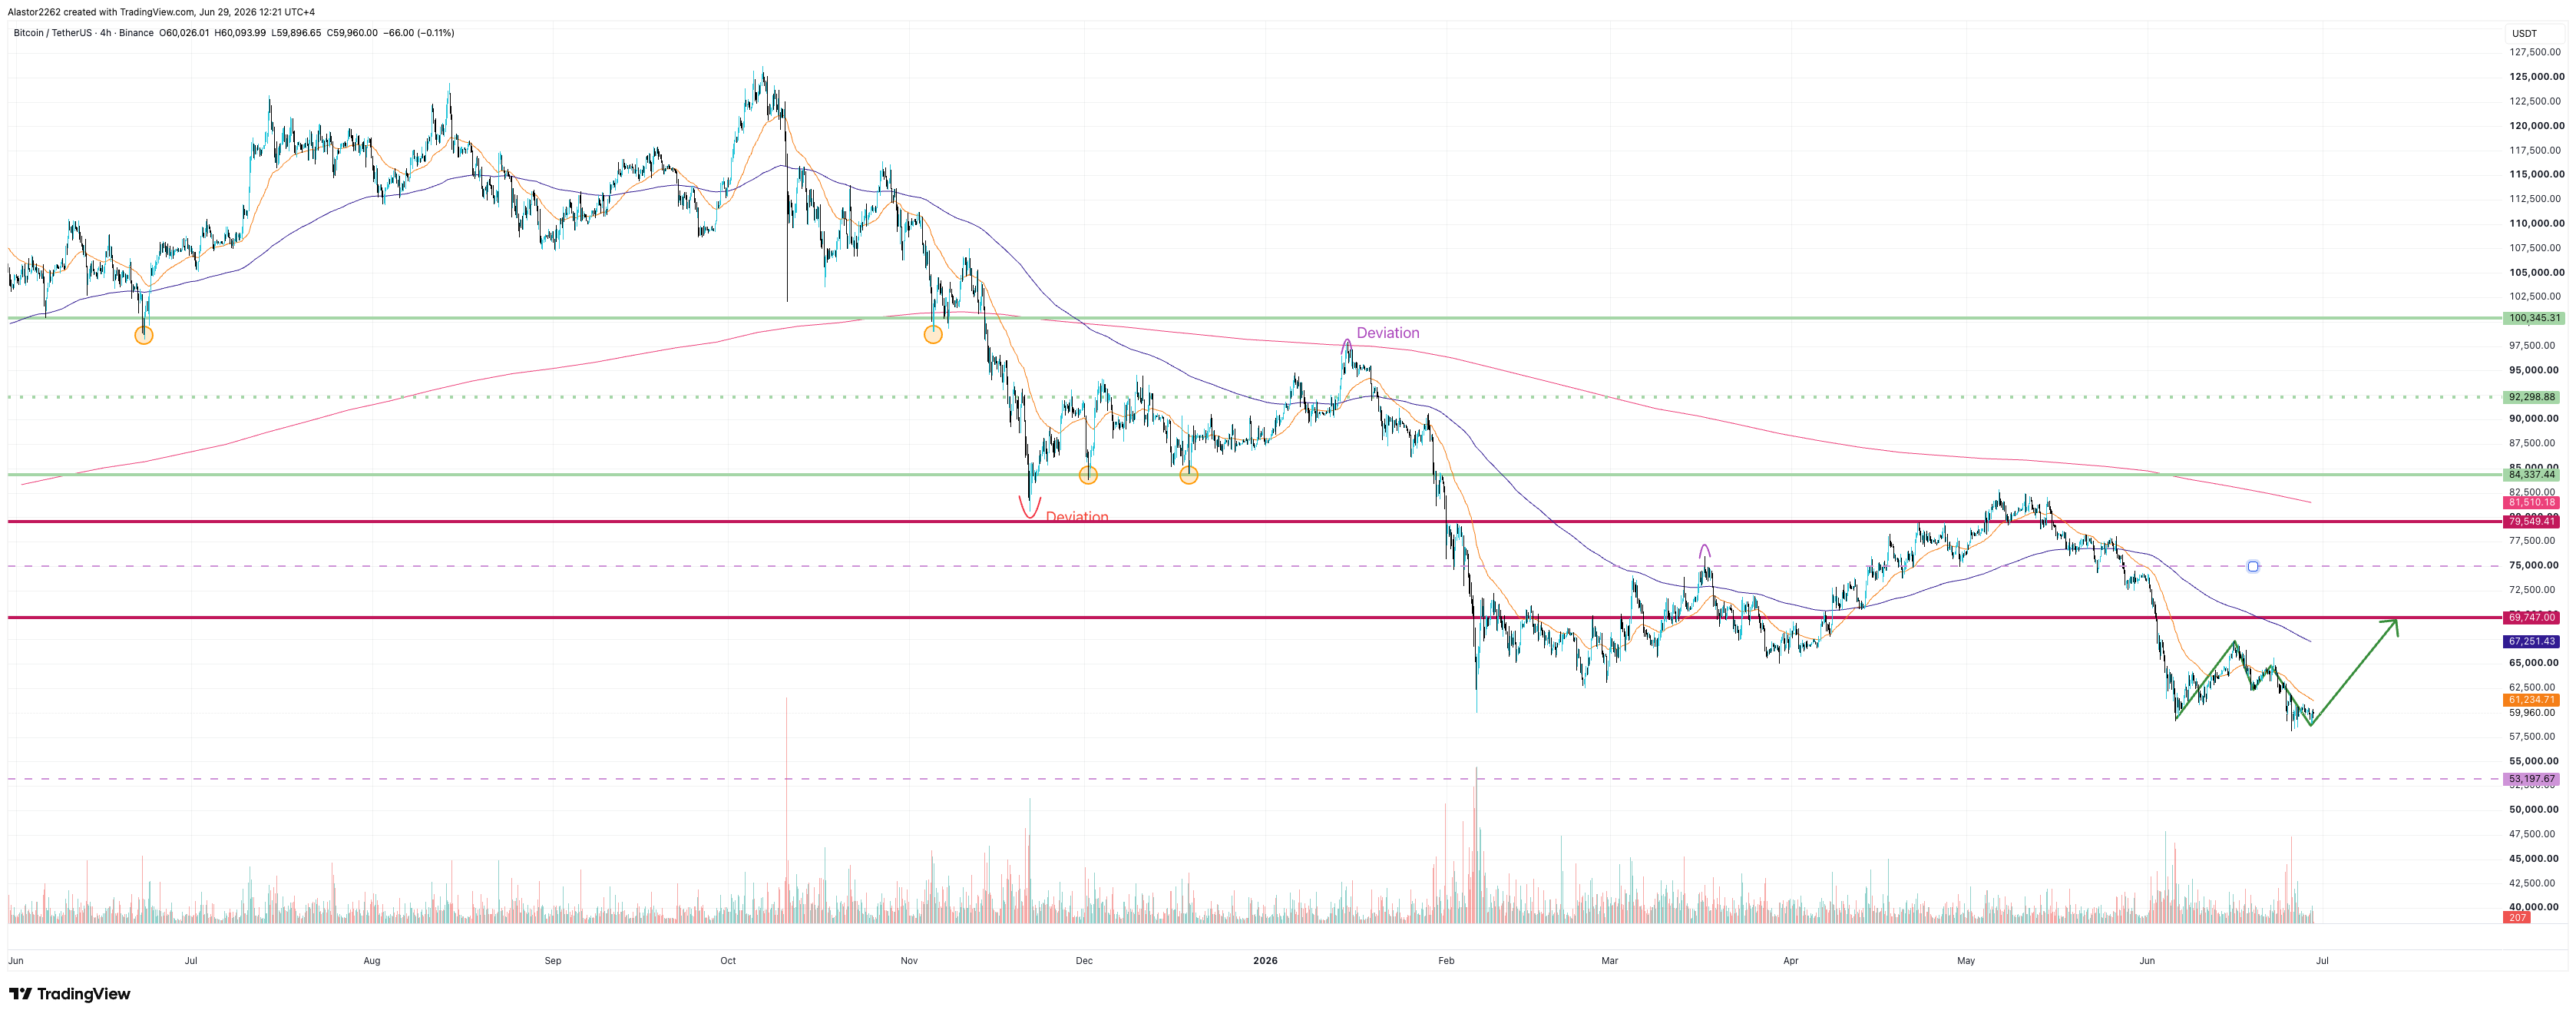
Bitcoin briefly traded down to around $58,000 before recovering convincingly. The bounce shows that buyers are still active on dips, but $61,000 remains the key short term pivot. A clean reclaim and hold above $61,000 would improve the setup and open the door to a move toward the $63,000 to $67,000 liquidity zone.
ETF and ETP flows remain the biggest problem. Weekly spot ETF net outflows accelerated to around $1.58B, while global digital asset ETP issuers recorded around $1.4B in net outflows so far this week. Without institutional inflows, rallies remain difficult to sustain.
Stablecoin liquidity also deteriorated. Total stablecoin sector cap fell to around $313.2B, while USDT market cap declined to around $184.9B. The 7 day net capital off ramp was around $2.1B, confirming that liquidity is still leaving the market.
Sentiment is back in extreme fear. Bitcoin Fear and Greed dropped to 16, while Ethereum fell to 12. This is a sign of stress, but it can also support sharp tactical bounces if price reclaims key levels.
The geopolitical backdrop is less negative than last week. The United States and Iran have agreed to halt attacks and renew talks, reducing the immediate oil shock risk. WTI has retraced back around $70, close to pre-war levels. However, the agreement remains fragile after the weekend's tit for tat strikes.
The preferred approach is to stay patient. Bitcoin has shown buyer interest near $58,000, but the market needs to reclaim $61,000 before the risk reward improves. Until then, rallies should be treated carefully.
In This Week's Note
Macro View
Market Movers and Events, Last Week
Key Headlines
Key Macro Drivers, The Week Ahead
Notable Token Unlocks
Market Outlook
Macro View
Macro remains the main driver for crypto.
The market is now dealing with two pressure points. The first is the AI selloff. The Morningstar AI Index fell 6.1% over two days, dragging broader tech sentiment lower and pushing investors toward safe havens, especially the dollar. The broader move had a clear risk off signature, with the Australian dollar, New Zealand dollar, and Canadian dollar all weakening while the yen remained firm.
The second pressure point is rates. Core PCE came in line with expectations at 3.4% in May, but consumer spending was stronger than expected. That keeps the Fed in a hawkish position and supports the higher for longer rate backdrop that continues to weigh on Bitcoin.
Kevin Warsh's first meeting as Fed Chair already pushed markets toward tighter rate expectations. The issue for crypto is not only the level of rates, but also the lack of visibility. A Fed that gives less forward guidance and reacts more directly to incoming data means more volatility around every major inflation and employment release.
The geopolitical backdrop has improved after a volatile weekend. The United States and Iran have agreed to halt attacks and renew talks, with U.S. officials saying both sides will stand down for now to preserve the fragile Memorandum of Understanding signed earlier this month.
This is positive for markets because it lowers the immediate risk of a renewed oil shock. WTI has already retraced sharply and is now back around $70, close to pre-war levels. That reduces the inflation pressure that was weighing on markets earlier in June.
However, the weekend's tit for tat strikes show that the agreement remains fragile. For now, geopolitics is less of a direct macro headwind than it was last week, but it remains an important headline risk. The market will need to see the halt in attacks hold and talks resume before fully removing the risk premium.
For Bitcoin, the setup is mixed. The macro backdrop remains difficult, ETF outflows are accelerating, and stablecoin liquidity is weak. However, the recovery from $58,000 was constructive and suggests that buyer interest still exists at lower levels.
This is not a strong risk on setup yet, but it is also not a clean capitulation setup. The better framing is tactical caution.
Market Movers and Events, Last Week
Market data and flows
Total crypto market cap fell to around $2.10T to $2.14T, down roughly 2.3% from last week.
Bitcoin dominance moved slightly lower to 58.2%, while Ethereum dominance declined to 9.3%. This shows that the market is not rotating cleanly into ETH or altcoins. The whole market remains under pressure.
Weekly spot ETF net flows deteriorated sharply, moving from around $142M of outflows last week to around $1.58B of outflows this week. Global digital asset ETP issuers also recorded around $1.4B in net outflows so far this week.
Ethereum gas fees fell to 0.06 Gwei, down from 0.12 Gwei last week. This confirms that network activity remains very weak.
Stablecoins and liquidity
Stablecoin liquidity deteriorated again.
Total stablecoin sector cap fell to around $313.2B. USDT market cap declined to around $184.9B, down 0.8%, while USDC increased to around $75.6B, up 1.1%.
The increase in USDC looks more defensive than expansionary. The broader message is still capital flight, with a 7 day net capital off ramp of around $2.1B.
This remains one of the clearest reasons why the market is struggling to sustain rallies. Without fresh stablecoin inflows, liquidity remains too weak for a broad recovery.
Sentiment
Sentiment deteriorated sharply.
Bitcoin Fear and Greed dropped from 35 to 16, moving back into extreme fear. Ethereum Fear and Greed dropped from 30 to 12.
This is the deepest panic reading of the cycle so far. Extreme fear can create tactical bounce conditions, but sentiment alone is not enough. Price still needs to reclaim key levels, and flows need to stabilize.
Technical picture
Bitcoin RSI declined to around 35 on the daily timeframe, showing oversold consolidation.
The key level remains $61,000. Bitcoin briefly traded near $58,000 before recovering, which is encouraging. However, $61,000 is still meaningful resistance. A clean reclaim and hold above that level would shift the short term setup more constructive.
Until then, the market remains fragile and exposed to another move lower if macro pressure or outflows continue.
Key Headlines
Binance withdraws its Greek licence bid but says it is staying in Europe
Binance withdrew its MiCA application with Greece's Hellenic Capital Market Commission on June 24, 2026. The move came days before the July 1 deadline requiring crypto firms to hold a licence in at least one EU member state.
Binance said it will seek authorisation in another EU country and that affected EU users will be contacted directly. The company also said customer funds remain accessible and that it is not leaving Europe.
This is not a direct Bitcoin catalyst, but it keeps regulatory uncertainty in focus for large global exchanges.
ICE and OKX form a tokenisation joint venture
Intercontinental Exchange, owner of the NYSE, and OKX announced a 50-50 joint venture on June 22, 2026 to build infrastructure for tokenised and digitally native products.
Subject to regulatory approval, the venture is expected to operate as a U.S. registered broker dealer and FCM. The goal is to give OKX's customer base access to ICE futures and NYSE tokenised equities.
This is structurally positive for tokenisation and regulated crypto market infrastructure. It does not change the near term liquidity picture, but it reinforces the longer term institutional direction of the industry.
Kraken deepens its institutional credit and DeFi push
Kraken and Maple closed an onchain warehouse facility for digital asset backed loans. The structure is USDC denominated and supports Kraken's OTC lending desk, with Maple providing senior financing through a bankruptcy remote SPV.
Separately, Kraken is reportedly in talks to take a 15% stake in Aave Group at a valuation of around $385M, although the discussions remain unconfirmed and Aave's founder publicly played down the idea of a structured acquisition.
The broader takeaway is that institutional credit, DeFi lending, and onchain capital markets continue to converge. This is constructive for crypto market structure, even if it does not solve the current macro and liquidity pressure.
Strategy contagion fears weigh on sentiment
Strategy related instruments added pressure to market sentiment. STRC, the yielding component of Strategy, dropped to around 75 from par at 100, while SATA fell to around 88.
Some of this may reflect cannibalisation between instruments, but the market is treating it as a sign of broader fragility. Strategy's Bitcoin holding, at around 4% of total supply, is not a systemic risk on its own, but it is currently weighing on sentiment.
Whale selling has cooled
One encouraging signal is that whale selling has slowed dramatically.
Whale selling was one of the key triggers of the October selloff, so the slowdown matters. Based on the four year Bitcoin cycle, selling was expected to taper around 6 to 9 months after it began, and that appears to be happening roughly on schedule.
The caveat is that whales historically do not return as major buyers until the next halving cycle, which is not due until 2028. This means whale selling pressure has improved, but this cohort is unlikely to become a major source of demand in the near term.
Key Macro Drivers, The Week Ahead
Only high impact events are included.
Wednesday, July 1: ADP Employment Change
ADP will be the first major labour market signal of the week.
A strong print would support the Fed's higher for longer stance and could pressure Bitcoin. A weak print would be more supportive for risk assets because the market needs evidence of labour market deterioration before it can price a more dovish Fed path.
Wednesday, July 1: ISM Manufacturing PMI
ISM Manufacturing PMI will help show whether restrictive rates are starting to affect activity.
A stronger number would support the idea that the economy remains resilient despite tighter policy. That would be negative for Bitcoin in the short term. A weaker number would support the slowdown narrative and could help stabilize liquidity expectations.
Thursday, July 2: Average Hourly Earnings MoM and YoY
Wage inflation is important because it feeds directly into the Fed's inflation framework.
If wages remain firm, it will be difficult for the Fed to soften its stance. That would keep pressure on Bitcoin. A softer wage number would be more constructive because it would reduce inflation pressure from the labour market.
Thursday, July 2: Nonfarm Payrolls
Nonfarm Payrolls is the most important release of the week.
The market is looking for signs that employment is finally weakening. A strong payrolls number would reinforce the higher for longer narrative and likely pressure Bitcoin. A weak payrolls number would be supportive, especially if combined with softer wage growth.
Notable Token Unlocks, June 29 to July 5
Ethena, ENA
Unlock date: June 29 to July 1
Approximate value: $16.3M
Supply impact. 2.3% of circulating supply
This is the largest unlock of the week by dollar value and should remain on watch.
Sui, SUI
Unlock date: July 1
Approximate value: $9.4M
Tokens unlocked: 13.72M SUI
Supply impact: 0.34% of circulating supply
The dollar value is meaningful, but the supply impact is relatively manageable.
EigenCloud, EIGEN
Unlock date: July 1
Approximate value: $8.7M
Tokens unlocked: 36.82M EIGEN
Supply impact: 6.15% of circulating supply
This is a meaningful supply event and could create pressure if market liquidity remains weak.
Collector Crypt, CARDS
Unlock date: June 29
Approximate value: $7.3M
Tokens unlocked: 28.84M CARDS
Supply impact: 6.11% of circulating supply
The supply impact is high and should be monitored closely.
Falcon Finance, FF
Unlock date: June 29
Approximate value: $6.8M
Tokens unlocked: 102.0M FF
The dollar value is smaller than ENA, but still relevant in a low liquidity market.
Market Outlook
Bitcoin
Support zone: $58,000
Key short term pivot: $61,000
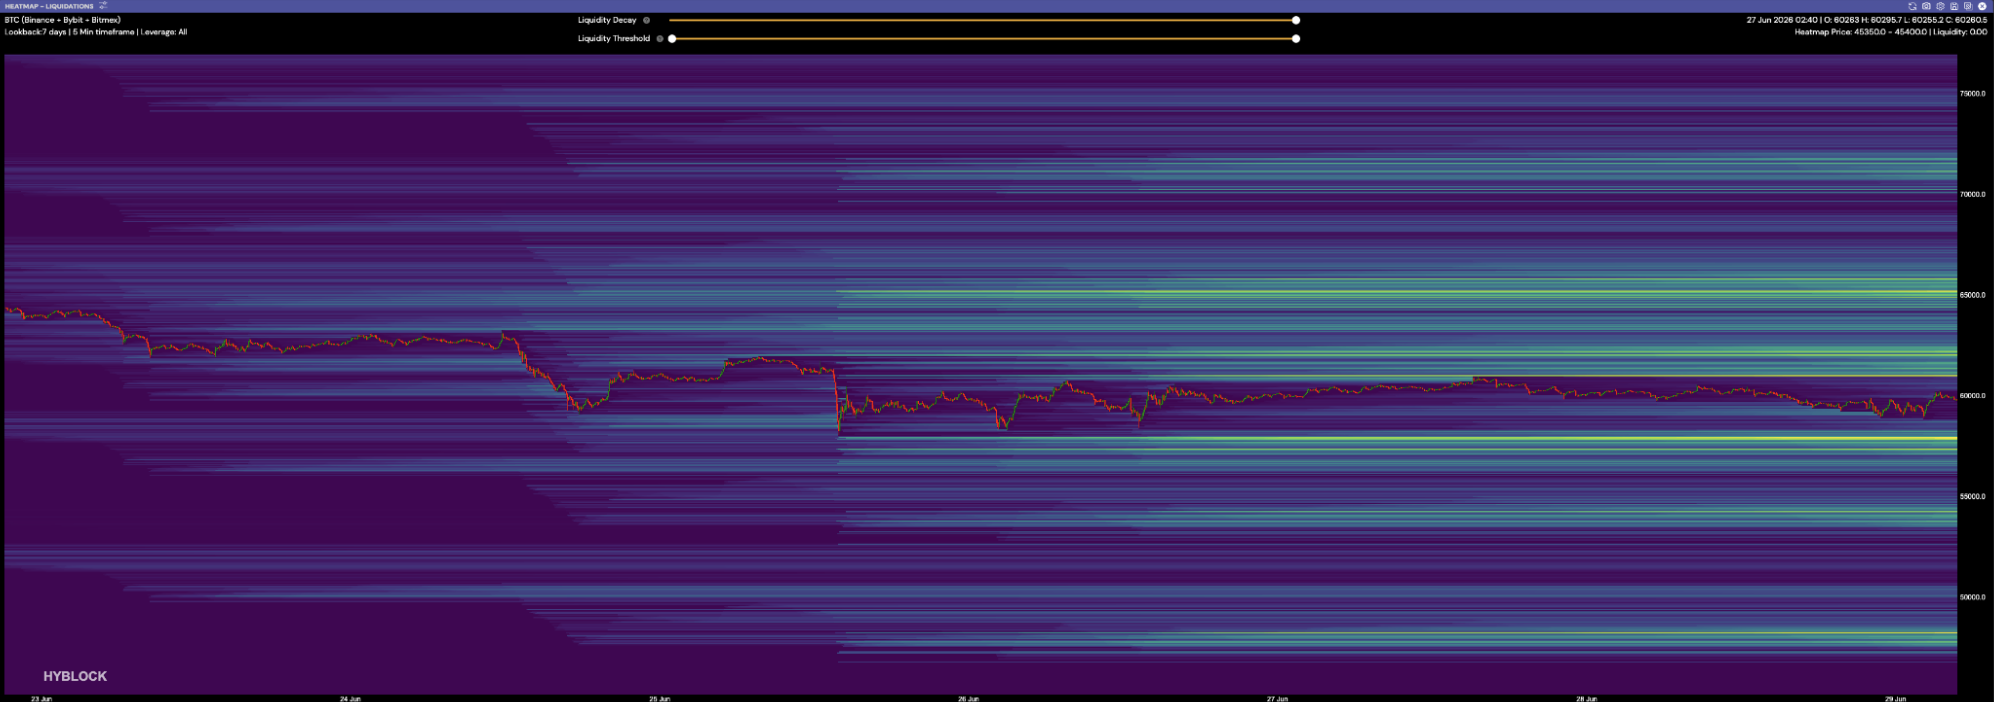
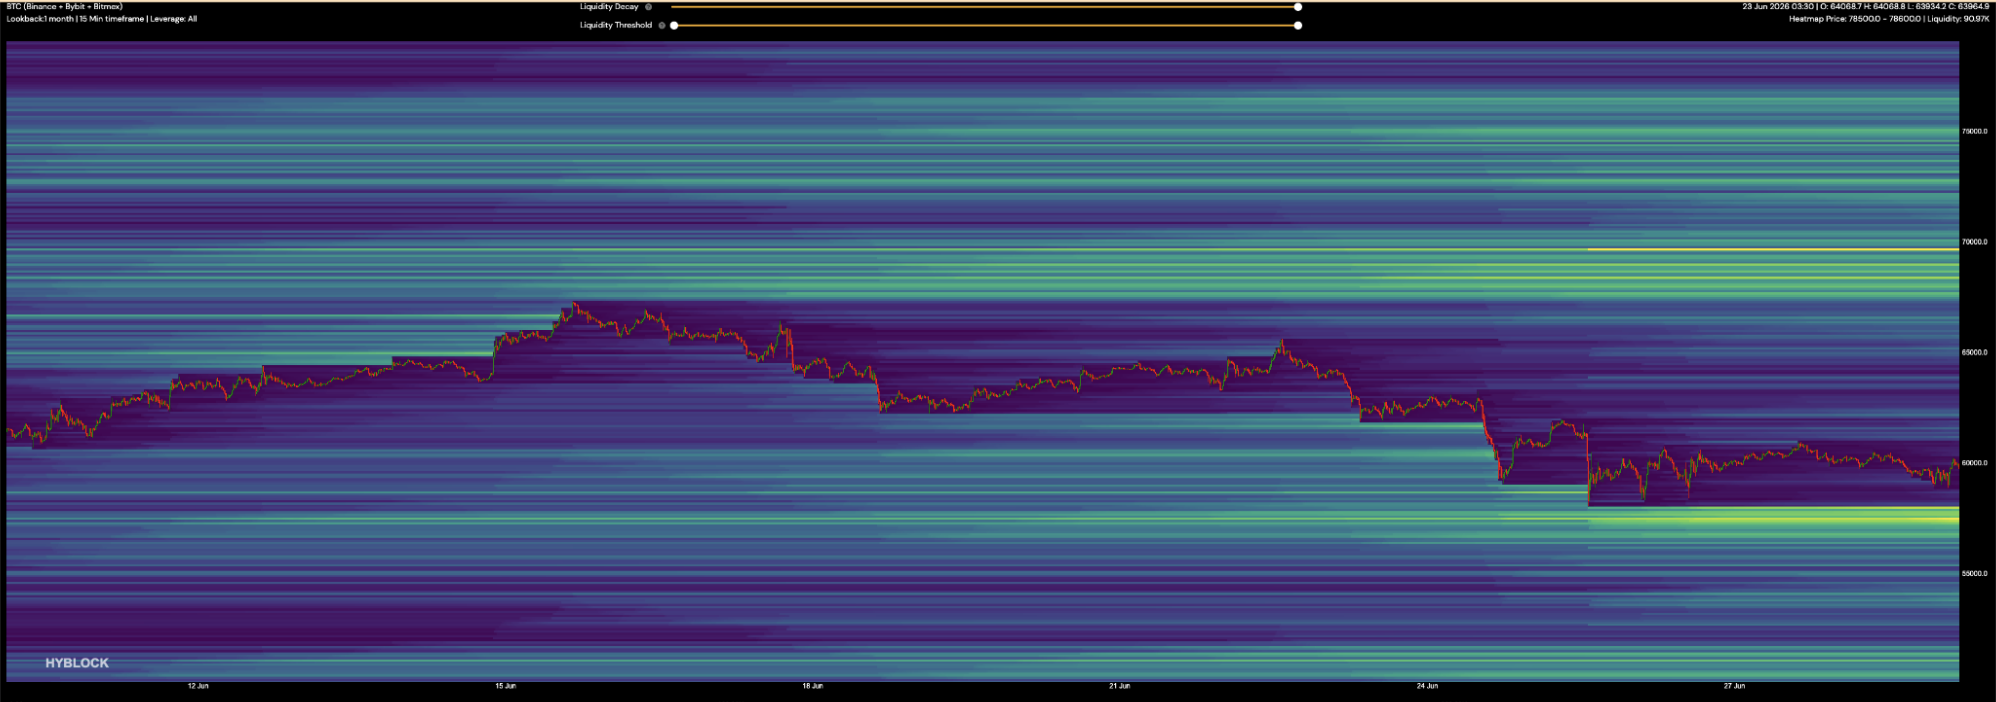
Upside liquidity zone: $63,000 to $67,000
Major upside liquidity target: $67,000
Risk zone: failure to reclaim $61,000
Bitcoin remains fragile, but the bounce from $58,000 was encouraging.
The recovery shows that there is real buyer interest on dips. However, $61,000 remains the key level. Bitcoin needs to reclaim and hold above $61,000 this week to confirm short term structural strength.
If $61,000 is reclaimed cleanly, the next likely move is a liquidity run toward $63,000 to $67,000. Short liquidations are clustered in that area, so the move could be fast if the pivot clears.
The main risk is that macro pressure continues to dominate. AI weakness, ETF outflows, stablecoin off ramps, and hawkish Fed expectations are still working against Bitcoin. The U.S. and Iran de-escalation reduces the immediate oil shock risk, but the agreement remains fragile after the weekend's strikes.
The preferred approach is to stay fluid and patient. Avoid chasing early longs while the 8 hour trend remains unclear. The better risk reward comes only after a clean reclaim of $61,000.
Ethereum
Support zone: low of the current range
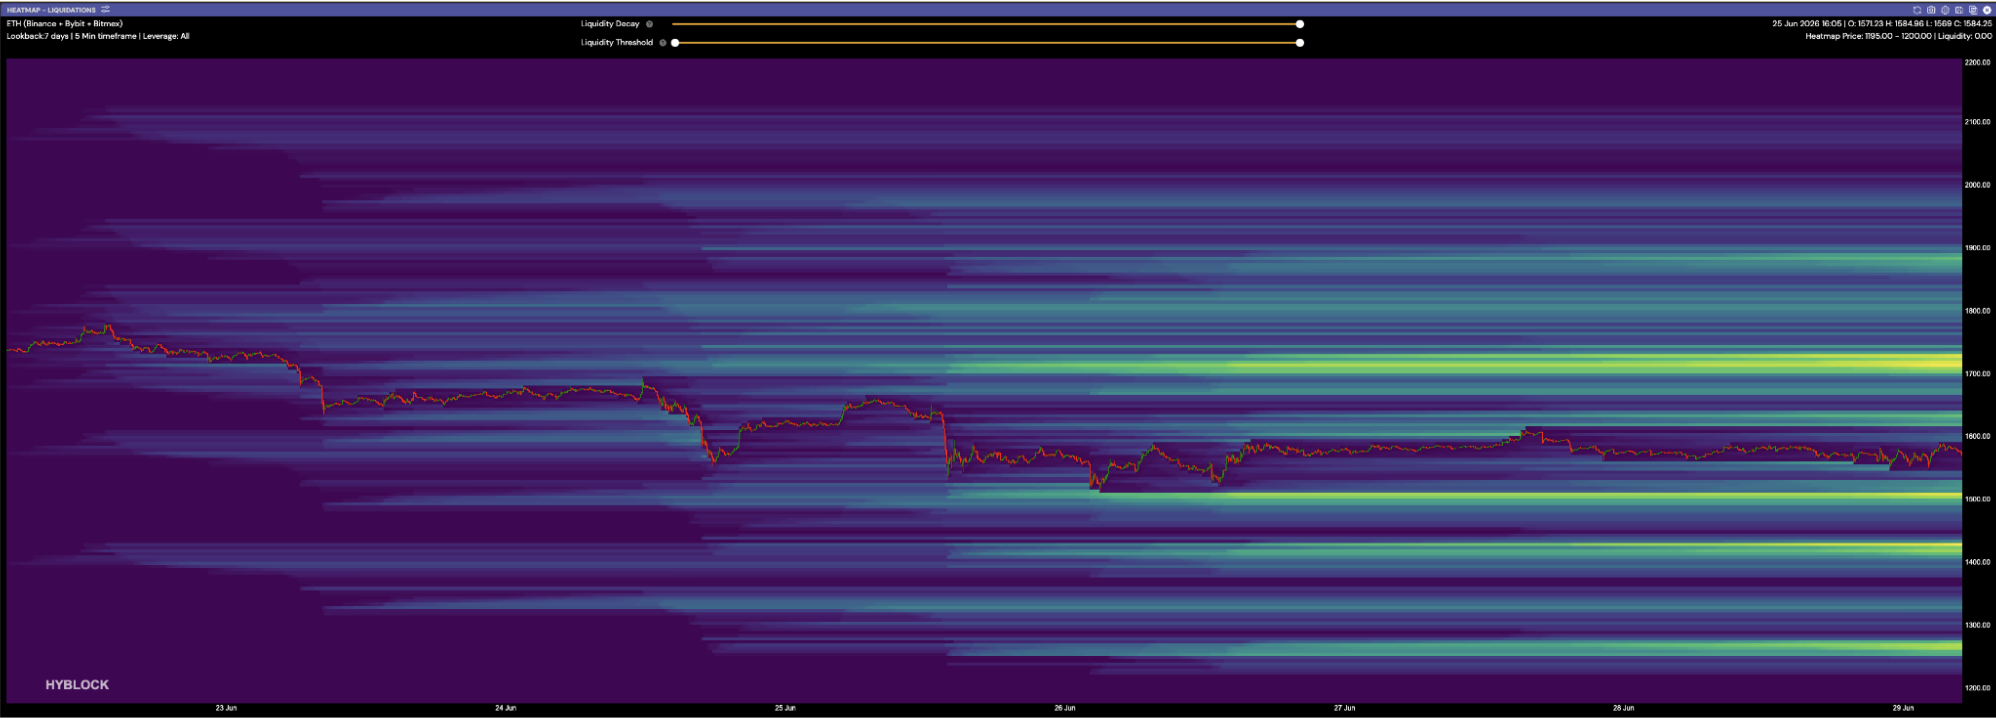
Key short term level: $1,850
Major upside liquidity target: $2,150
Ethereum remains weaker than Bitcoin.
ETH dominance declined to 9.3%, and Ethereum Fear and Greed dropped to 12. Network activity remains extremely weak, with gas fees near 0.06 Gwei, confirming that onchain demand is still soft.
The Ethereum Foundation restructuring is also weighing on sentiment. The Foundation cut 54 staff, around 20% of its workforce, as part of a reorganisation into five domain clusters: protocol, access, user, community, and institutional.
The restructuring may be healthy over the long term if it improves execution and reduces reliance on one central body. However, in the short term, it raises governance questions around who sets priorities, how independent core research remains, and whether institutional ETH treasury backers begin to shape protocol work more visibly.
The CLARITY Act also remains an important overhang. Ethereum is arguably one of the assets best positioned to benefit from passage because of its smart contract infrastructure, but the timeline remains uncertain. A signature in the coming weeks looks unrealistic. The more credible window is around the August recess, assuming the Senate floor vote and reconciliation process do not slip further.
ETH needs to reclaim and hold $1,850 before the short term structure improves. Until then, Ethereum should be viewed as a tactical recovery candidate inside a weaker broader trend.
Altcoins
Altcoin exposure should remain selective and limited.
The market does not yet have the liquidity conditions needed for a broad altcoin rotation. Stablecoin supply is shrinking, ETF and ETP outflows are accelerating, and Ethereum is not providing leadership.
There are still pockets of structural strength, especially in tokenisation, regulated market infrastructure, onchain credit, and institutional DeFi. The ICE and OKX joint venture, Kraken and Maple facility, and possible Kraken interest in Aave all point in that direction.
However, these are longer term market structure themes. They do not offset the near term pressure from weak liquidity and macro uncertainty.
The better approach is to avoid broad altcoin beta and focus only on names with clear catalysts, strong product momentum, or specific market structure relevance.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.