


Weekly Crypto Outlook – January 12, 2026
Crypto markets enter mid-January with improving price action but increasingly fragile internals, as leverage rebuilds faster than liquidity. ETF outflows and contracting stablecoin supply signal that recent gains are driven more by positioning than participation. The outlook favors a liquidity-driven push higher followed by an elevated risk of sharp reversals.

TL;DR
Crypto markets enter mid-January with improving price action but increasingly fragile internals. Early-year optimism has faded as ETF inflows reversed, stablecoin supply continues to contract, and futures positioning remains elevated relative to participation. Geopolitical risk eased briefly last week following a swift and contained US military operation in Venezuela, helping stabilize risk sentiment during a technically fragile rebound. The base case favors a liquidity-driven move toward USD 97,600, followed by a corrective reversal into the mid USD 80,000s, reflecting leverage rebuilding faster than liquidity. Near term, US macro data may trigger volatility, but flows, positioning, and derivatives dynamics remain the dominant drivers. Altcoins: selective exposure is advised, with the Green / Orange / Red classifications in the body of this report providing a useful framework for relative positioning.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Macro Drivers, The Week Ahead
Market Outlook
Macro View
From macro dominance to positioning dominance
Macro drivers remain secondary in the near term. With no immediate monetary inflection points, crypto markets are increasingly governed by flows, derivatives positioning, volatility regimes, and internal structure rather than macro repricing.
Geopolitical risk briefly eased late last week, contributing to improved global risk sentiment. Reports of a swift and contained US military operation in Venezuela reduced near-term uncertainty around regional instability and energy supply. While not a structural driver for digital assets, the rapid de-escalation removed a tail-risk overhang at a moment when positioning was already fragile, likely supporting the rebound.
What makes the current environment unstable is the divergence between improving technical and trend signals and still-weak liquidity creation. Futures leverage has rebuilt, sentiment has rebounded sharply, and trend indicators have turned constructive, yet stablecoin supply continues to contract. Risk is re-entering the system faster than liquidity, a setup that often supports near-term upside while increasing the probability of sharp reversals once liquidity targets are met.
Market Movers and Events, Last Week
Market data and flows
Crypto market capitalization: USD 3.09 trillion, down 0.6% week on week
Average weekly trading volume: USD 104 billion, 22% above average
Bitcoin weekly volume: USD 39.3 billion, 26% above average
Ethereum weekly volume: USD 20.1 billion, 19% above average
Ethereum network fees: ~0.04 Gwei, confirming persistently low on-chain activity
Futures and positioning
Futures traders have begun unwinding risk-on exposure.
Bitcoin: funding rose to 8.8% while open interest declined by ~USD 0.5 billion to USD 29.1 billion
Ethereum: funding increased to 10.4% as open interest fell sharply by ~USD 2.4 billion to USD 17.2 billion
This combination suggests long exposure remains crowded despite declining participation, increasing fragility.
ETFs
Bitcoin ETFs: USD 681 million in outflows over the past 7 days
Ethereum ETFs: USD 68 million in outflows over the past 7 days
After just two days of strong inflows at the start of the year, ETF flows have reversed, reinforcing the view that allocator demand remains tactical rather than persistent.
Stablecoins
USDT market cap: USD 186.9 billion, down 0.11% week on week
USDC market cap: USD 74.6 billion, down 0.9% week on week
Net stablecoin flows: approximately USD 0.9 billion in off-ramps last week
The continued absence of stablecoin inflows confirms that current price action is not supported by fresh liquidity.
Dominance
Bitcoin dominance: 58.5%
Ethereum dominance: 12.1%
Relative performance has begun to tilt toward higher beta assets, though leadership remains selective.
Key headlines
SBF not pardoned: President Trump ruled out clemency for former FTX CEO Sam Bankman-Fried, ending months of speculation.
Senator Lummis criticizes DOJ Bitcoin sales: Concerns raised over potential BTC sales conflicting with the Strategic Bitcoin Reserve policy.
Florida renews Bitcoin reserve proposal: New legislation introduced to hold BTC as a state-level reserve asset.
US bill targets prediction markets: Proposed legislation would restrict government officials from trading on platforms like Polymarket.
Key Macro Drivers, The Week Ahead
While macro remains secondary, thin liquidity conditions mean data surprises can amplify price moves.
January 13: US CPI (Dec)
Consensus: 2.7% y/y
Sensitivity: A softer print could support near-term risk appetite, while a higher reading would reinforce the lack of urgency to add exposure.
January 14: US PPI (Nov)
Sensitivity: Secondary impact unless materially surprising; December PPI (Jan 30) is more forward-looking.
January 15: US tax payments due
January 15: US Senate Banking and Agriculture Committees hold synchronized crypto market structure markups
January 19: US markets closed
Market Outlook
Sentiment
Bitcoin Greed & Fear Index: 51%
Ethereum Greed & Fear Index: 62%
Sentiment has normalized from extreme pessimism but remains unstable.
Bitcoin
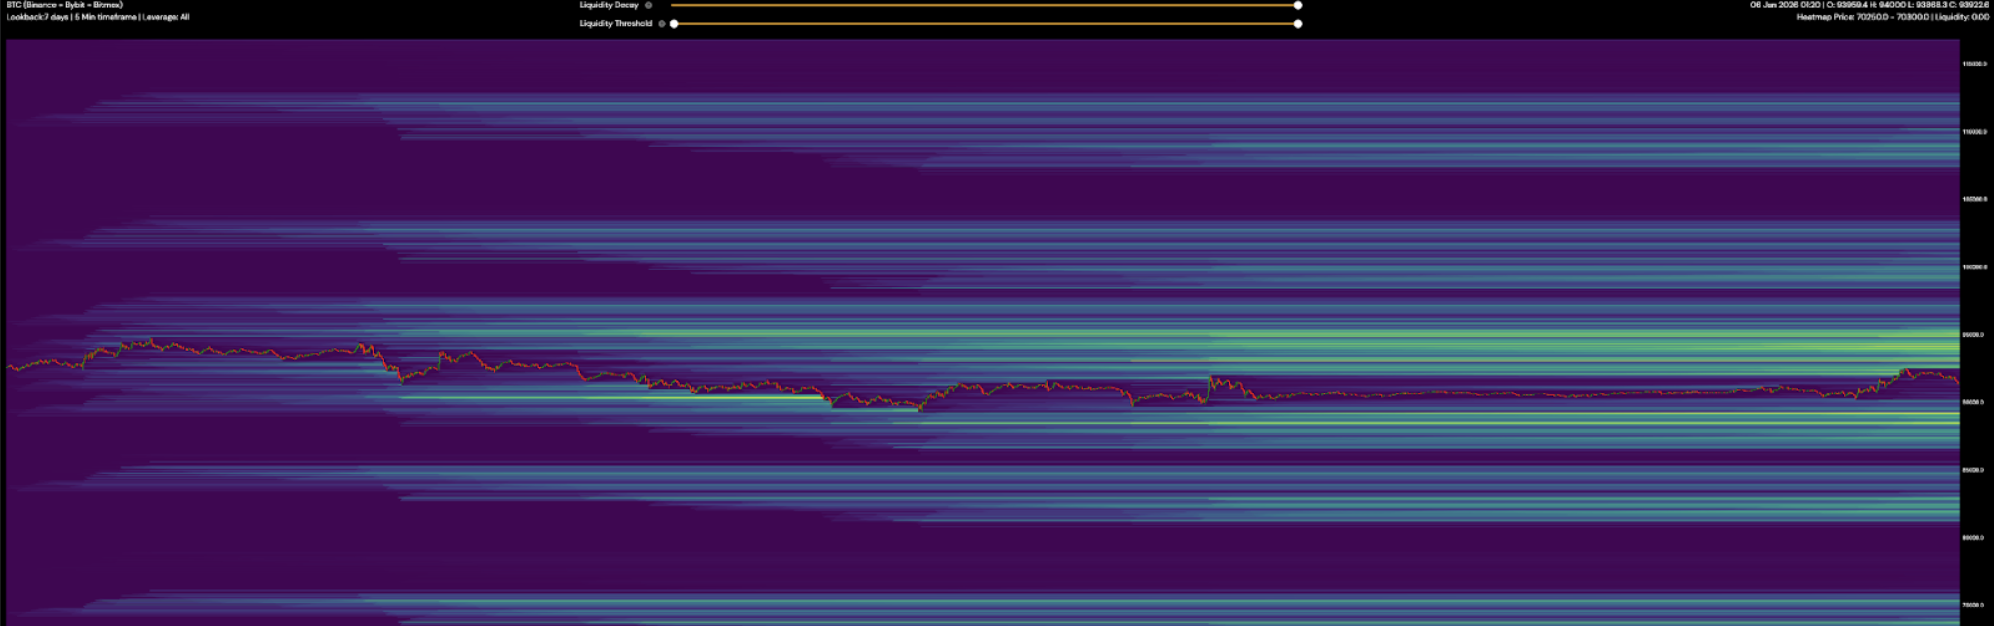
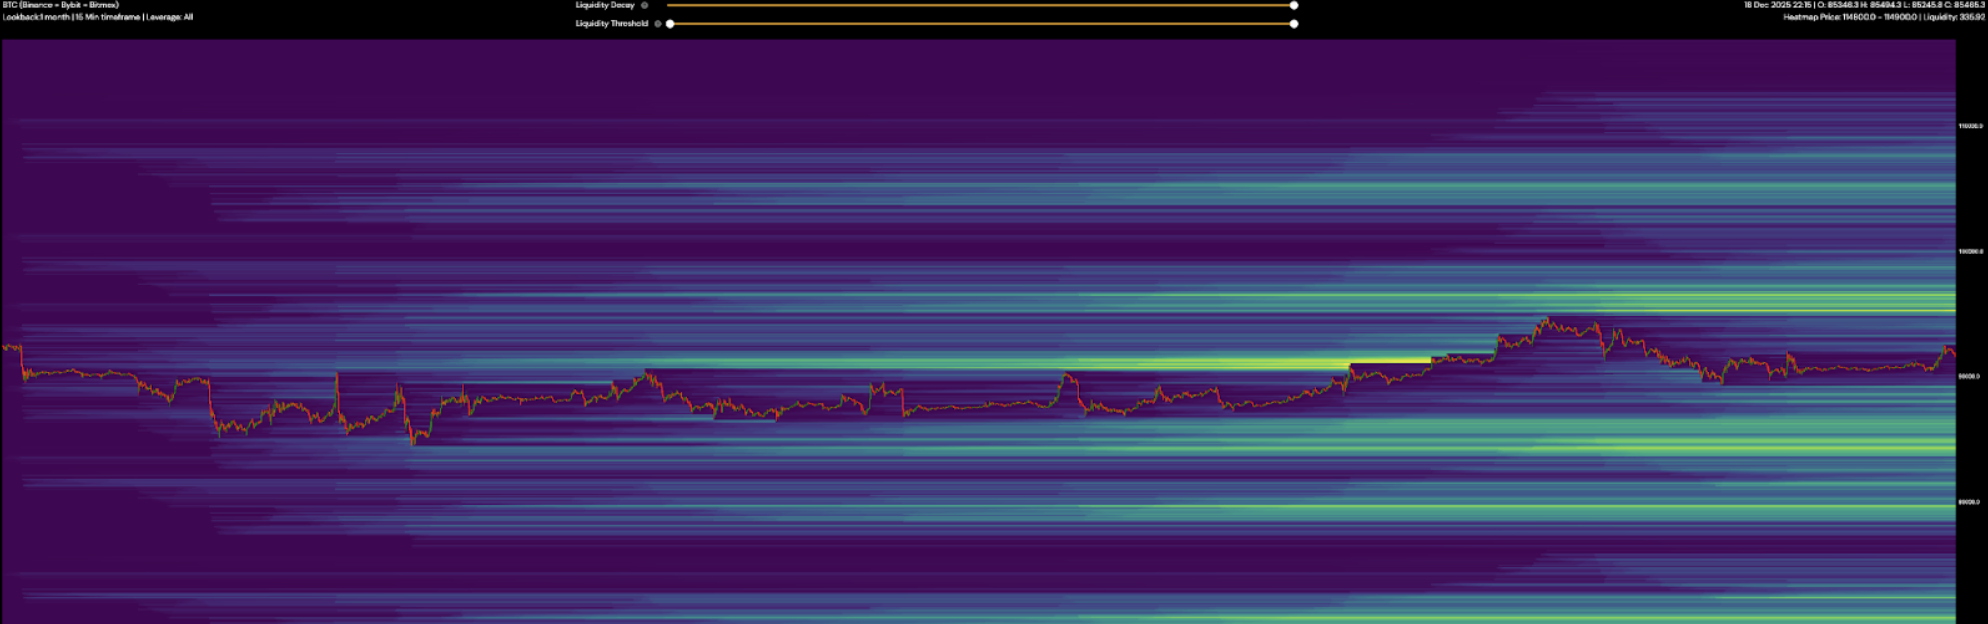
Bitcoin has entered a bullish short-term trend, supported by improving momentum indicators and rising futures positioning. Price is holding above the key short-term pivot at USD 88,636.
Bitcoin remains in a bullish short-term trend but lacks upside momentum. Price action is increasingly driven by positioning rather than participation.
Upside liquidity: USD 95,200 to USD 96,600, with the weekly 50 EMA near USD 97,600
Downside liquidity: USD 88,500 and USD 84,300
Base case:
A liquidity run toward USD 97,600, followed by a reversal to clear downside liquidity into the mid USD 80,000s.
Continuation toward USD 100,000 remains a lower-probability scenario and would require a material improvement in ETF flows, stablecoin issuance, and volume participation.
Ethereum
Ethereum continues to lag structurally. Funding remains elevated even as open interest contracts, leaving ETH vulnerable in a broader BTC pullback.
Upside liquidity: USD 3,200 and USD 3,500
Downside liquidity: USD 3,000 and USD 2,850
Confirmation: Acceptance above USD 3,200
Until confirmation is achieved, ETH strength should be treated as constructive but fragile.
Altcoins
As we move into the start of 2026, the altcoin landscape remains highly fragmented. Liquidity is selective, dispersion is widening, and leadership matters far more than broad beta. The framework below reflects an early-cycle view of relative strength, structural quality, and risk.
🟢 Green – Constructive Structure / Relative Leadership
BNB: Institutional access and protocol upgrades underpin resilience.
Solana: Liquidity leadership and developer momentum remain intact.
Tron: Defensive infrastructure profile driven by stablecoin settlement.
Polygon: Improved burns and institutional focus strengthen structure.
Sui: Ecosystem expansion and buybacks support improving fundamentals.
Render: AI compute demand continues to drive relative outperformance.
Monero: Privacy demand and upgrades offset regulatory overhang.
🟠 Orange – Mixed Signals / Tactical Exposure
XRP: Regulatory progress offset by elevated derivatives positioning.
TON: Vesting clarity and Telegram integration stabilize sentiment.
Stacks: Bitcoin-native yield thesis intact but BTC-dependent.
Ethena: Unlocks and buybacks drive volatile, tactical price action.
Raydium: Strong Solana DEX volumes but cyclical exposure.
Hyperliquid: Venture accumulation offset by supply pressure.
Virtuals: AI narrative-driven flows with sentiment sensitivity.
🔴 Red – Structurally Weak / Elevated Risk
Pudgy Penguins: Brand strength but highly speculative structure.
Zcash: Governance instability undermines confidence.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.