


Weekly Crypto Outlook – November 10, 2025
The crypto market remains in consolidation, driven mostly by institutional and macro positioning rather than fresh inflows. Bitcoin is holding the 100K USD support zone but needs to reclaim 110K–116K for a sustained recovery. Ethereum has seen deeper deleveraging, and altcoin performance remains selective ahead of the Aptos unlock.

TL;DR
Crypto markets remain in a consolidation phase, with price action primarily driven by institutional flows and macro positioning rather than fresh capital inflows. Bitcoin held the 100,000 USD support area on its initial test, but a sustained recovery requires reclaiming the 110,000 USD to 116,000 USD region. Until that level is cleared, trading is likely to remain range-bound and flow-driven.
Ethereum has undergone a deeper reset in positioning and leverage than Bitcoin. The 3,500 USD level remains the key support area, while a constructive setup requires a move back above 3,750 USD, followed by confirmation above 4,000 USD. Spot participation remains muted, and leadership is likely to continue rotating around Bitcoin unless inflows return and broader liquidity improves.
Altcoin performance remains selective and event-driven, with positioning staying cautious ahead of the Aptos unlock. Broader altcoin strength will likely require Bitcoin to regain key resistance and for ETF outflows to stabilize.
For now, the bias remains patient and tactical, focused on accumulating near support and avoiding momentum chasing until inflows strengthen and higher-timeframe resistance levels are reclaimed.
In this week’s note
Market Movers & Events – Last Week
Key Macro Drivers – The Week Ahead
Market Outlook – Liquidity, Bitcoin, Ethereum, Altcoins
1. Market Movers & Events – Last Week (Nov 3 – 9)
The United States government is reopening after a 40-day shutdown, the longest on record. Market reaction has been contained, as the shutdown was not the primary driver of recent crypto weakness. Institutional flows, inflation trends, and labor-market softening remain the dominant influences.
ISM Services moved toward approximately 52, with new orders rising from around 50.4 to 56.2, signaling renewed momentum in services activity.
Challenger layoffs increased approximately 175 percent year-over-year to about 153 thousand in October, indicating continued weakening in employment.
NY Fed President Williams noted balance-sheet expansion may begin after quantitative tightening ends in December, while firm services-inflation data tempers expectations for a near-term rate cut.
Fund Flows: Institutional flows remain a key driver. The Coinbase Bitcoin Premium has stayed negative since October 30, indicating continued United States-based selling pressure.
Stablecoin activity paused: USDT supply held steady at 183.4 billion USD, USDC supply declined slightly to 75.6 billion USD, and weekly net flows turned marginally negative.
Key Headlines
European Union to update DLT Pilot Regime on December 3 to support tokenization and simplify participation.
Samourai Wallet developer sentenced to 5 years and fined 250,000 USD for operating an unlicensed money-transmission business.
United Kingdom preparing to launch stablecoin regulatory regime in line with United States timelines, including interim holding caps.
2. Key Macro Drivers – The Week Ahead (Nov 10 – 14)
Calendar
Nov 11: Aptos unlock (~11.31 million tokens)
Nov 13: United States CPI release and Bitfarms earnings
Nov 14: United States PPI and United States Retail Sales
View: The week ahead delivers the first major data prints since government reporting resumed. Updated inflation and consumption readings will help determine whether recent services strength persists and how quickly labor-market softness filters into broader activity. These releases will shape market expectations into the December Federal Reserve meeting.
3. Market Outlook – Liquidity, Bitcoin, Ethereum, Altcoins
Liquidity and Positioning
Total market capitalization: 3.53 trillion USD, down 4.6 percent
Weekly trading volume: 188 billion USD, up 23 percent
Bitcoin volume: 70.8 billion USD, up 29 percent
Ethereum volume: 42.3 billion USD, up 24 percent
Stablecoins
USDT supply stable at 183.4 billion USD
USDC supply lower at 75.6 billion USD
Net weekly flows slightly negative
ETF flows
Bitcoin ETF outflows of approximately 1.2 billion USD
Ethereum ETF outflows of approximately 509 million USD
Sentiment
Bitcoin sentiment: 15 percent (from 8 percent)
Ethereum sentiment: 30 percent (from 6 percent)
Bitcoin (BTC)
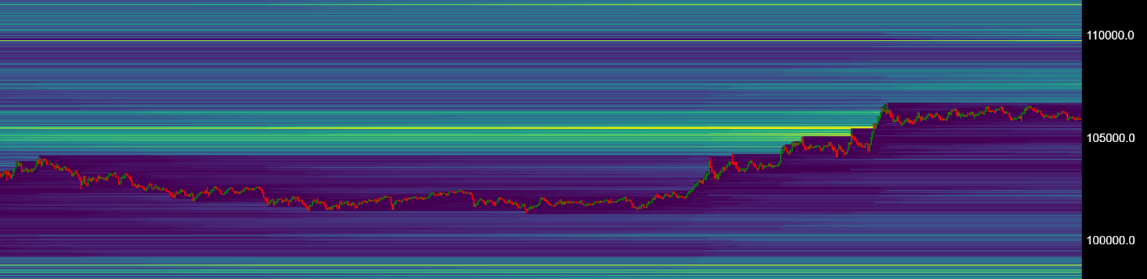
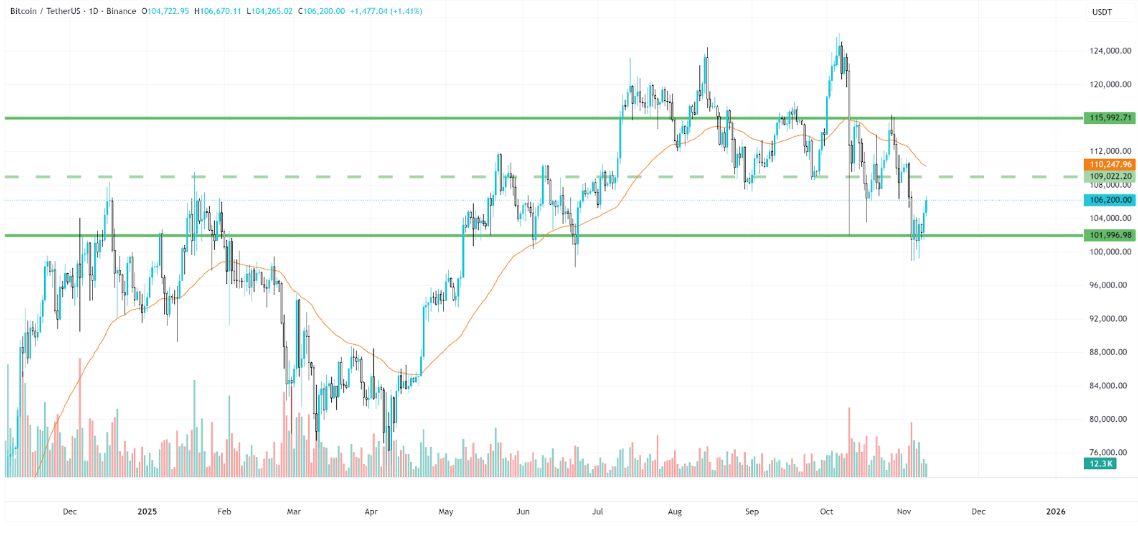
Bitcoin continued to hold the 100,000 USD support area across multiple sessions. Today’s price action delivered a relief rally, clearing the initial liquidity pocket near 105,500 USD and extending toward 106,500 USD. The next key objective is a sustained reclaim of the 110,000 USD region, with confirmation coming on a break and hold above the 110,000 to 116,000 USD zone.
Until those levels are secured, price action is likely to remain range-bound, with potential liquidity sweeps toward 104,000 USD and, if flows remain pressured, even below 100,000 USD. Continued ETF outflows or stronger United States macro data would increase the probability of deeper downside probes before a more durable recovery can form.
Ethereum (ETH)
Ethereum experienced a deeper positioning reset than Bitcoin. The 3,500 USD level remains the key support area, while a constructive shift requires a move above 3,750 USD, followed by a reclaim of 4,000 USD. Spot participation remains muted, and relative strength is likely to lag until inflows improve.
Altcoins
Altcoin strength remains selective and flow-dependent. Focus remains on higher-quality names with deeper liquidity. The Aptos unlock on November 11 presents near-term supply risk, encouraging a cautious stance across altcoin exposure until market inflows stabilize.

Copyright © 2026 Rain Trading Limited