


Weekly Crypto Outlook – March 9, 2026
Crypto markets enter the week with fragile momentum after Bitcoin briefly broke above $70,000 but failed to sustain the move. While ETF inflows and stablecoin demand remain supportive, weak macro data and US–Iran tensions continue to dominate market direction. The base case remains volatile consolidation unless Bitcoin reclaims the $73,000 level.

TL;DR
Crypto markets enter the week with mixed signals and fragile momentum. Bitcoin briefly broke above $70,000 last week on the back of a relief rally, likely helped by optimism around the New York Times reporting on Trump and Iran, but the move failed to hold, and much of the gain was later erased as downside liquidity was retested and weak US employment data reinforced growth concerns.
The near-term setup remains conflicted. On one hand, Bitcoin ETF inflows have stayed positive, USDC minting is accelerating, leverage has largely reset, and several valuation and sentiment indicators suggest the market is closer to a cyclical floor than to the start of a fresh capitulation leg. On the other hand, funding rates have turned sharply negative as new shorts are being established, spot volumes remain weak, and macro conditions remain hostage to the US–Iran conflict and its impact on oil, inflation, and Fed expectations.
This week, both technical and fundamental signals remain secondary to geopolitics. If tensions ease, the market has room for a tactical rebound. If they escalate again, the downside liquidity pools around $62,000 remain exposed.
Our base case is continued consolidation with elevated volatility, but with a greater risk of revisiting recent lows. That view would be invalidated if Bitcoin reclaims and holds above the $73,000 area.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Macro Drivers, The Week Ahead
Market Outlook
Macro View
Relief rally fades as geopolitics and stagflation risk dominate
Last week started with a relief rally, most likely supported by the New York Times article around Trump and Iran, but the market ultimately gave back much of that move. The reversal was accelerated by weak US employment data and renewed focus on the downside liquidity still sitting below spot.
The broader macro backdrop remains complicated. The February Non Farm Payroll report showed a loss of 92,000 jobs versus expectations for a gain of roughly 59,000, while unemployment rose to 4.4%. At the same time, wage growth surprised to the upside. That combination reinforces stagflation risk: weaker growth, but not enough disinflation to give the Fed immediate room to ease.
This is particularly relevant in the context of the Iran conflict. Oil prices remain highly sensitive to any escalation because of the strategic importance of the Strait of Hormuz. If tensions persist or intensify, higher energy prices could feed directly into goods inflation and keep the Fed cautious even as growth weakens.
For traditional risk assets, that is a difficult backdrop. For Bitcoin, the picture is more nuanced. The same dynamics that constrain central banks and expose the fragility of sovereign financial plumbing also reinforce Bitcoin’s structural properties as a non-sovereign, self-custodied asset.
Still, for this week, macro and fundamental drivers remain secondary to the geopolitical path. CPI on March 11 and Core Personal Consumption Expenditures on March 13 matter, but their market impact will be filtered through the lens of oil, inflation expectations, and the US–Iran situation.
Market Movers and Events, Last Week
Market data and flows
Crypto market cap: $2.29T, up 0.9% week on week
Average weekly volume: $109B, up 12%
Bitcoin weekly volume: $48.9B, up 19%
Ethereum weekly volume: $22.9B, up 10%
Ethereum network fees: 0.03 Gwei
At first glance, volumes improved, but the composition matters. Spot activity remains subdued, and the market still lacks the kind of broad participation needed to sustain a clean breakout.
Futures and positioning
Bitcoin funding rate: -2.5%
Bitcoin open interest: $20.7B, up $1.1B
Ethereum funding rate: -10.3%
Ethereum open interest: $10.9B, up $700M
Funding collapsed sharply last week as new shorts were established, especially in Ethereum. That leaves the market more defensive and more vulnerable to short squeezes if sentiment improves, but it also confirms that traders are still positioning cautiously rather than leaning into a clean recovery.
Whale distribution remains an important structural overhang. Over the past five months, roughly $30B of net outflows from large holders have weighed on price action. The positive offset is that this long distribution phase has also cleaned up market structure materially.
ETF flows
Bitcoin ETF flows over 7 days: +$568M
Ethereum ETF flows over 7 days: -$23M
Bitcoin ETF inflows remained constructive and are now marginally positive for March despite the broader macro stress.
Ethereum continues to struggle to attract sustained ETF demand.
Stablecoins and liquidity
USDT market cap: $183.9B, up 0.16% week on week
USDC market cap: $77.2B, up 2.8% week on week
Stablecoin net flows last week: +$2.4B
Stablecoin net flows over 30 days: +$3.8B
USDC is seeing particularly strong inflow demand, suggesting capital may be moving into stablecoins but has not yet been fully deployed into crypto markets.
Trading activity also increased, with USDT volume at $92B and USDC volume at $13.2B, both above recent averages.
Dominance
Bitcoin dominance: 58.3% Ethereum dominance: 10.3%
Bitcoin continues to outperform, and the broader altcoin model still argues for limited exposure.
Key headlines
ICE invests in OKX
Intercontinental Exchange, the owner of the New York Stock Exchange, acquired a stake in OKX valuing the exchange at approximately $25B.
Tokenised collateral gains institutional traction
A Nasdaq and ValueExchange report shows that 52% of institutions expect to be managing live tokenised collateral before the end of 2026.
SEC signals limits on leveraged ETFs
The SEC reportedly asked issuers to pause filings for highly leveraged single-security ETFs.
Key Macro Drivers, The Week Ahead
Mar 11: CPI - Inflation data will influence expectations around the Fed’s policy path.
Mar 13: Core Personal Consumption Expenditures - The Fed’s preferred inflation measure and a key indicator for assessing disinflation progress.
Ongoing US - Iran tensions: Geopolitical developments remain the dominant market driver.
Token Unlocks
Mar 12: Aptos (APT) – ~$10.5M Mar 13: WhiteBIT (WBT) – ~$4.18B Mar 14: pump.fun (PUMP) – ~$19.1M Mar 15: Starknet (STRK) – ~$4.8M Mar 15: Sei (SEI) – ~$3.6M
Market Outlook
Sentiment
Bitcoin Greed and Fear Index: 30% (vs. 15% last week)
Ethereum Greed and Fear Index: 35% (vs. 20% last week)
Sentiment has improved from the extreme fear levels seen last week, but overall positioning remains cautious and far from bullish territory.
Bitcoin
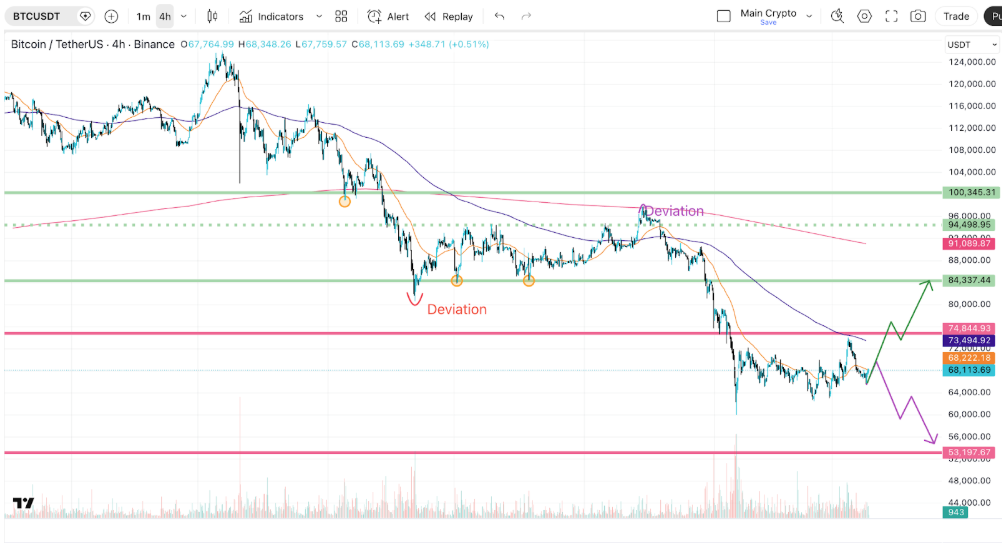
The market attempted to break above $70,000 last week but failed to hold the move, and the downside accelerated after weak payrolls.
This was in line with our midweek view that the relief rally had already cleared much of the upside liquidity and left the downside imbalance exposed again.
At the same time, Bitcoin’s resilience around geopolitical stress remains notable.
Key levels
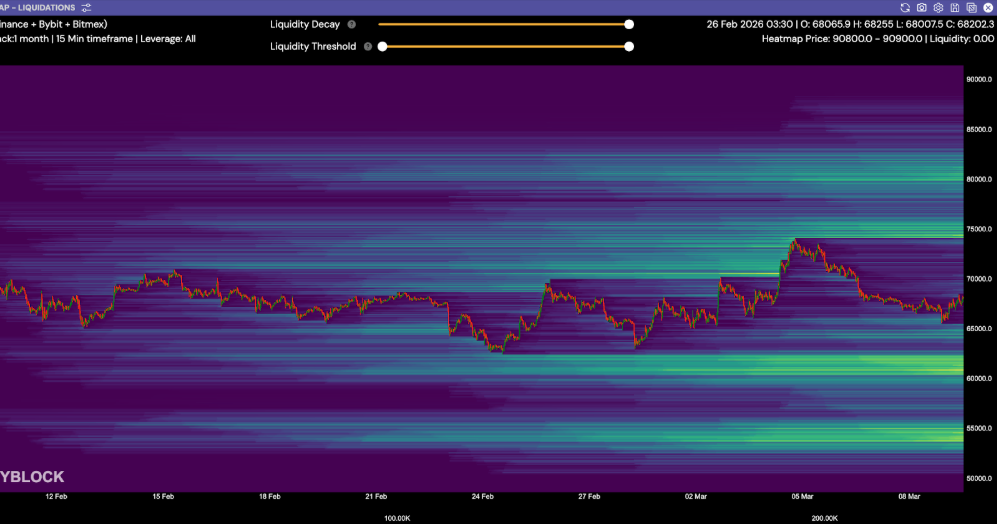
Current price: approximately $68,250
Immediate resistance: $70,000
Critical reclaim level: sustained hold above $73,500
Upside liquidity: $74,500
Downside liquidity pool: $62,000 and $54,000
Base case
Continued consolidation with elevated volatility remains the most likely near term scenario, with a higher probability of revisiting recent lows (purple path).
Unless Bitcoin can reclaim and sustain levels above $73,000, the market remains vulnerable to another move lower toward the $62,000 liquidity zone.
A sustained hold above $73,000 would invalidate the current downside scenario and shift the market toward the recovery path illustrated in green on our chart, opening the door for a broader rebound.
Ethereum
Ethereum remains structurally weaker than Bitcoin and continues to lack consistent institutional inflows.
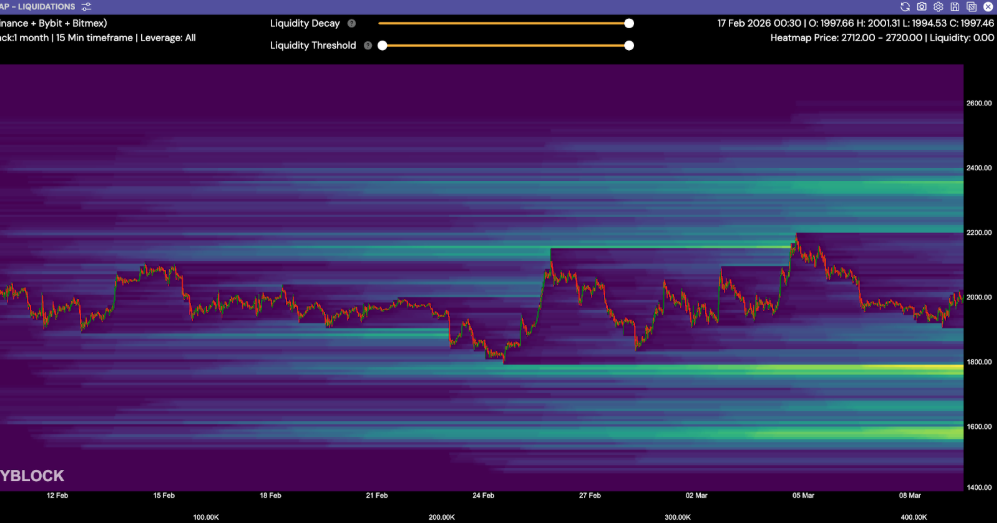
Key levels
Current price: approximately $2,000
Resistance: $2,100
Downside liquidity pool: $1,780 and $1,575
ETH remains reactive to Bitcoin and broader liquidity conditions.
Altcoins
The altcoin model remains cautious and selective. Bitcoin continues to attract defensive capital allocation while broader altcoin participation remains limited.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Trading Limited