



TL;DR
Crypto enters the week with weak liquidity, continued outflows, and limited directional conviction.
Total crypto market cap stands at $2.49T, down 2.4% from last week. Volume has improved slightly, but not enough to change the broader picture. ETF selling, stablecoin outflows, and weak spot participation continue to weigh on the market.
Bitcoin remains under pressure. The current scenario points to further weakness into the downside liquidity zone around $71.0K to $71.3K, with the larger $70K area still in focus. A relief rally would be more likely to develop from the $70K to $71K zone.
Ethereum remains weaker than Bitcoin, but it is now close to key short term support. ETH needs to hold the $1,970 to $1,975 zone and reclaim $2,050 to improve the short term setup.
Macro remains the main driver this week. The key U.S. events are Powell’s speech and ISM Manufacturing on Monday, June 1, ADP Employment and ISM Services on Wednesday, June 3, and the labor market report on Friday, June 5.
The key takeaway: stay cautious. Bitcoin can still produce a sharp relief rally if downside liquidity is taken first, but the broader structure remains fragile without stronger ETF flows, stablecoin minting, or a clear macro catalyst.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Headlines
Key Macro Drivers, The Week Ahead
Notable Token Unlocks
Market Outlook
Macro View
Macro remains uncomfortable for risk assets.
Equities continue to be supported by the AI rally, but bond markets are sending a more cautious message. Geopolitical pressure, the prolonged Strait of Hormuz blockade, and the risk of higher oil prices are keeping inflation concerns alive.
This matters for crypto because the market has shifted away from a clean rate cut narrative. If oil remains elevated and inflation pressure persists, the Fed has less room to ease. That keeps pressure on long duration and liquidity sensitive assets such as Bitcoin, Ethereum, and higher beta altcoins.
The divergence between equities and rates is also becoming harder to ignore. Equity markets are still behaving as if liquidity conditions can improve, while bond markets are increasingly focused on inflation and policy risk. Historically, these divergences do not last indefinitely.
For Bitcoin, the key question is whether rates markets are right. If higher for longer risk continues to build, crypto upside remains capped. If macro data weakens enough to bring rate cuts back into focus, Bitcoin could benefit quickly from its current depressed sentiment setup.
Market Movers and Events, Last Week
Market data and flows
Crypto market cap: $2.49T, down 2.4% WoW
Average weekly volume: $80B, 4% above average
Bitcoin weekly volume: $29.4B, 3% above average
Ethereum weekly volume: $13.1B, 5% below average
Ethereum network fees: 0.11 Gwei
Market activity remains weak despite a small improvement in aggregate volume. The issue is not only price action, but the lack of fresh capital entering the market.
Futures and positioning
Bitcoin funding rate: 4.8%
Bitcoin open interest: $24.5B, down $100M WoW
Ethereum funding rate: 14.7%
Ethereum open interest: $12.0B, up $200M WoW
Leveraged players are not showing strong directional conviction in Bitcoin. Open interest has barely moved, and funding remains moderate.
Ethereum is more concerning. Funding has increased while price action remains weak, suggesting long exposure is still too crowded relative to the underlying trend.
Dominance and rotation
Bitcoin dominance: 59.3%, down 0.7% WoW
Ethereum dominance: 9.7%, up 0.2% WoW
Bitcoin dominance has slipped below 60%, while Ethereum dominance remains below 10%.
This does not yet confirm a broad altcoin rotation. Instead, it suggests the market is becoming more selective. A few idiosyncratic altcoins can still outperform, but the broader liquidity backdrop does not support aggressive altcoin exposure.
Stablecoins and liquidity
USDT market cap: $188.4B, down 0.69% WoW
USDT volume: $68B, 4% above average
USDC market cap: $75.8B, down 0.8% WoW
USDC volume: $10.6B, 1% above average
Weekly stablecoin net change: minus $1.9B
30 day stablecoin minting: $0.6B
Stablecoins remain one of the weakest parts of the setup. The market is not seeing the type of fresh liquidity that normally supports a durable risk on move.
Stablecoin outflows, combined with ETF selling, point to an ongoing unwind of crypto exposure.
ETF and institutional flows
Year to date, crypto markets have seen $4.8B in total inflows, including $9.2B into Bitcoin and $6.5B out of Ethereum.
MicroStrategy remains one of the few visible structural buyers. However, the market is increasingly questioning how durable that buying power can remain if broader flows stay negative.
Sentiment
Bitcoin Greed and Fear: 10%, down from 25% last week
Ethereum Greed and Fear: 5%, down from 10% last week
Sentiment has quickly returned to extreme fear. This is tactically constructive, but sentiment alone is not enough. The market still needs a catalyst, either from macro, ETF flows, stablecoins, or new regulated product demand.
Key Headlines
Ondo Finance founder Nathan Allman passed away
Nathan Allman, founder and CEO of Ondo Finance, passed away unexpectedly on 25 May 2026 at age 32. No cause of death was disclosed.
Allman founded Ondo in 2021 after working on Goldman Sachs’s digital assets desk. The company became one of the leading tokenized real world asset platforms, with products including USDY, OUSG, and Ondo Global Markets.
Ian De Bode, who had served as president for more than 2 years, has assumed the CEO role with immediate effect.
Ethereum Foundation under renewed scrutiny
The Ethereum Foundation is facing renewed criticism after a wave of senior departures in 2026, including several in May.
Critics argue that the Foundation has become too insular and less responsive to a more competitive blockchain landscape. Vitalik Buterin has responded by outlining a narrower mandate focused on censorship resistance, openness, privacy, and security.
The key issue for markets is confidence. Ethereum already faces weak dominance, ETF outflows, and elevated funding. Governance uncertainty adds another layer of pressure at a time when ETH needs a stronger catalyst.
SoFi launches bank issued stablecoin
SoFi Technologies launched SoFiUSD on 27 May 2026, becoming the first U.S. national bank to offer a bank issued stablecoin directly inside a consumer banking app.
The token is redeemable 1:1 for U.S. dollars, backed by liquid assets, and runs on Ethereum and Solana.
This is structurally positive for the stablecoin sector. It reinforces the trend toward regulated bank participation, tokenized deposits, and 24/7 settlement infrastructure.
Bonds warn while equities celebrate
Equities remain supported by the AI rally, but bond markets are increasingly focused on geopolitical and inflation risk.
The Strait of Hormuz blockade remains the key pressure point. A longer disruption would increase the risk of higher oil prices and shortages in key raw materials, keeping inflation pressure elevated.
For Bitcoin, this creates a difficult setup. Equity strength can support risk appetite in the short term, but rates markets may ultimately matter more if inflation expectations rise again.
ETF flows fade while derivatives activity picks up
Bitcoin’s early May rally was driven mainly by ETF inflows and continued buying from digital asset treasuries, while derivatives activity remained subdued.
That has now changed. ETF flows have turned negative, while perpetual futures funding has increased.
This suggests the market is becoming more speculative again, but without the same institutional spot support that helped drive the earlier rally.
Key Macro Drivers, The Week Ahead
Monday, June 1: Powell speech
Powell’s speech is the first major macro event of the week.
Markets will watch for any signal on whether the Fed remains focused on inflation risk or is becoming more open to future easing. A hawkish tone would pressure crypto, especially if it reinforces higher for longer expectations.
Monday, June 1: ISM Manufacturing PMI
ISM Manufacturing will help clarify whether U.S. growth is slowing or stabilizing.
A stronger print could support the idea that the economy remains too resilient for rate cuts. A weaker print would be more supportive for Bitcoin, especially if it brings policy easing back into focus.
Wednesday, June 3: ADP Employment Change
ADP will be watched as an early read on labor market strength before Friday’s payrolls report.
A soft print would support the case for slower growth and easier policy. A strong print would reduce pressure on the Fed to cut rates.
Wednesday, June 3: ISM Services PMI
ISM Services is especially important because services inflation remains central to the Fed’s reaction function.
A strong services print would be negative for crypto, as it would reinforce inflation stickiness and limit the room for policy easing.
Friday, June 5: Labor market report
The main events on Friday are:
Average Hourly Earnings MoM
Average Hourly Earnings YoY
Nonfarm Payrolls
This is the most important U.S. data set of the week. Payrolls will drive the growth narrative, while wages will drive the inflation narrative.
For crypto, the best outcome would be softer employment growth without a wage acceleration. The worst outcome would be strong payrolls and sticky wage growth, which would support higher rates and pressure risk assets.
Notable Token Unlocks, June 1 to June 7
Hyperliquid, HYPE
Unlock type: ongoing linear vesting
Approximate value: $39.04M
Supply impact: 4.4%
HYPE remains one of the strongest altcoins, but ongoing linear supply remains worth monitoring after a large rally.
Ethena, ENA
Unlock date: June 2
Approximate value: $18.61M
Supply impact: 0.49%
Unlock type: linear vesting
The dollar value is meaningful, but the circulating supply impact is limited.
Sui, SUI
Unlock date: June 1
Approximate value: $13.10M
Supply impact: 0.36%
Unlock type: cliff release
SUI remains relevant given recent market attention, but this unlock is manageable relative to circulating supply.
EigenCloud, EIGEN
Unlock date: June 1
Approximate value: $7.80M
Supply impact: 6.55%
Unlock type: cliff release
This carries more dilution risk given the larger supply impact.
Optimism, OP
Unlock date: May 31 / June 1
Approximate value: $3.91M
Supply impact: 1.50%
Unlock type: core contributor and investor
Moderate supply impact, but still worth monitoring given weak broader liquidity.
Market Outlook
Bitcoin
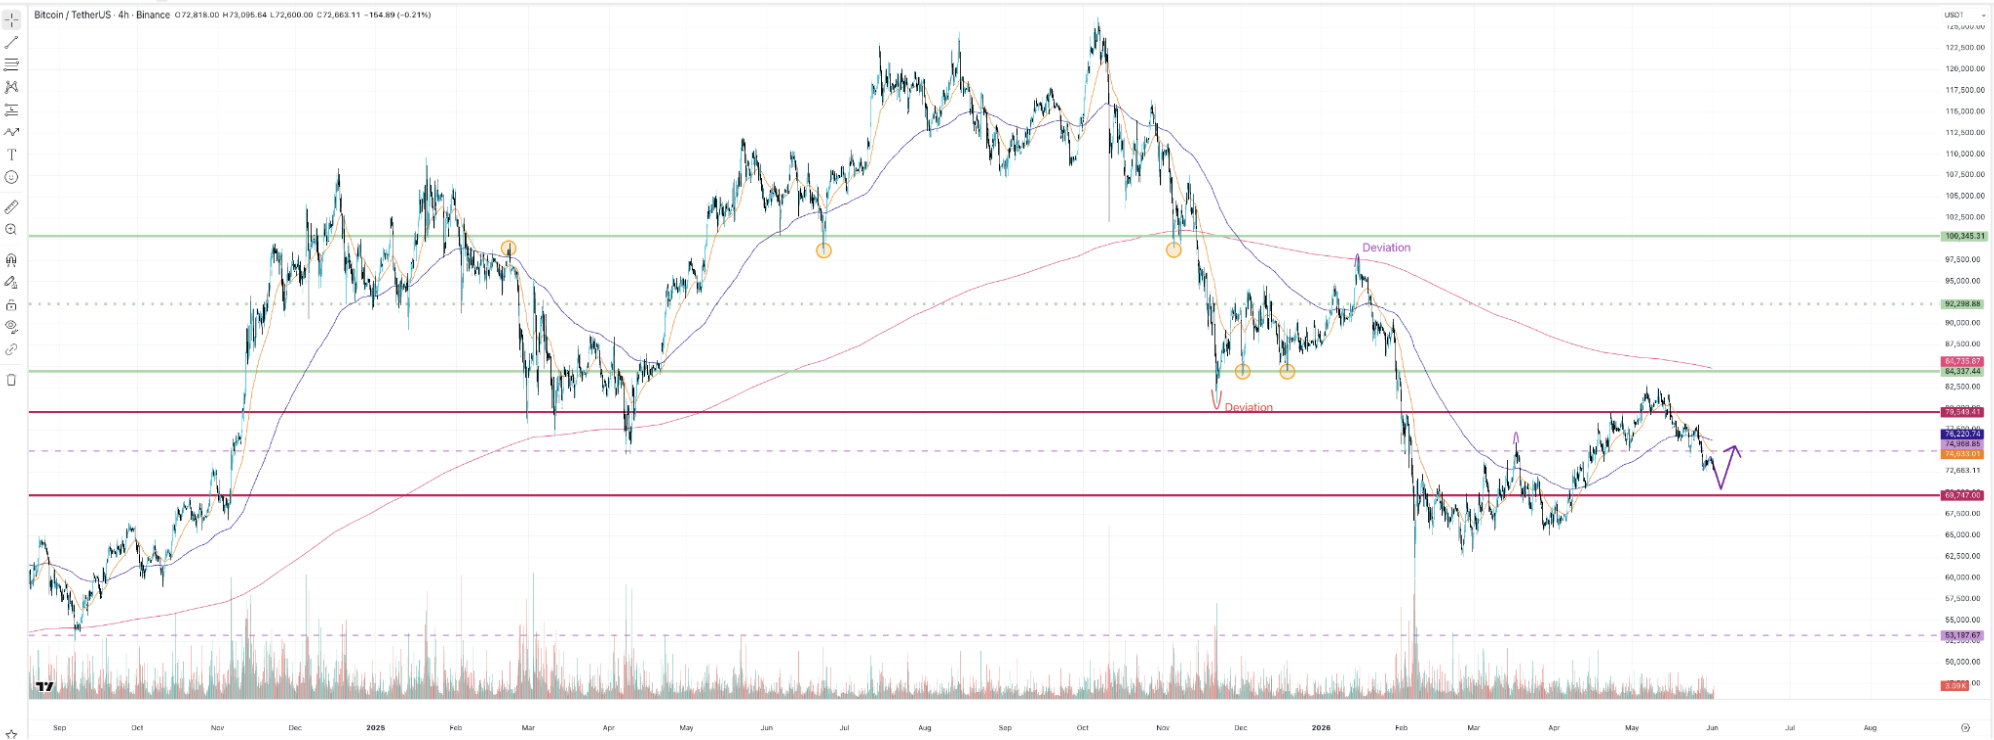
Support zone: $72.2K
Key short term level: $73.0K
Major bull or bear level: $72.2K
Upside liquidity zone: $73.5K to $74.0K
Larger upside catalyst zone: $76.0K to $78.0K
Downside liquidity zone: $71.0K to $71.3K
Larger downside liquidity zone: $70.0K
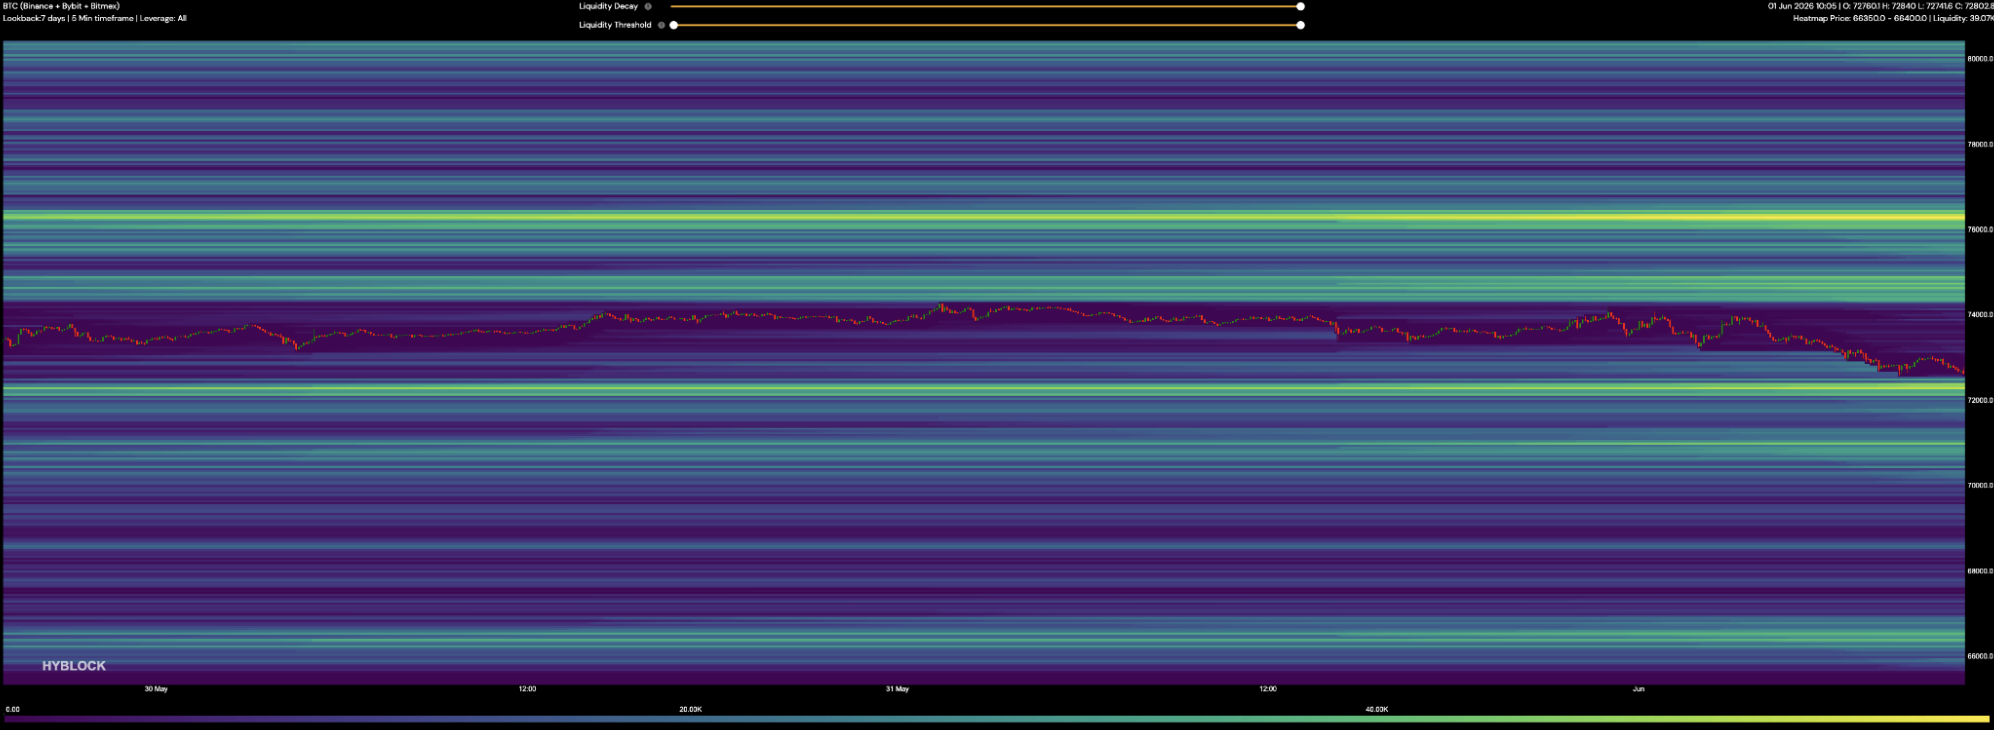
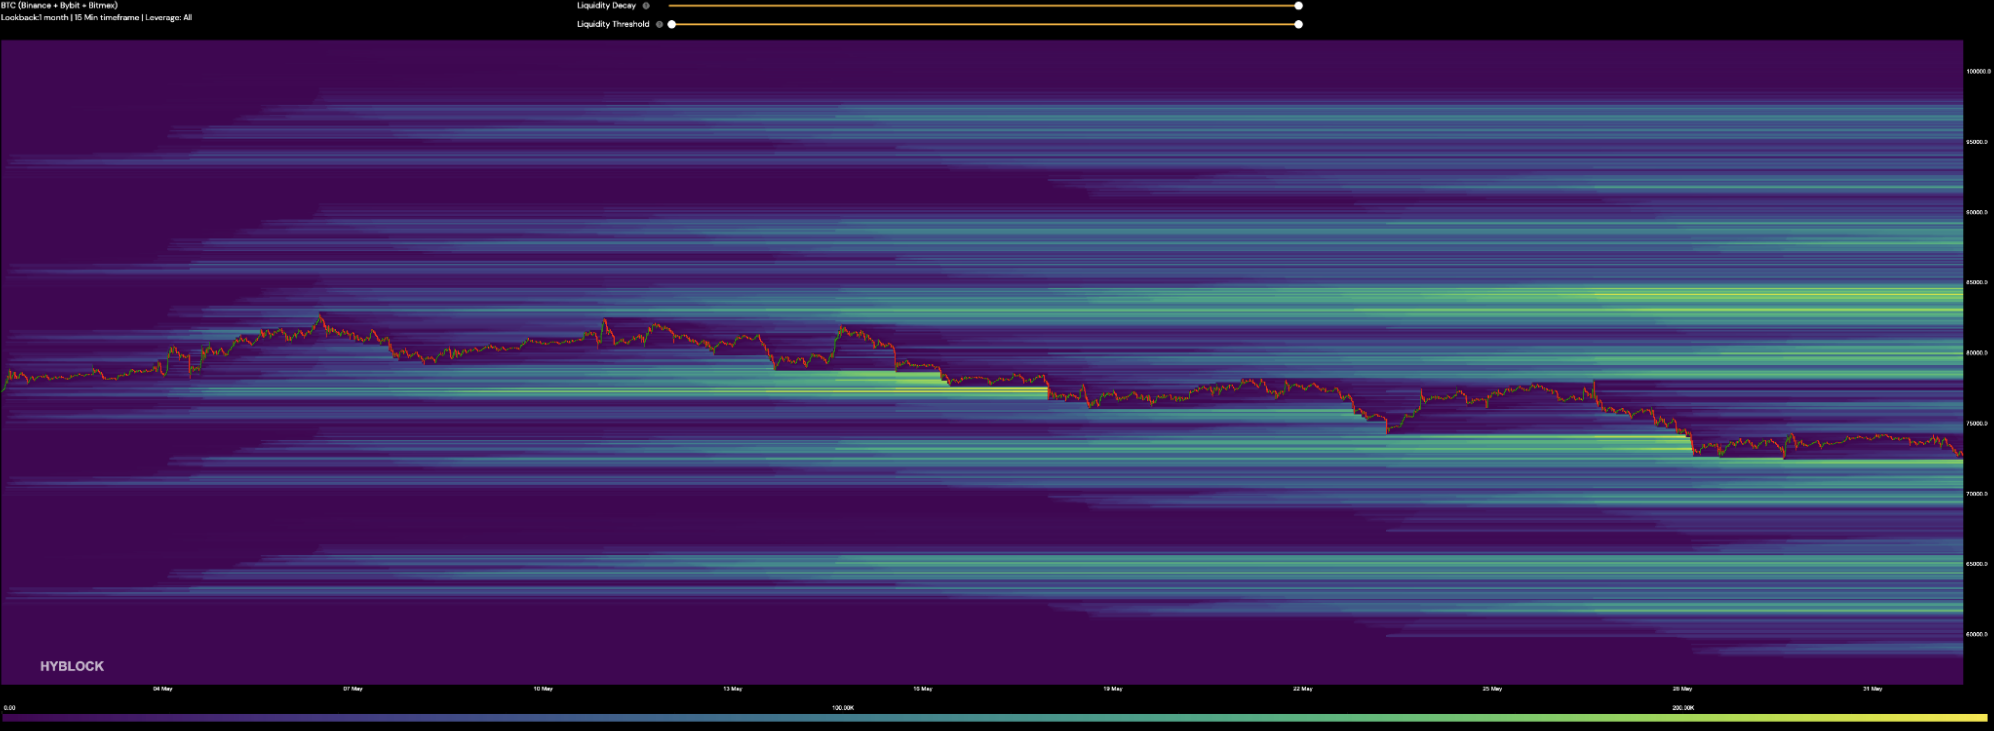
Bitcoin remains under pressure, and the current scenario points to further weakness into the downside liquidity zone.
The immediate support area is now $72.2K, with $73.0K as the key short term level. Unless Bitcoin reclaims and holds above this area, the market is likely to continue looking lower.
The preferred scenario is a move into the $71.0K to $71.3K downside liquidity zone. A deeper sweep toward $70K would also fit the current structure.
We would expect a relief rally to be triggered from the $70K to $71K zone, especially if sentiment remains at extreme fear and forced selling begins to slow.
On the upside, the first liquidity zone is $73.5K to $74.0K. A stronger recovery would need to reclaim that area before the larger $76K to $78K zone comes back into focus.
Ethereum
Support zone: $1,970 to $1,975
Key short term level: $2,000
Major bull or bear level: $2,030
Bullish reclaim level: $2,050
Upside liquidity zone: $2,080 to $2,100
Larger upside catalyst zone: $2,150 to $2,180
Downside liquidity zone: $1,950 to $1,970
Larger downside liquidity zone: $1,900 to $1,920
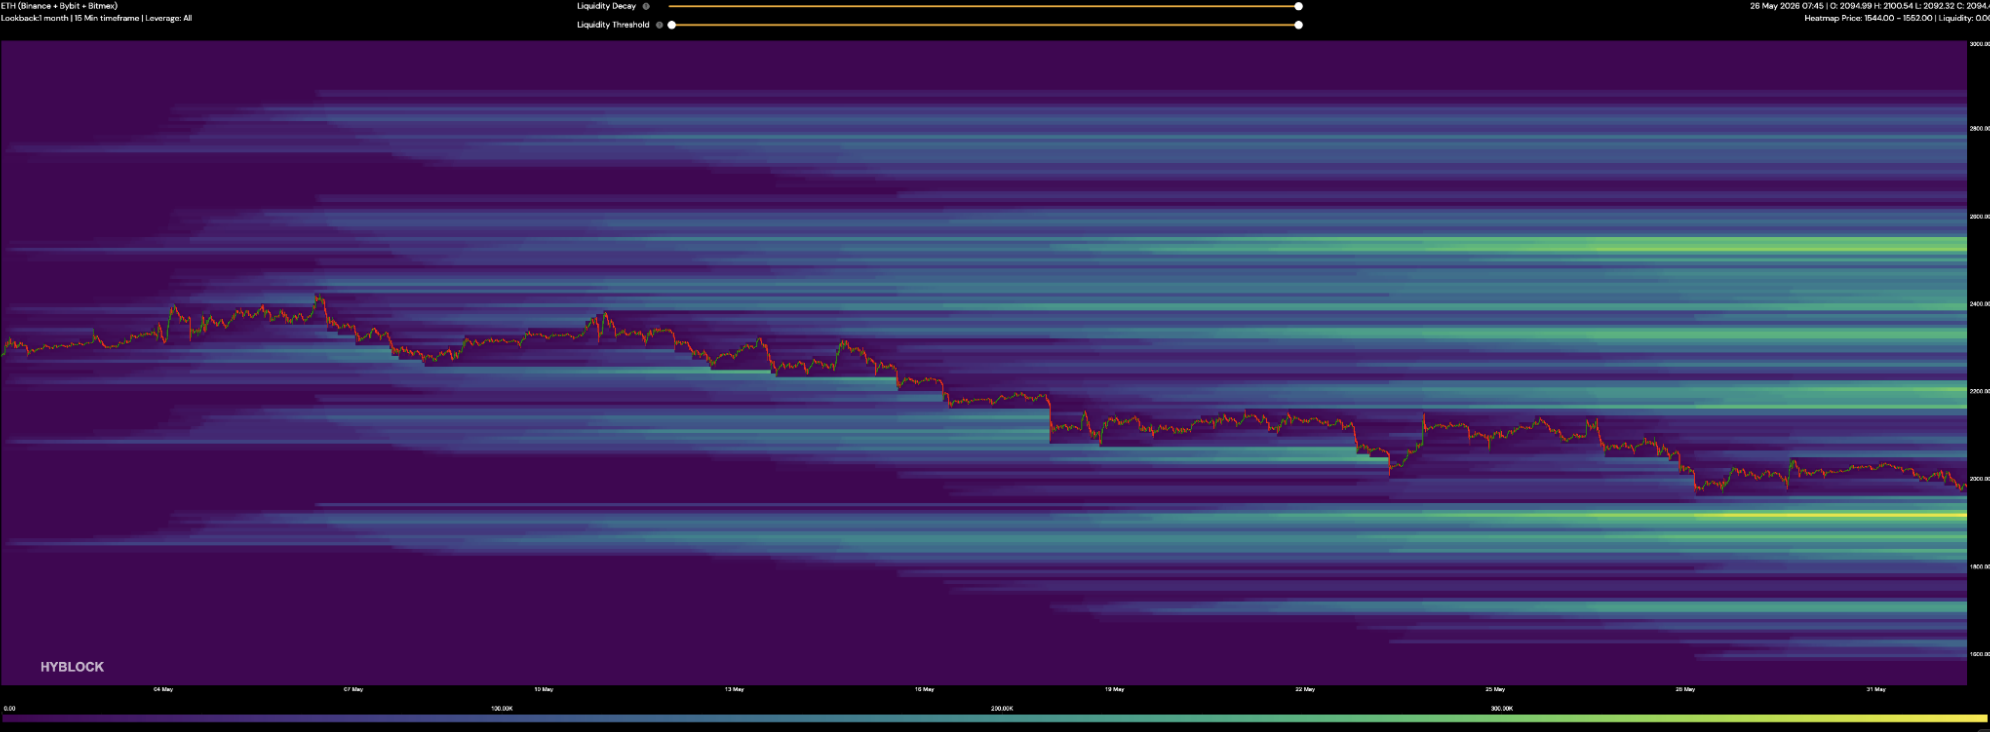
Ethereum remains weaker than Bitcoin, but the setup is now very close to key short term support.
The immediate support zone is $1,970 to $1,975, with $2,000 as the key short term level. The major bull or bear level is $2,030.
If Ethereum loses the $1,970 area, the next downside liquidity zone is $1,950 to $1,970, followed by the larger downside zone at $1,900 to $1,920.
On the upside, ETH first needs to reclaim $2,050 to improve the short term structure. A move through that level would open the path toward $2,080 to $2,100, with $2,150 to $2,180 as the larger upside catalyst zone.
The relative value view remains unchanged: favor Bitcoin over Ethereum until ETH shows a cleaner reclaim and stronger market leadership.
Altcoins
Altcoin exposure should remain selective.
Bitcoin dominance has slipped below 60%, but this does not yet confirm a broad altcoin rotation. Stablecoin liquidity is weak, ETF flows are negative, and Ethereum remains structurally weak.
That said, individual altcoins can still outperform where there is a clear catalyst, strong product momentum, or unique market structure.
Hyperliquid remains the clearest example. HYPE continues to benefit from strong protocol activity, expanding synthetic markets, and continued interest following the launch of the SpaceX pre IPO perpetual futures contract.
However, this week also brings ongoing HYPE linear vesting, worth roughly $39.04M, so momentum should be monitored carefully.
Outside of strong idiosyncratic names, broader altcoin exposure should remain limited until stablecoin growth improves, Ethereum stabilizes, and ETF selling slows.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Trading Limited