


Weekly Crypto Outlook – January 19, 2026
Crypto markets enter the third week of January with price action unfolding firmly in line with last week’s downside roadmap. Bitcoin completed its upside liquidity run into the weekly 50 EMA near USD 97,600, rejected sharply, broke below USD 94,500, and is now trading toward USD 92,500.

TL;DR
Crypto markets enter the third week of January with price action unfolding firmly in line with last week’s downside roadmap. Bitcoin completed its upside liquidity run into the weekly 50 EMA near USD 97,600, rejected sharply, broke below USD 94,500, and is now trading toward USD 92,500. This confirms that the move was liquidity-driven rather than the start of a new trend. With leverage still elevated relative to participation, ETF flows mixed, and liquidity creation lagging, the balance of risk is skewed to the downside. Escalating geopolitical headline risk linked to renewed US tariff threats toward Europe materially raises the probability of sharp volatility this week. The base case remains further downside toward key liquidity and liquidation zones before a more durable base can form. Altcoins should be approached selectively, with uneven performance likely in a high-volatility environment.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Macro Drivers, The Week Ahead
Market Outlook
Macro View
From positioning dominance to volatility realization
Macro drivers remain secondary to flows and positioning, but headline risk has risen sharply. Bitcoin’s move last week followed the expected pattern: a liquidity-driven rally into a major technical reference point, followed by rejection once positioning became stretched.
Bitcoin reached the weekly 50 EMA near USD 97,600 midweek, fulfilling the upside objective outlined in the prior outlook. The subsequent failure to hold above USD 94,500, followed by a steady decline toward USD 92,500, confirms the move lacked durable participation and fresh liquidity support.
Geopolitical risk has re-emerged as a volatility catalyst. US President Donald Trump’s announcement of potential 10% to 25% tariffs on several European allies, tied to negotiations around Greenland, has drawn strong reactions from European leaders and increased the risk of broader trade escalation. While not crypto-specific, these developments raise cross-asset volatility risk in thin January liquidity and are likely to amplify positioning-driven moves.
The broader setup remains fragile. Leverage rebuilt faster than liquidity, participation stayed selective, and stablecoin issuance remained insufficient to absorb shocks. This configuration increases the probability of sharp directional moves as downside liquidity comes into focus.
Market Movers and Events, Last Week
Market data and flows
Crypto market capitalization rebounded to USD 3.23 trillion, up 4.5% week on week
Average weekly trading volume rose to USD 112 billion, 8% above average
Bitcoin weekly volume reached USD 42.5 billion, 8% above average
Ethereum weekly volume increased to USD 23.5 billion, 17% above average
Ethereum network fees remain near 0.04 Gwei, confirming subdued on-chain activity
Futures and positioning
Bitcoin funding declined to 4.1%, while open interest increased to USD 29.8 billion
Ethereum funding fell to 3.4%, with open interest rising to USD 18.5 billion
This confirms the rebound was not leverage-led, with futures traders adding exposure cautiously while remaining vulnerable to downside moves.
ETFs
Bitcoin ETF inflows totaled approximately USD 1.4 billion over the past week
Ethereum ETFs recorded USD 479 million in outflows
ETF flows have improved for Bitcoin but remain inconsistent, reinforcing the view that allocator demand is tactical rather than persistent.
Stablecoins
USDT market cap: USD 186.9 billion, flat week on week
USDC market cap: USD 75.9 billion, up 1.7% week on week
Net stablecoin flows turned modestly positive last week, but remain negative year to date
Liquidity creation is improving only marginally and remains insufficient to support sustained upside.
Dominance
Bitcoin dominance: 58.5%
Ethereum dominance: 12.1%
Relative performance has begun to tilt toward higher beta assets, though leadership remains selective.
Key headlines
SBF not pardoned: President Trump ruled out clemency for former FTX CEO Sam Bankman-Fried, ending months of speculation.
Senator Lummis criticizes DOJ Bitcoin sales: Concerns raised over potential BTC sales conflicting with the Strategic Bitcoin Reserve policy.
Florida renews Bitcoin reserve proposal: New legislation introduced to hold BTC as a state-level reserve asset.
US bill targets prediction markets: Proposed legislation would restrict government officials from trading on platforms like Polymarket.
Key Macro Drivers, The Week Ahead
Thin liquidity conditions mean macro and geopolitical headlines may have outsized impact.
Economic calendar
Jan 19–23: World Economic Forum (Davos)
Jan 20: ADP Employment Change
Jan 22: US GDP (Q4, annualized)
Jan 22: Core PCE (MoM)
Jan 23: S&P Global Manufacturing PMI
Jan 23: Michigan Consumer Expectations
Escalating US–Europe tariff rhetoric significantly raises the risk of abrupt sentiment shifts, particularly around US data releases.
Market Outlook
Sentiment
Bitcoin Greed & Fear Index: 76%
Ethereum Greed & Fear Index: 81%
Sentiment has improved but remains vulnerable given deteriorating structure.
Bitcoin
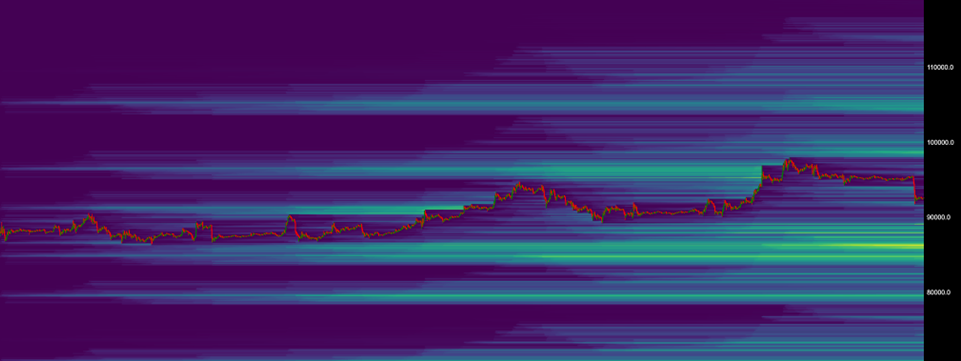
Bitcoin is no longer in a short-term bullish trend. The rejection at the weekly 50 EMA near USD 97,600, followed by a break below USD 94,500 and continuation lower toward USD 92,500, confirms that the recent advance was a completed liquidity run rather than a trend reversal. Price action is now fully aligned with last week’s downside scenario.
Volatility is expected to increase as price approaches key downside liquidity zones.
Immediate downside liquidity: USD 90,500
Major liquidation pools: USD 86,200 and USD 79,800
With upside liquidity largely exhausted and positioning still elevated relative to participation, the balance of risk remains skewed to the downside. Any short-term rebounds should be treated as corrective unless price can reclaim and sustain levels above USD 94,500. The path of least resistance remains toward lower liquidity, where a more durable base may eventually form.
Ethereum
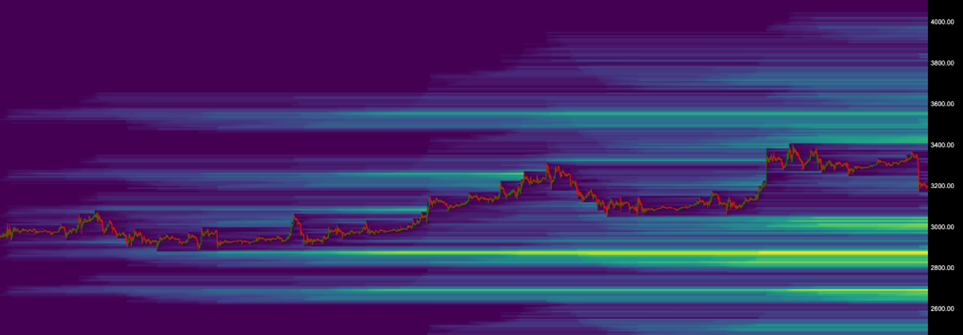
Ethereum continues to lag Bitcoin and has also transitioned out of a constructive short-term setup. The inability to sustain strength following Bitcoin’s rejection has left ETH vulnerable to downside continuation in a high-volatility environment.
Immediate downside liquidity: USD 3,000
Major liquidation pools: USD 2,850 and USD 2,650
Funding has eased, but open interest remains elevated relative to participation, increasing sensitivity to broader market moves. Until Ethereum can reclaim and hold above USD 3,200, price action should be viewed as fragile, with downside liquidity increasingly in focus.
Altcoins
As Bitcoin and Ethereum move deeper into corrective territory, altcoin performance is expected to remain uneven. Liquidity is selective, participation is thin, and price action is increasingly driven by broader market volatility rather than fundamentals. Any strength should be treated tactically, while downside risk increases if liquidation cascades develop in majors.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Trading Limited