


Weekly Crypto Outlook – February 16, 2026
Crypto markets have entered a fragile stabilization phase following the February 6th liquidation low near $60,000. ETF outflows and shrinking liquidity continue to pressure prices, while $75,000 stands out as the key level signaling a transition toward recovery. Macro conditions are gradually turning more constructive over the medium term.

TL;DR
Crypto markets have transitioned from a forced liquidation regime into a fragile stabilization phase after the February 6th low near $60,000. While the immediate panic phase appears to have passed, liquidity conditions remain weak, ETF outflows persist, and stablecoin supply continues to contract, suggesting the recovery remains tentative rather than confirmed. Macro conditions are gradually turning more constructive, with slowing growth, cooling inflation, and increasing probability of further monetary easing over time. Structurally, institutional adoption continues to accelerate, and near-term price action is likely to remain range-bound and liquidity-driven, with $75,000 emerging as the key level that would signal a transition from stabilization to recovery.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Macro Drivers, The Week Ahead
Market Outlook
Macro View
Late-cycle deceleration continues, but policy backdrop is improving
Recent macro data reinforces a clear trend: the US economy is slowing at the margin, but not collapsing. Headline nonfarm payrolls rose by 130k, modestly above expectations, but prior months were revised sharply lower by a combined 175k. On a rolling three-month basis, job growth has slowed significantly compared to last year, confirming gradual labour market weakening.
Retail sales also disappointed, reinforcing that consumer activity is cooling. Inflation continues to trend lower, with Core CPI at 2.4% year-on-year, its lowest level in eight months. Importantly, inflation is declining even as the Fed has begun cutting rates, meaning real rates remain restrictive. This leaves room for further easing if economic weakness persists.
Broader labour market revisions reinforce this trend. Over the past three years, US job creation has been revised lower by more than 2 million jobs cumulatively, highlighting structural weakness beneath headline data. Job openings have declined significantly, confirming that labour demand is softening.
From a crypto perspective, this macro mix is structurally constructive over the medium term. Slower growth, falling inflation, and eventual easing liquidity conditions historically support Bitcoin. However, near-term price action remains dominated by liquidity, positioning, and derivatives dynamics.
Market Movers and Events, Last Week
Market data and flows
Crypto market cap: $2.35T, down 2.1% week-on-week
Average weekly volume: $100B, down 49%
Bitcoin weekly volume: $43.3B, down 47%
Ethereum weekly volume: $21.4B, down 58%
Ethereum network fees: 0.04 Gwei, reflecting extremely low activity
The sharp decline in trading volumes confirms weak conviction and reduced market participation following the liquidation phase.
Futures and positioning
Bitcoin funding rate: 3.2%
Bitcoin open interest: $20.5B, down $1.2B
Ethereum funding rate: 6.4%
Ethereum open interest: $10.2B, up slightly
Positioning has reset following forced liquidations. Lower open interest reduces immediate liquidation risk but reflects limited conviction.
ETF flows
Bitcoin ETF flows (7d): -$359M
Bitcoin ETF flows (30d): -$2.9B
Ethereum ETF flows (7d): -$161M
Ethereum ETF flows (30d): -$912M
ETF outflows remain a significant liquidity headwind and contrast sharply with strong inflows seen last year.
Stablecoins and liquidity
USDT market cap: $183.7B, down 0.43%
USDC market cap: $73.6B, up 1.1%
Net stablecoin outflows (30d): -$2.1B
Estimated crypto liquidity change YTD: -$20.1B
Liquidity continues to leave the ecosystem, reinforcing fragile market conditions.
Dominance
Bitcoin dominance: 58.5%
Ethereum dominance: 10.0%
Bitcoin continues to outperform relative to altcoins, reflecting defensive positioning.
Key headlines
US crypto legislation continues progressing
Senator Mark Warner pushed to advance the Digital Asset Market Clarity Act, while SEC Chairman Paul Atkins confirmed that lasting regulatory clarity requires formal legislation. This reinforces that the US is moving gradually toward a stable institutional regulatory framework.
Coinbase earnings highlight trading slowdown but strong stablecoin growth
Coinbase missed Q4 expectations, reflecting weaker trading activity and cyclical liquidity contraction. However, stablecoin revenue reached a record $364M, and USDC balances hit an all-time high, reinforcing continued structural growth in on-chain settlement.
Corporate Bitcoin accumulation remains strong
Strategy acquired 40,150 BTC in January, bringing total holdings to 712,647 BTC and accounting for nearly all corporate buying. Corporate treasury adoption continues to expand globally, reinforcing sustained institutional demand despite recent market weakness.
Key Macro Drivers, The Week Ahead
Macro and policy events
Feb 16: US markets closed (bank holiday): Lower liquidity conditions may produce irregular price action and exaggerated volatility, particularly in crypto markets which continue to trade continuously.
Feb 17 onward: Chinese New Year: Seasonal liquidity slowdown across Asia may reduce trading activity and delay institutional positioning until full market participation resumes.
Feb 18: FOMC minutes: Markets will look for confirmation of a dovish policy trajectory. Any indication of accelerated easing would be supportive for risk assets, including crypto, through lower real yields and improved liquidity expectations.
Feb 20: US GDP release: A weaker-than-expected GDP print would reinforce the late-cycle slowdown narrative and increase expectations of further monetary easing, which historically supports Bitcoin over the medium term.
Feb 20: Core PCE inflation: As the Fed’s preferred inflation measure, continued disinflation would strengthen the case for additional rate cuts and improve the macro liquidity outlook.
Feb 20: Supreme Court tariff ruling: Trade policy uncertainty remains a key macro risk factor. Escalation in tariff tensions could temporarily pressure risk assets, while resolution would support broader market stability.
Market Outlook
Sentiment
Extreme bearish sentiment persists but is stabilizing. Such sentiment levels typically coincide with late-stage liquidation and potential stabilization phases.
Bitcoin
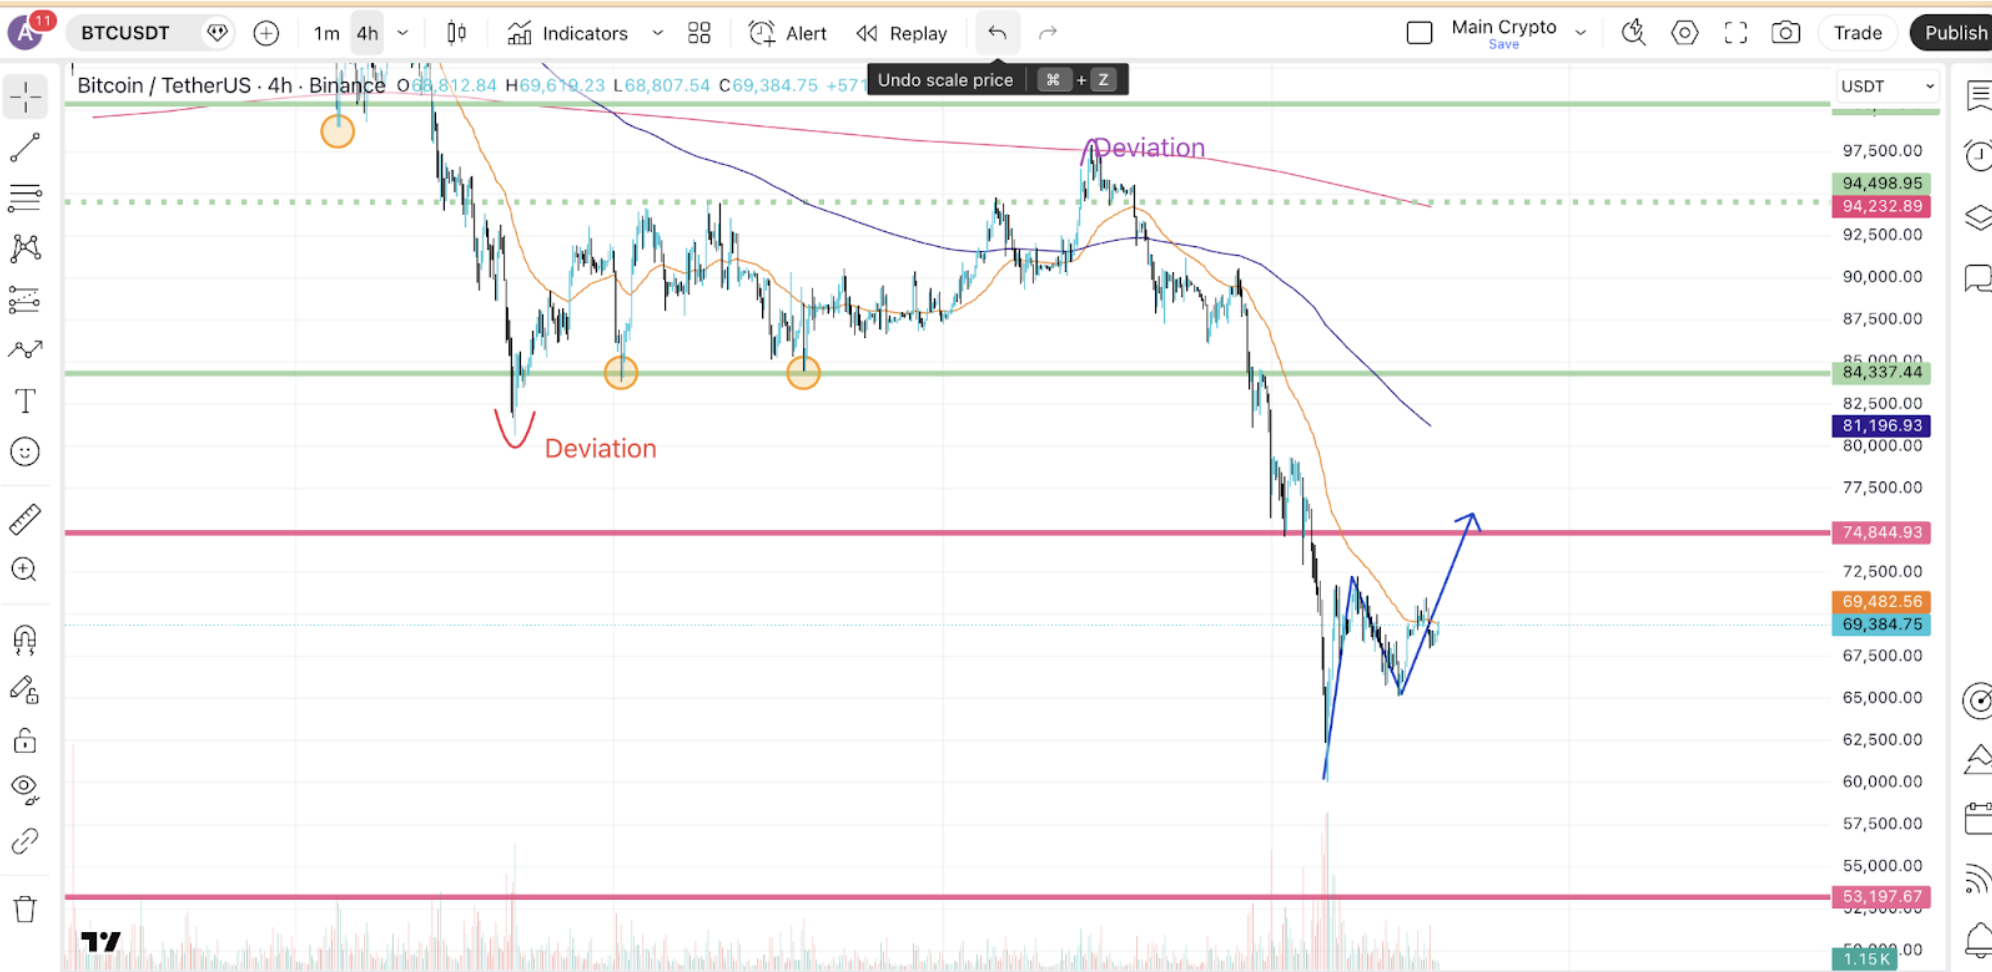
Bitcoin established a local low near $60,000 on February 6th, completing a major liquidation phase and clearing significant downside liquidity. Price has since recovered into a historically important multi-month range that previously contained price for extended periods.
Re-entry into this range suggests a transition from directional liquidation into consolidation.
Key levels
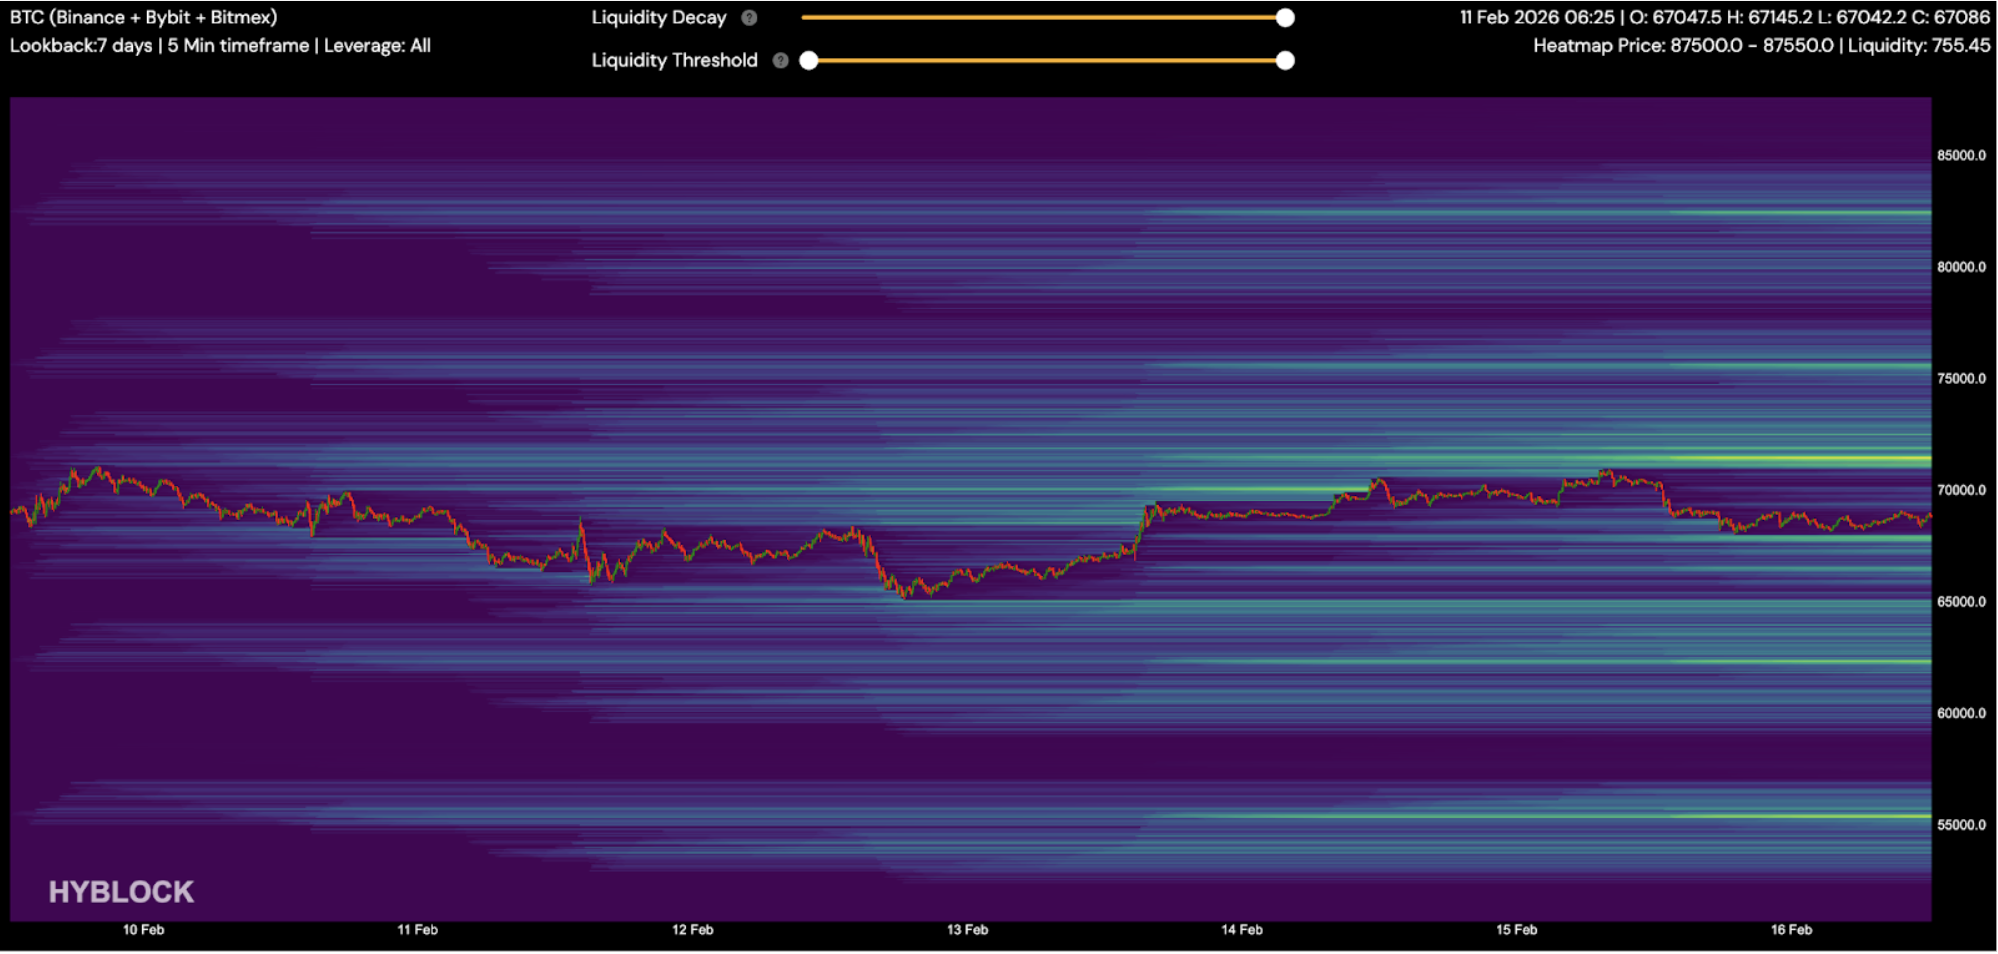
Current price: approximately $68,800
Liquidity pool to the upside: $71,500
Recovery trigger: reclaim and sustained hold above $75,000
Bearish continuation trigger: loss of $65,000 would open the path toward new cycle lows
Base case
Bitcoin is likely to continue recovery toward the upside liquidity pool at $71,500, with the next key objective being a move toward the top of the range at $75,000. Clearing these levels would confirm strengthening market structure and increase the probability of a broader stabilization phase.
Downside scenario
Failure to sustain current range support and loss of the $65,000 level would invalidate the stabilization structure and increase the probability of continuation toward new cycle lows.
Ethereum
Ethereum remains structurally weaker than Bitcoin and continues to reflect lower institutional conviction and persistent ETF outflows.
Key levels
Current price: approximately $1,959
Recovery trigger: reclaim and sustained hold above $2,200
Liquidity pool to the downside: $1,890
ETH will remain reactive to Bitcoin and broader liquidity conditions.
Altcoins
Altcoin performance remains fragile in low-liquidity conditions. Bitcoin continues to attract relative strength as the lowest-risk crypto asset during uncertain market conditions.
Hyperliquid (HYPE) remains one of the stronger performers structurally, though positioning should remain tactical.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Trading Limited