



TL;DR
Year-end liquidity continues to thin across crypto markets, shifting price dynamics away from macro headlines and toward positioning and liquidation mechanics. Both Bitcoin and Ethereum remain within broader bearish structures, but leverage has been meaningfully reduced, lowering immediate downside tail risk. Liquidation maps suggest a higher probability of an upside sweep before any sustainable reversal, though a final downside probe cannot be ruled out. Markets are likely to remain tactical and range-bound, with confirmation levels required before adopting directional exposure. Discipline and patience remain critical into year-end.
In this week’s note
Macro View
Market Movers & Events – Last Week
Key Macro Drivers – The Week Ahead
Market Outlook
1. Macro View
Liquidity tightening beneath a stable macro surface
Macro clarity has improved, but it has not translated into renewed risk appetite. US inflation data surprised to the downside and labor market indicators continue to soften, reinforcing expectations for further Fed easing in 2026. However, central banks globally are signaling a slower and more cautious easing path. The Bank of England emphasized gradualism, the ECB revised growth and inflation projections higher, and the Bank of Japan delivered a hike with limited forward guidance.
For crypto markets, this backdrop remains restrictive rather than supportive. Liquidity is no longer tightening aggressively, but it is not expanding sufficiently to sustain upside momentum. With few near-term macro catalysts, price action into year-end is increasingly governed by internal liquidity, positioning, and derivatives dynamics.
2. Market Movers and Events – Last Week
Price action and volumes
Crypto market capitalization stands at approximately USD 2.98 trillion, down 2.9% week on week.
Average weekly trading volumes declined to USD 108 billion, materially below average.
Bitcoin weekly volume was USD 44.9 billion.
Ethereum weekly volume was USD 21.7 billion.
Ethereum network fees remain around 0.04 Gwei, consistent with subdued on-chain activity.
Futures and positioning
Bitcoin funding rose to 5.1% over the week, while BTC futures open interest declined by approximately USD 0.4 billion to USD 27.8 billion.
Ethereum funding increased to 3.5%, with ETH futures open interest declining by approximately USD 0.6 billion to USD 18.0 billion, though still elevated in absolute terms.
Across both assets, rising funding alongside falling open interest confirms continued leverage reduction rather than renewed directional conviction.
ETFs
ETF flows remain a headwind into year-end.
Bitcoin ETFs recorded USD 496 million in outflows over the past 7 days and approximately USD 300 million in net outflows in December.
Ethereum ETFs saw USD 644 million in outflows over the past 7 days, though December remains modestly positive overall.
Dominance
Bitcoin dominance stands at 59.0%, up week on week.
Ethereum dominance stands at 12.0%, down week on week.
This shift continues to favor Bitcoin over broader altcoin exposure.
Stablecoins
Stablecoin flows weakened further following a USD 1.5 billion USDC off-ramp.
USDT market capitalization is USD 186.8 billion, up 0.32% week on week, though volumes remain subdued.
USDC market capitalization declined to USD 77.0 billion, down 1.8% week on week.
Overall stablecoin supply contracted by approximately USD 0.8 billion last week, reinforcing the view that liquidity is being withdrawn rather than redeployed into risk assets.
Key Headlines
DTCC to tokenise US Treasuries
The Depository Trust and Clearing Corporation is partnering with Digital Asset and the Canton Network to begin tokenizing a subset of US Treasury securities currently held at the Depository Trust Company. With regulatory clearance secured from the SEC, the pilot is expected to launch in early 2026, marking a significant step toward bringing traditional treasury markets onto blockchain rails and modernising capital markets infrastructure.
ECB digital euro moves forward
The European Central Bank stated that the digital euro project is technically ready and now awaits formal approval from EU lawmakers. The initiative aims to strengthen Europe’s monetary sovereignty and provide a resilient digital currency option, though legislative agreement on privacy and regulatory frameworks remains a key hurdle.
SoFi launches Ethereum stablecoin
SoFi Technologies announced the launch of its dollar-pegged stablecoin, SoFiUSD, on Ethereum. Fully backed by cash reserves and issued by SoFi Bank, the stablecoin is designed to support trading, payments, remittances, and white-label issuance, underscoring traditional finance’s accelerating adoption of tokenised money and on-chain infrastructure.
3. Key Macro Drivers – The Week Ahead
There are no major macro or monetary policy catalysts scheduled this week. With institutional participation expected to remain light due to the holiday period, liquidity conditions are likely to stay thin. As a result, price action should remain driven by positioning and liquidation dynamics rather than fundamental repricing.
4. Market Outlook
Sentiment and liquidity
Bitcoin Greed and Fear Index stands at 29%.
Ethereum Greed and Fear Index stands at 43%.
Sentiment has improved from extreme pessimism but remains consistent with a market stabilizing rather than trending.
Bitcoin
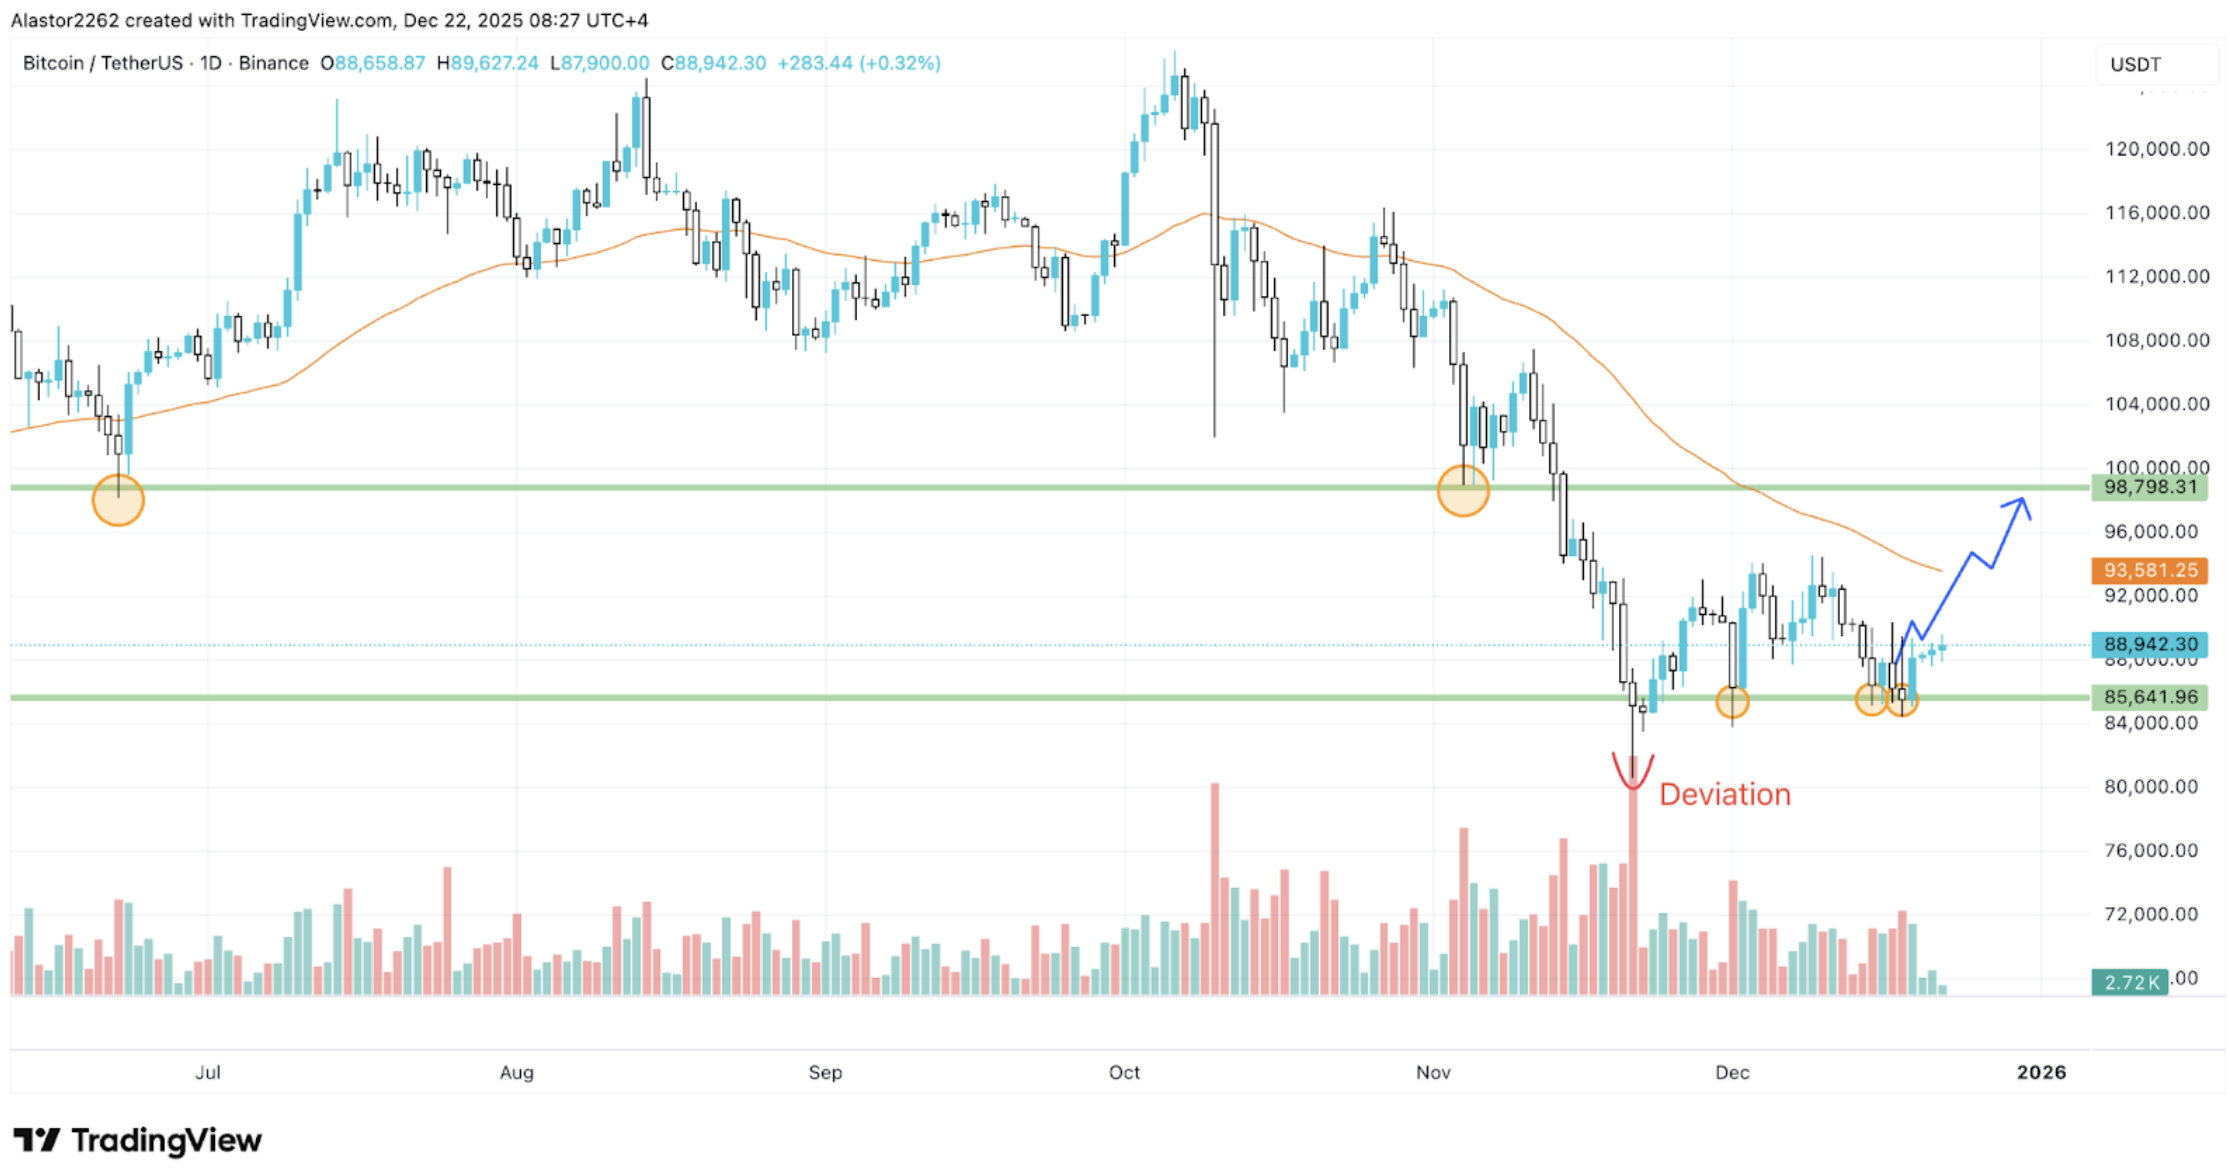
The broader Bitcoin downtrend remains intact, with price action continuing to trade within a fragile, low-liquidity environment. The liquidation heatmap offers limited directional clarity, with notable liquidity clusters sitting above price around the USD 95,000 area and below price around USD 84,000 and USD 79,000.
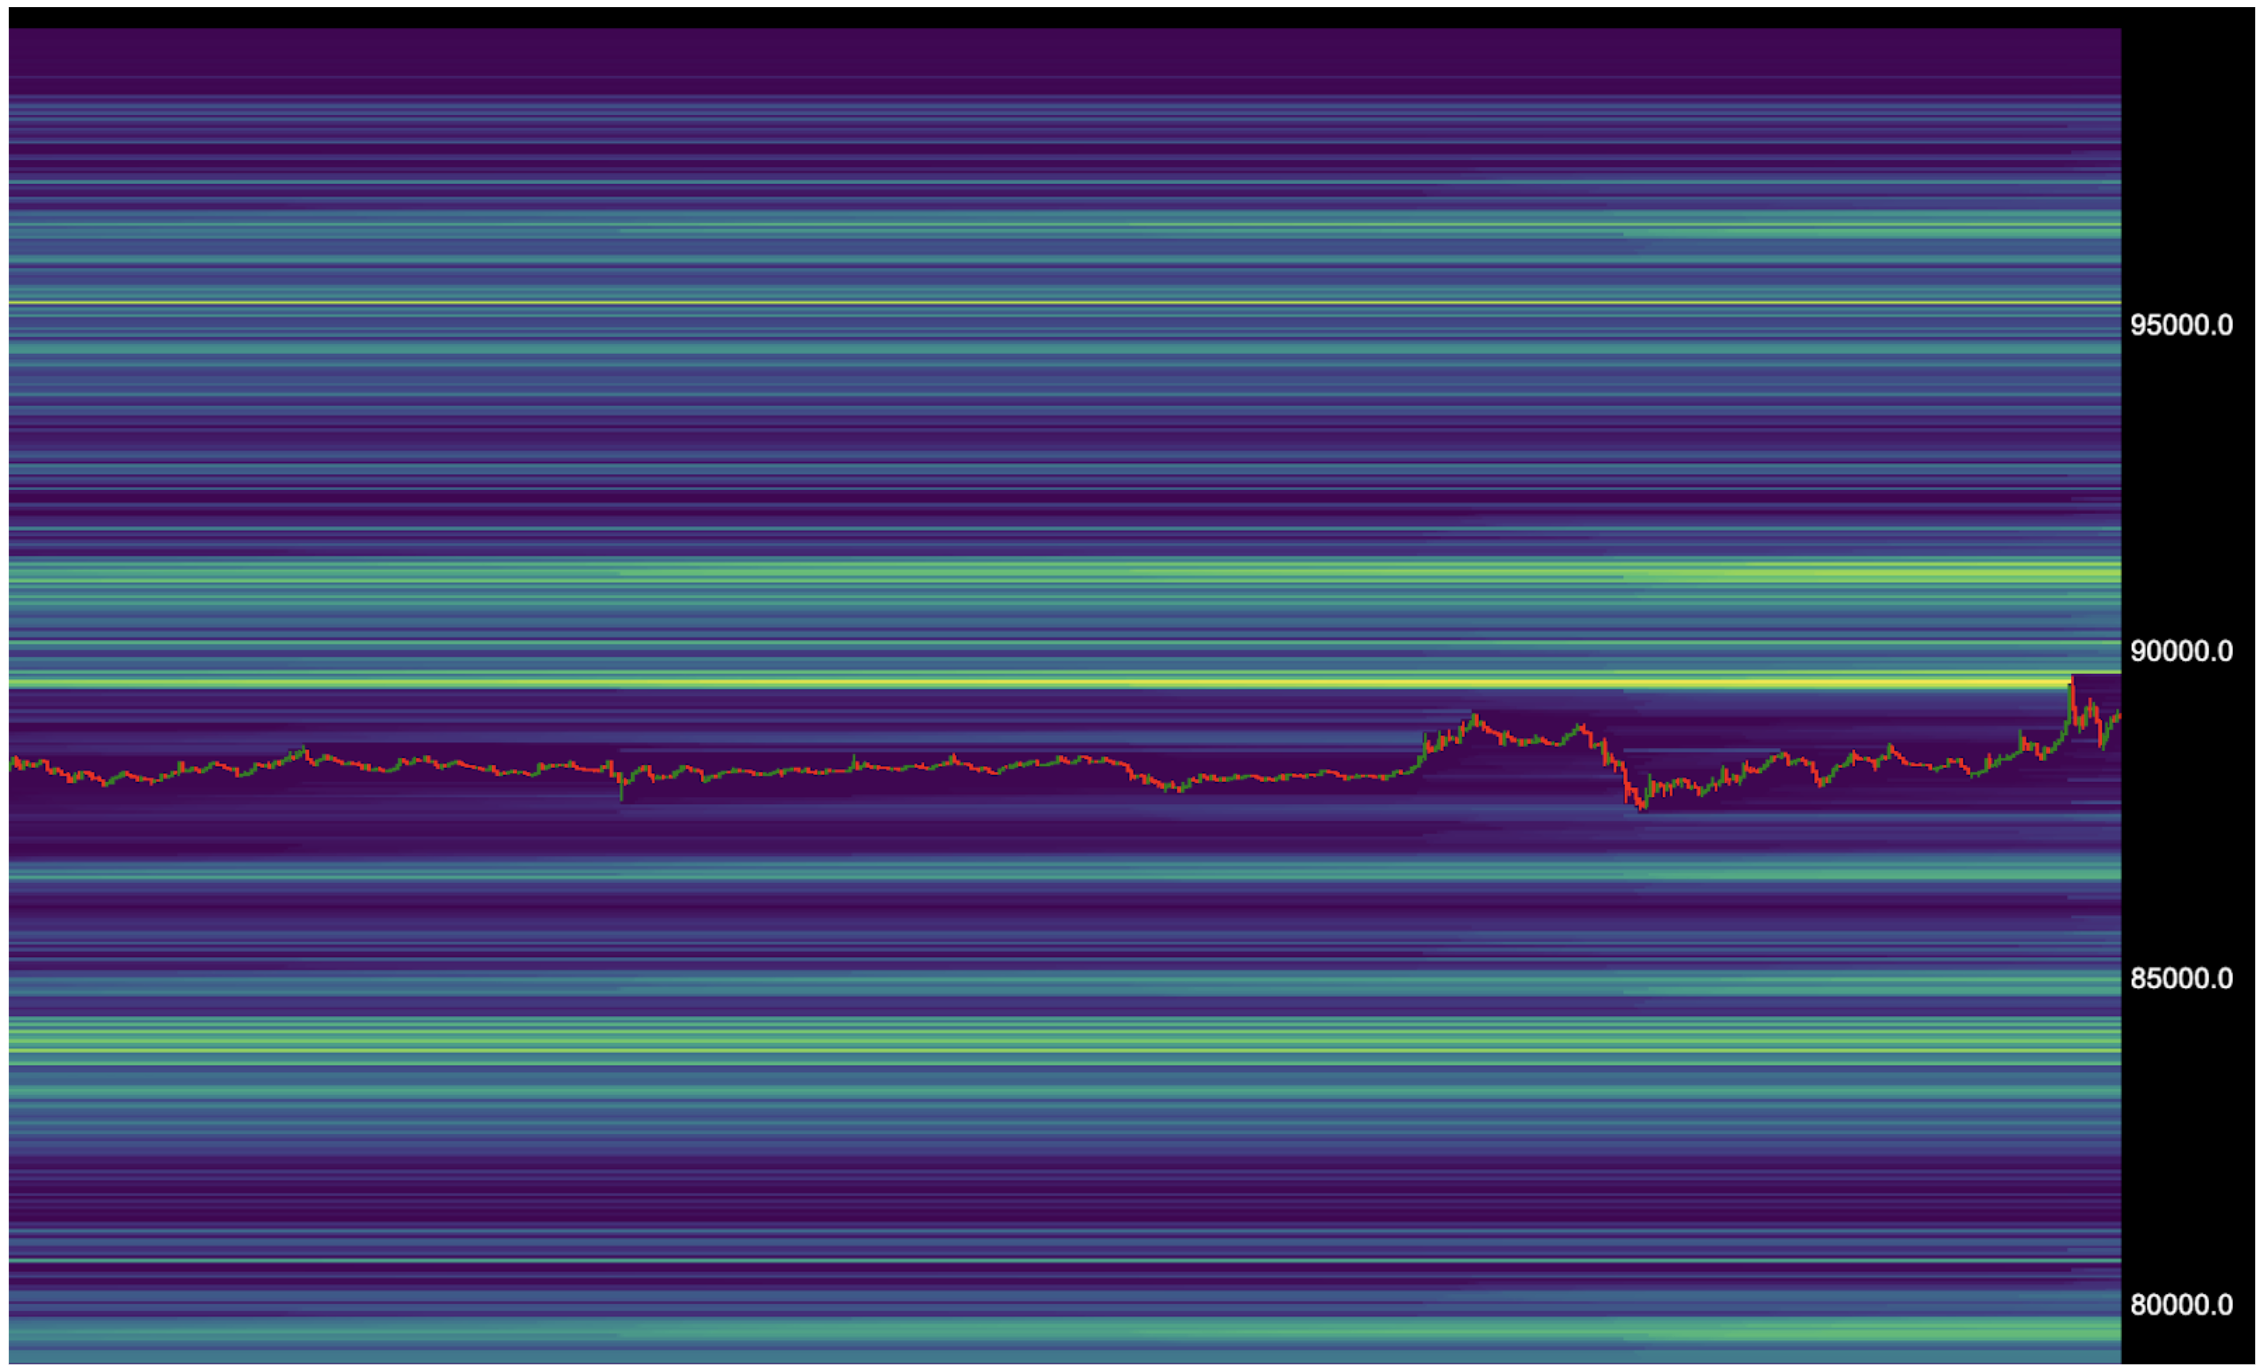
Price action last week saw repeated sharp rejections in the USD 89,500 to USD 90,000 zone, indicating aggressive selling into strength and highlighting persistent downside pressure beneath the surface. Despite this pressure, the market continues to make lower lows, which leads us to the most likely scenario for the coming week.
The preferred path is a clearance of the upside liquidation cluster, though traders should remain alert to the risk of a final downside attempt into the USD 84,000 liquidation zone to shake out weaker positioning before such a move. Confirmation of a meaningful reversal requires acceptance above USD 93,500. Until then, rallies should be treated as tactical rather than structural.
Ethereum
Ethereum continues to mirror Bitcoin’s fragile structure, with rebound attempts capped within its broader downtrend. Liquidity on the upside is concentrated around USD 3,100 and USD 3,250, while meaningful downside liquidity sits near USD 2,700.
Similar to Bitcoin, Ethereum faces the risk of a final downside sweep before any sustainable recovery can develop. The most constructive scenario involves clearing upside liquidity, though a dip toward lower liquidity levels cannot be excluded in thin conditions. Confirmation of a reversal for ETH requires acceptance above USD 3,200. Until that level is reclaimed, price action remains vulnerable to further volatility driven by positioning rather than conviction.
Altcoins
Altcoins remain structurally weak. Collapsing volumes, ongoing deleveraging, and disappointing token economics continue to weigh on the sector. With liquidity scarce and leadership absent, broad altcoin exposure remains unattractive outside of isolated, catalyst-driven opportunities.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.