


Weekly Crypto Outlook – March 16, 2026
Crypto markets enter the week with improving technical structure and stronger ETF inflows. Bitcoin continues to grind higher despite geopolitical tensions and weak equities, suggesting downside risks may have largely been absorbed. A clean break above $75,000 could accelerate momentum, while $69,500 remains the key pivot level.

TL;DR
Crypto markets enter the week with improving technical structure and a gradual shift in macro drivers. Bitcoin continues to grind higher despite persistent geopolitical tensions and weakening global equities, suggesting that downside tail risks may have largely been absorbed.
Positioning dynamics have changed meaningfully. Funding rates have turned slightly positive, ETF inflows are strengthening, stablecoin minting remains elevated, and liquidation activity has been unusually subdued. At the same time, volumes remain low and conviction is still fragile, indicating that the current move higher is being driven more by the absence of sellers than by aggressive new demand.
A notable macro transition is also underway. Bitcoin’s correlation to monetary policy expectations appears to be weakening, while geopolitical developments and energy markets are becoming increasingly influential. Somewhat counterintuitively, this shift may be constructive for Bitcoin, reinforcing its role as a non-sovereign asset during periods of global uncertainty.
Our base case for the week is continued upside grind with intermittent volatility. A clean breakout above the $75,000 area could accelerate momentum, while failure to hold above the $69,500 pivot would reopen downside risk toward the $62,000 liquidity zone.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Macro Drivers, The Week Ahead
Market Outlook
Macro View
Bitcoin’s macro narrative is evolving
For much of the past two years, crypto markets have traded largely in line with expectations around interest rates, particularly those relating to Federal Reserve policy. That relationship now appears to be weakening.
Recent market behaviour suggests that geopolitical developments, especially those influencing oil prices, are becoming a more dominant driver of global asset allocation decisions. While rising energy prices increase recession risks and complicate inflation dynamics, they also highlight vulnerabilities in traditional financial systems and sovereign monetary frameworks. This environment tends to reinforce Bitcoin’s structural investment case.
Last week’s US labour market surprise illustrated this shift. Despite a sharp negative payrolls print, rate expectations only adjusted briefly before stabilising. Investor attention has increasingly shifted toward the trajectory of oil prices and the broader implications of geopolitical tensions.
From a macro perspective, the speed of oil price increases matters more than the absolute level. If crude prices stabilize near $80 per barrel, the economic impact is likely manageable. However, a sustained move toward $120–125 could materially increase recession risks and delay monetary easing.
Inflation dynamics may also become more complex in the coming months. US gasoline prices have already risen significantly since tensions escalated, meaning upcoming inflation data may show renewed price pressures.
Despite this challenging backdrop, Bitcoin has shown resilience. Since geopolitical tensions intensified, Bitcoin has outperformed both equities and gold. Institutional flows into digital asset investment products have remained positive, reinforcing the view that investors are willing to maintain exposure to Bitcoin during periods of macro uncertainty.
Taken together, these developments suggest that while macro conditions remain fragile, the evolving driver set may increasingly favour Bitcoin over traditional risk assets.
Market Movers and Events, Last Week
Market data and flows
Crypto market cap: $2.45T, up 7% week on week
Average weekly volume: $97B, down 11%
Bitcoin weekly volume: $43.7B, down 11%
Ethereum weekly volume: $20.4B, down 11%
Ethereum network fees: 0.04 Gwei
Markets moved higher despite declining volumes, indicating that price appreciation was driven primarily by reduced selling pressure rather than strong spot demand.
Futures and positioning
Bitcoin funding rate: +0.2%
Bitcoin open interest: $21.7B, up $1B
Ethereum funding rate: -0.4%
Ethereum open interest: $11.9B, up $1B
Funding rates improved as traders cautiously added upside leverage. Positioning suggests that market participants are attempting to buy a potential cyclical bottom rather than aggressively chasing momentum.
Liquidation activity remained notably low, reinforcing the view that downside leverage has already been flushed out.
ETF flows
Bitcoin ETF flows (7 days): +$763M
Ethereum ETF flows (7 days): +$162M
Flows into digital asset investment products have strengthened in March, marking a reversal after several months of persistent outflows. This shift reduces the probability of extreme downside scenarios in the near term.
Stablecoins and liquidity
USDT market cap: $184B, up 0.05% week on week
USDC market cap: $79.1B, up 2.5% week on week
Stablecoin balances increased by roughly $2.4B last week, reinforcing the view that fresh liquidity is gradually entering the crypto ecosystem.
The expansion remains uneven. USDC continues to grow faster than USDT, suggesting that institutional oriented capital flows remain the primary driver of recent stablecoin inflows.
Dominance
Bitcoin dominance: 58.8%
Ethereum dominance: 10.5%
Bitcoin continues to attract defensive allocation. We still favor Bitcoin over broader altcoin exposure, although selective altcoin opportunities are beginning to emerge.
Key Macro Drivers, The Week Ahead
Mar 18: Producer Price Index ex Food & Energy Previous: 3.6% YoY Consensus: 3.6% YoY The release will help assess whether underlying producer inflation remains sticky.
Mar 18: Federal Reserve Interest Rate Decision Mar 21: Powell speech
Geopolitical developments and oil price movements remain the primary macro drivers.
Token unlocks
More than $269M in tokens are scheduled to be released this week. Below are the most notable unlock events.
Mar 16: Arbitrum (ARB) – ~$9.65M unlock (1.78% of circulating supply)
Mar 17–18: Lombard (BARD) – ~$32.43M unlock (11.09% of circulating supply)
Mar 17: ZKsync (ZK) – ~$3.4M unlock (2.97% of circulating supply)
Mar 20: LayerZero (ZRO) – ~$55.53M unlock (5.64% of circulating supply)
Mar 22: River (RIVER) – ~$26.7M unlock (5.67% of circulating supply)
Market Outlook
Sentiment
Bitcoin Greed and Fear Index: 65% (vs. 30% last week)
Ethereum Greed and Fear Index: 70% (vs. 35% last week)
Sentiment has improved significantly and now reflects constructive short term positioning. However, markets remain far from euphoric levels typically associated with major tops.
Bitcoin
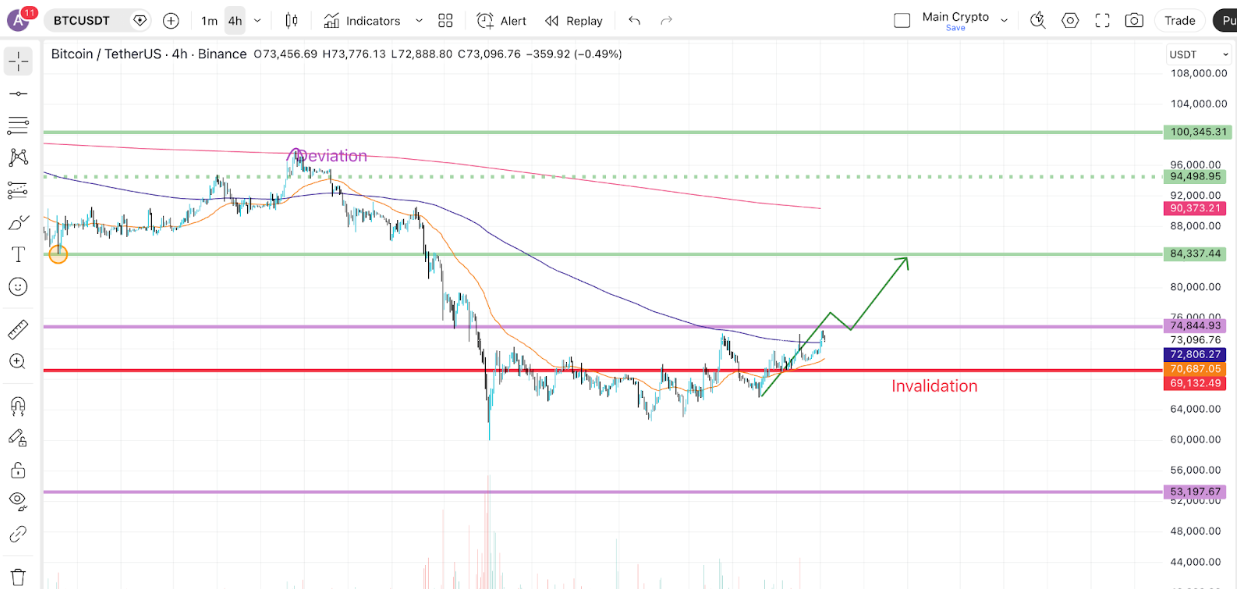
Bitcoin continues to grind higher with improving technical indicators and strengthening institutional flows.
Key levels
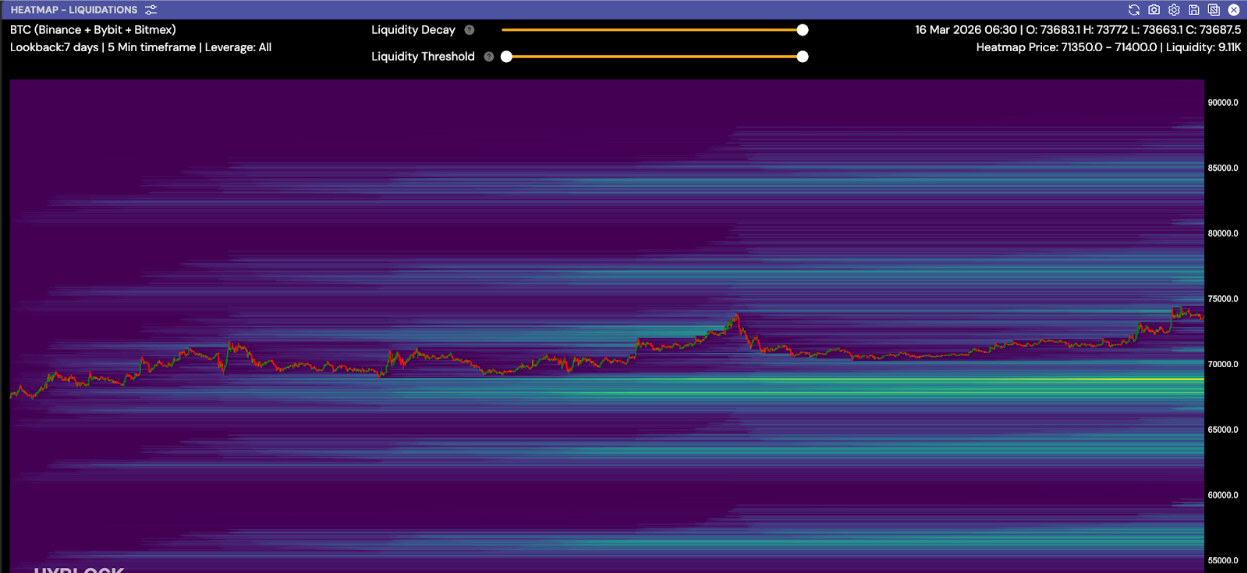
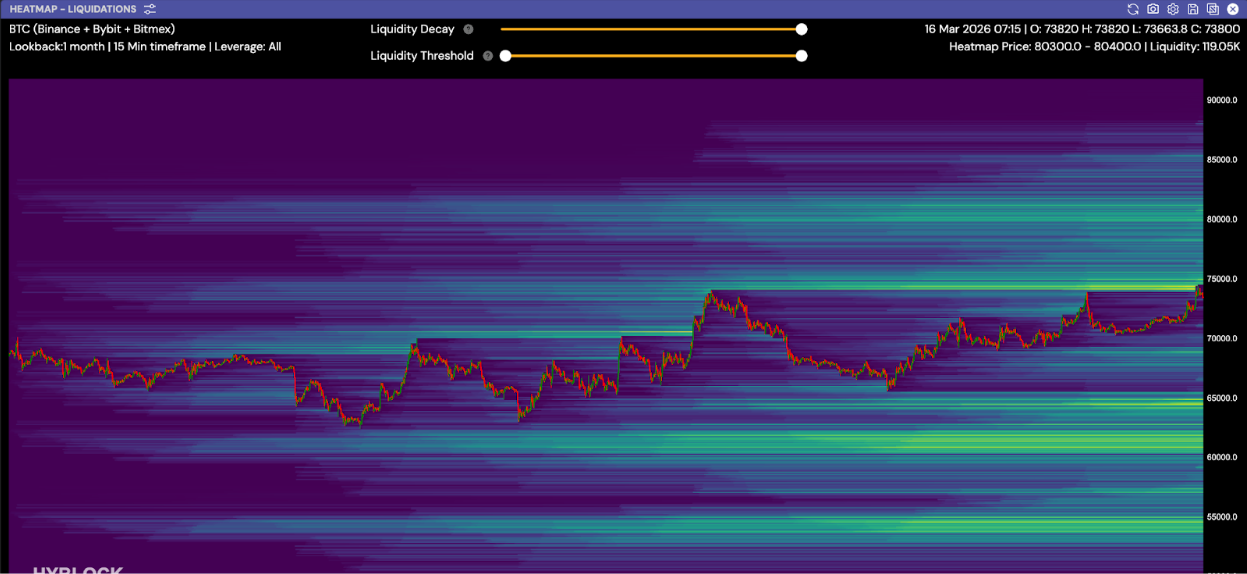
Current price: approximately $73,100
Short term pivot: $69,000
Resistance zone: $75,000
Major resistance: $79,000
Downside liquidity pool: $68,800 and $64,500
Technical structure suggests that monday morning move cleared the liquidation pool at 74300, momentum could extend toward the $75,000 and $79,000 area. Failure to hold above the $69,000 pivot would likely trigger renewed downside testing.
Ethereum
Ethereum technicals are also improving but remain weaker relative to Bitcoin.
Key levels
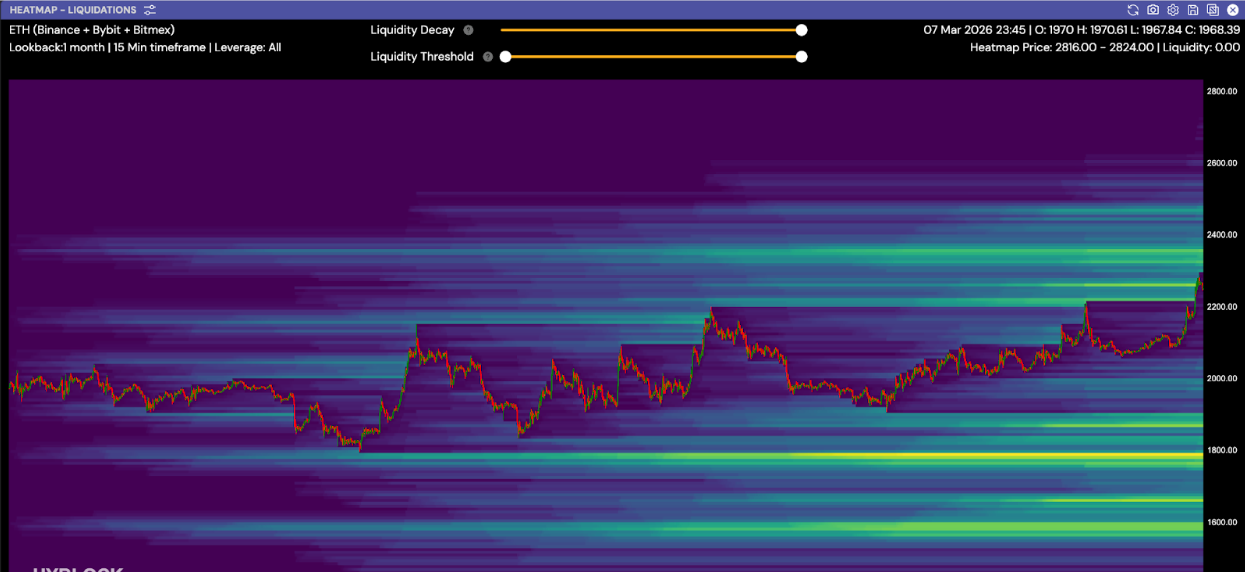
Current price: approximately $2,250
Pivot: $2,025
Resistance: $2,600
Downside liquidity pool: $1,875 and $1,780
ETH remains highly dependent on Bitcoin’s direction and broader liquidity conditions.
Altcoins
The altcoin model remains selective. Bitcoin continues to dominate flows, although improving sentiment and stablecoin expansion may allow isolated altcoin rallies.
One notable exception remains Hyperliquid, which continues to gain traction within the derivatives ecosystem. The protocol’s monthly trading volume now exceeds $200B, and the HYPE token has decoupled from the broader crypto downturn, rising roughly 24% year to date while Bitcoin has declined over the same period.
This divergence highlights an increasingly important theme across altcoins. Tokens tied to platforms generating real activity and liquidity are beginning to outperform, while projects with weaker token utility continue to lag.
Structural developments in tokenisation infrastructure continue to support the long term thesis for on-chain capital markets, but capital allocation remains highly selective.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.