


TL;DR
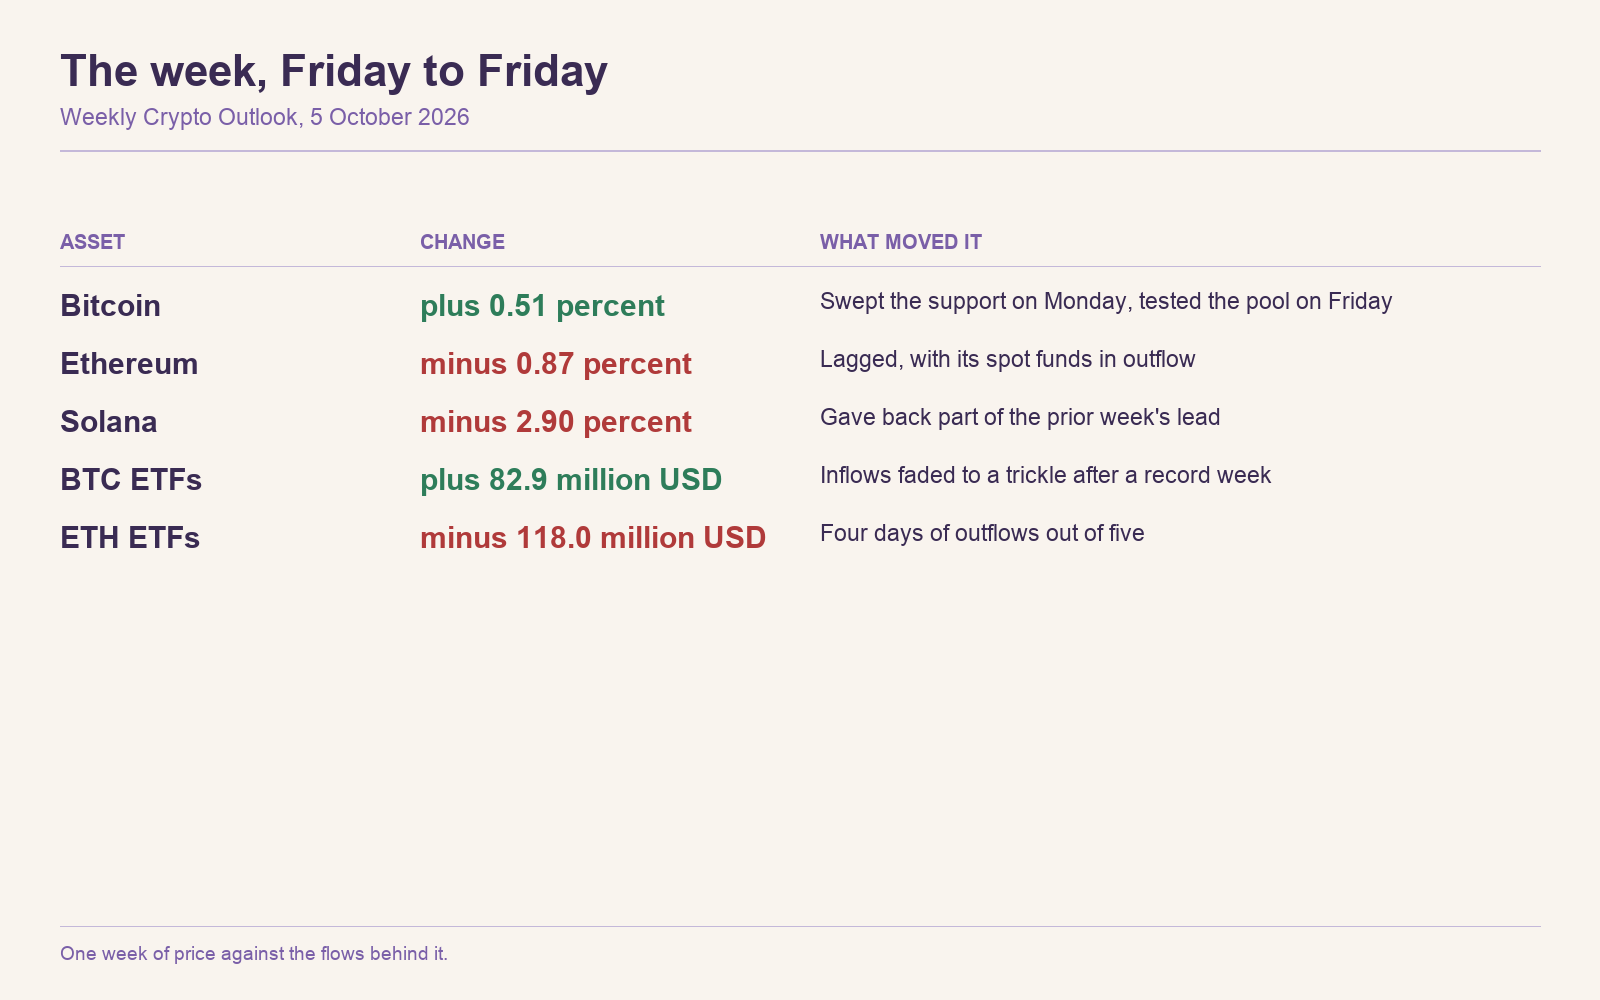
Bitcoin closed the week 0.51% higher at $84.5K. On Monday it swept beneath the May high of $82.8K to $82.5K and closed back above it the same day; on Friday it ran to $87.2K into the short positions overhead and was sold back to $84.5K, leaving a $2,420 upper wick. Sunday took it to $86.8K and this morning it trades at $85.9K, inside the lower edge of the pool of short liquidation stock from $85.75K to $90.25K. Leverage came back: open interest is up 10.2% from the week's low and funding has climbed from 0.0015 to 0.0083 against a 0.0100 neutral rate.
The rates picture moved in the market's favour. The implied odds of an October hike fell from about 75% to about 37% after the New York Fed president said September's hike had reduced the urgency for more and softer job openings, confidence and core PCE followed. Wednesday's FOMC minutes of the meeting that hiked are the test: patient minutes keep the backdrop as priced, hawkish ones firm October back up. Iran-US talks have stalled, yet Brent is down to $101 from above $106 on supply.
Institutional flows stepped back. US spot Bitcoin ETFs took in US $82.9M Monday to Friday after US $2.4B the week before, with a US $148.7M outflow on 30 September ending a nine-day run of inflows, and Ethereum ETFs took out US $118.0M. Stablecoin supply grew by US $3.0B.
Our preferred Bitcoin scenario is the fill of Friday's wick to $87.2K and a continuation into the centre of the pool at $88K. The trigger is one 4 hour candle closing above $86.8K, Sunday's high. It is invalidated on acceptance below $82.5K, Monday's sweep low, three consecutive 4 hour candles closing beneath it. The alternate stays live until the pool is cleared above $90.25K: a third push above $87.4K that is sold, confirmed by a daily close back below $85.75K, and a move back toward the long stock beneath $83.75K.
Full outlook below.
Disclaimer :
Posted in personal capacity. Views are my own, not those of Rain MENA FZE (VARA-regulated, Dubai), where I am a Director, or Rain Trading Limited (FSRA-regulated, ADGM), where I am Senior Executive Officer and General Manager. This is general market commentary, not investment advice, not a solicitation, and not a recommendation to buy, sell or hold any asset. Crypto assets are volatile and you can lose the full value of your investment. Do your own research. No Rain client, product or service is being offered or promoted in this post.
In This Week's Note
Macro View
Market Movers
Key Headlines
Key Macro Events
Notable Token Unlocks
Market Outlook
What happened last week
Bitcoin spent the week between a floor it defended and a ceiling it tested. On Monday 28 September it dipped beneath the May high of $82.8K to $82.5K and closed the day back above it at $83.5K; every daily close since 22 September, 13 of 13, is above that level. On Friday 2 October it ran to $87.2K, into the short positions stacked above, and was sold back to $84.5K the same day, leaving a $2,420 upper wick. Friday to Friday the week is up 0.51%. On Sunday it rose to $86.8K and closed at $86.5K, filling half of that wick, and this morning it trades at $85.9K.
Last week's call was a sweep of the leveraged longs beneath $82.75K and then a move up through the shorts overhead, with $85.5K as the first stop. The sweep ran to $82.5K, the reclaim printed the same day, and price reached $87.2K on Friday, through the first stop. The second stop at $88.25K was not reached; the push was sold the same day, and that wick is this week's setup.
The macro backdrop moved in the market's favour. The odds of an October rate rise fell from about 75% to about 37% after the New York Fed president said September's hike had reduced the urgency for more and softer job openings, confidence and inflation data followed. Long yields went the other way: the ten-year touched about 5.3%, its highest since 2002.
Who bought, and who sold
The spot ETFs, the listed funds that give traditional investors access to crypto, stepped back. Bitcoin funds took in US $82.9M Monday to Friday after US $2.4B the week before, with an outflow of US $148.7M on 30 September ending a nine-day run of inflows; Ethereum funds took out US $118.0M. Stablecoins, the digital dollars that fund crypto buying, grew by US $3.0B on the week, the strongest reading in the set.
The futures market came back in. Open interest on the largest dollar-margined book, the value of open leveraged bets, fell to US $7.7B during Monday's sweep and has rebuilt to US $8.5B this morning, up 10.2% from that low and 6.2% from the prior Friday. Funding, the recurring fee that traders betting on a rise pay to those betting on a fall, climbed from 0.0015 per interval a week ago to 0.0083 today, against a normal rate of 0.0100. Sunday's push into the pool was bought on the perpetuals, with US $195M of net aggressive buying on the largest book, and barely at all on spot, where the same measure read minus US $3.7M.
Why that matters
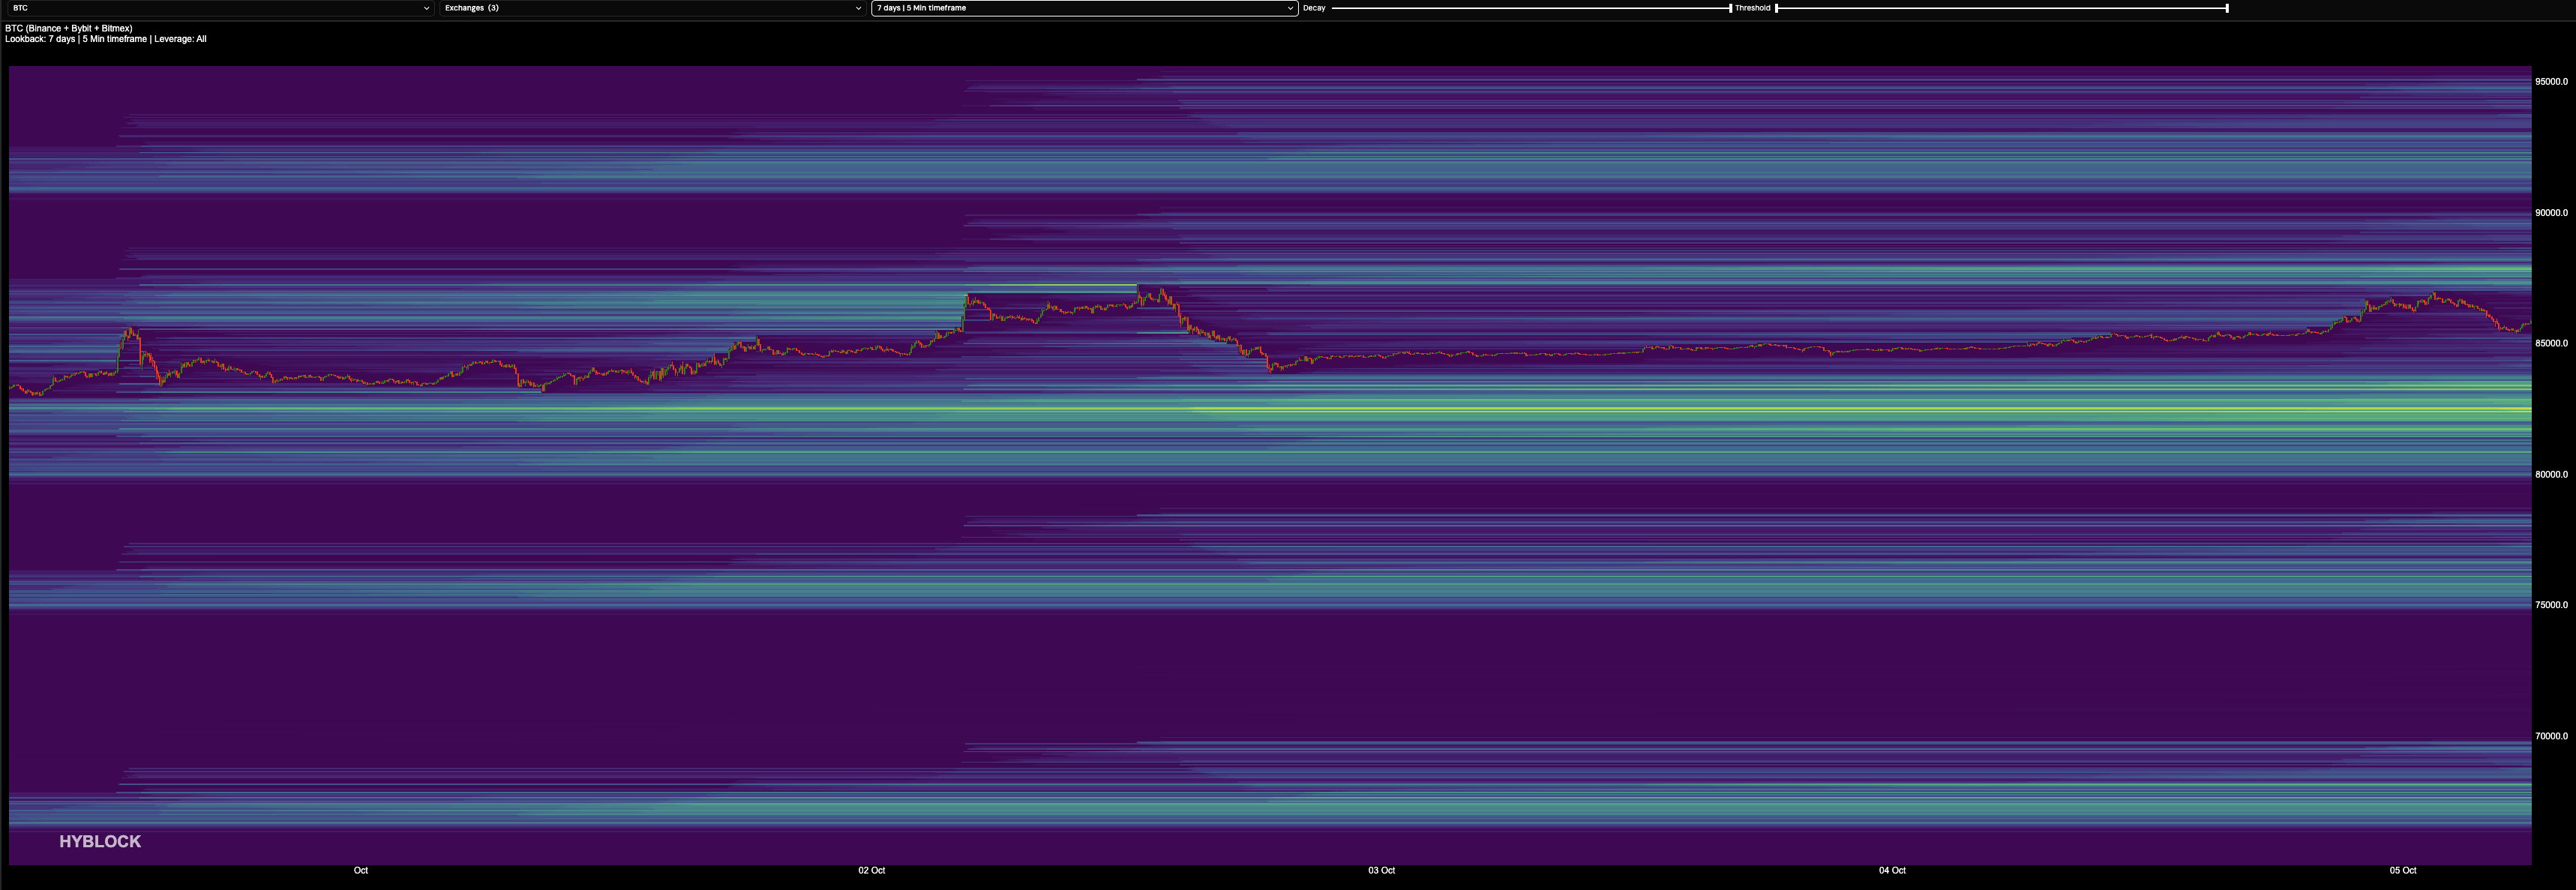
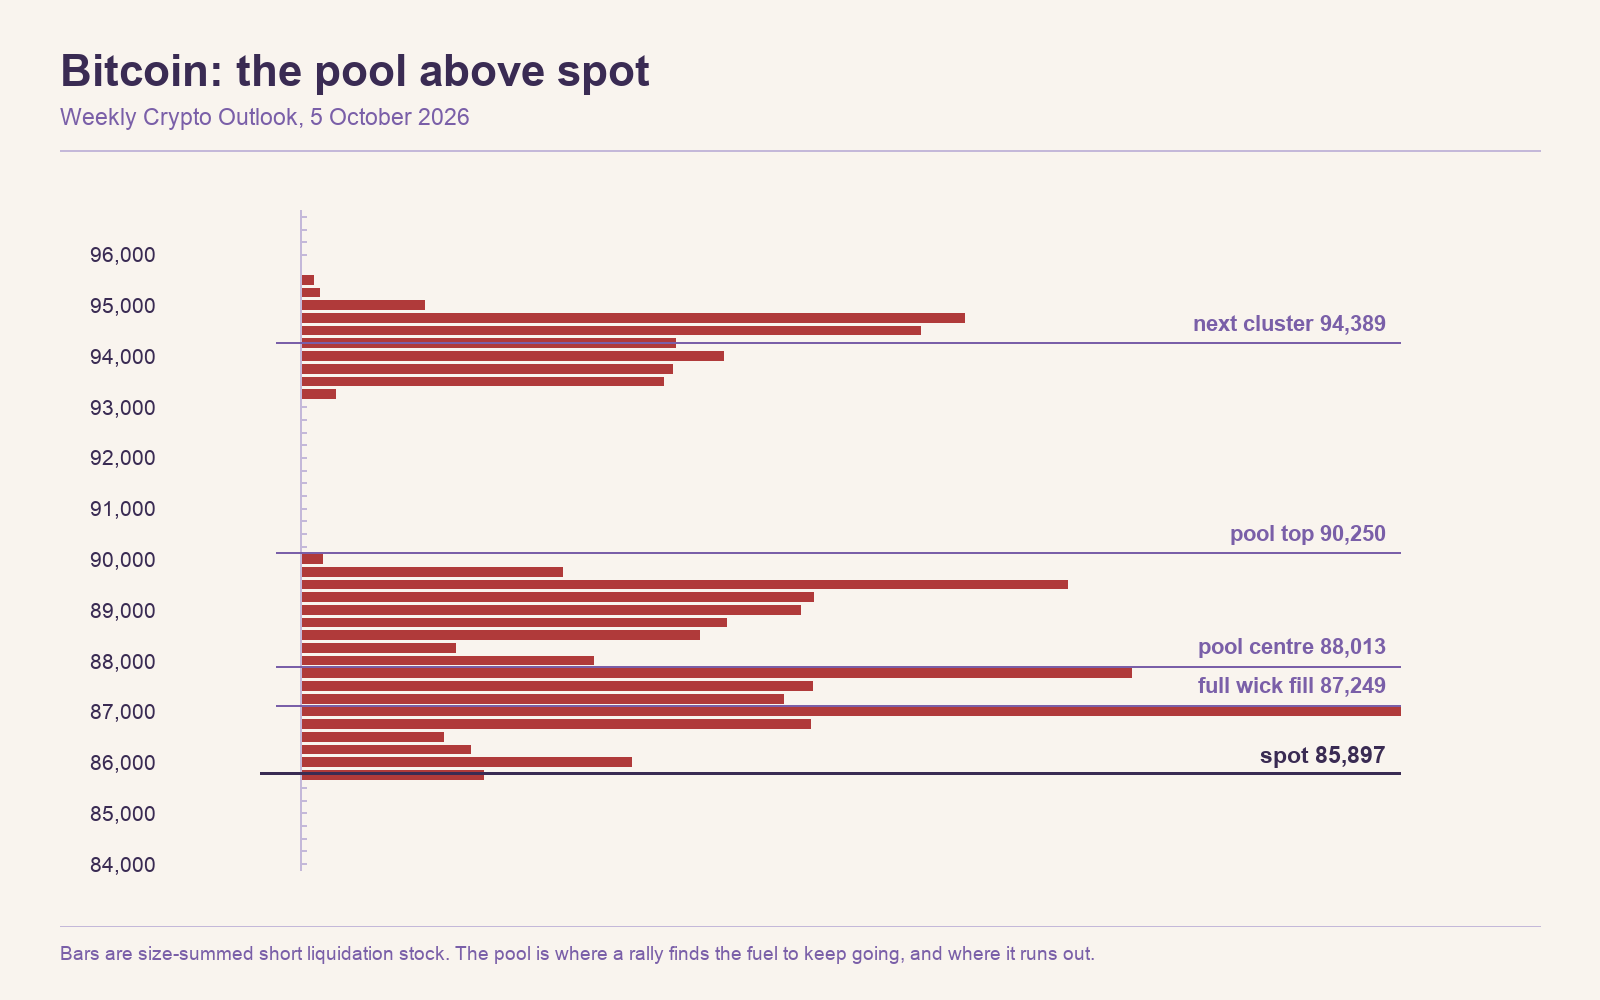
A rally that leverage carries into a pool of short positions usually reaches the pool, because those positions are the fuel: each one forced to close is a buy order. The pool above runs from $85.75K to $90.25K and holds 55.8% of all the standing short liquidation stock on the map, size-summed, centred at $88K, with its densest band from $87K to $87.25K, exactly where Friday's high and the 21 September high of $87.4K sit.
Whether price stays above the pool afterwards depends on whether spot buyers follow the leverage in. This week they did not: the ETF bid faded to a trickle and spot flow was net selling. That is why the third push above the two highs has a scenario of its own.
My read for the week
Bitcoin fills Friday's wick to $87.2K and continues into the pool's centre at $88K, where half of its short stock has been consumed. A clean break of the pool travels: the map is empty from $90.25K to $93.25K.
The signal is one 4 hour candle closing above $86.8K, Sunday's high. Spot has sat inside the pool's lower edge since Sunday evening without that close.
I am wrong on acceptance below $82.5K: three consecutive 4 hour candles closing beneath Monday's sweep low. The support at $82.8K has absorbed one deviation already; a second that holds beneath the first one's low is a failure of the support, and the long positions beneath, centred near $82K, come into play.
The alternate, live until the pool is cleared: a run above $87.4K through both prior highs, followed by a daily close back below $85.75K, the floor of the pool. That is an upside stop hunt completed and rejected, and the path from there runs back to the long positions from $80K to $83.75K. It is retired by acceptance above $90.25K.
Ethereum and Solana sit at the lower edge of their own short stock and follow Bitcoin's trigger. Ethereum lost 0.87% on the week and Solana 2.90%.
The detail behind the call
The figures, charts and levels behind this read, section by section.
Macro View
A light calendar, and the Fed's own words
The week carries few prints and one document. The ISM services index lands on Monday (consensus 55.1 against 55.4). On Wednesday the Fed publishes the minutes of the 16 September meeting, the one that raised rates by 25 basis points. Thursday is jobless claims (200K against 197K) and Friday the preliminary Michigan sentiment survey (47.6 against 47.8) with its one-year inflation expectations (prior 4.6%). September CPI comes the following week.
The backdrop changed more in the last ten days than in the month before. The implied odds of an October hike fell from about 75% to about 50% when the New York Fed president said the September hike had reduced the urgency for further tightening, and to about 37% on the data that followed: August job openings at 7.079M, the lowest in five months; September consumer confidence at 81.9 from 88.6, the weakest since 2014; core PCE at 0.2% on the month and 3.0% on the year. Against that, second-quarter growth was revised up to 2.2%, August consumer spending rose 0.9% and jobless claims are at their lowest since July. The ten-year yield briefly reached about 5.3%, its highest since 2002, while the front end fell: the market is pricing the Fed's path and the government's borrowing separately.
Wednesday's minutes are the test. If the committee that hiked reads as patient, the backdrop stays where the price already is. If the minutes read as another hike pencilled in, October firms back up and the pool above loses its buyers. Bitcoin's move from the sweep low to the pool happened across the fall in hike odds, so the tone of the minutes matters more this week than any single print.
Iran, and the oil route into inflation
The diplomatic opening of late September has stalled. Iran's seven-day plan of 25 September to reopen the Strait of Hormuz was rejected by the US president on 26 September. On 3 October a source in Tehran said Iran is preparing for a "major round of fighting" and that the assessment in Iran is that the war is resuming, while the door to diplomacy remains open. Seven rounds of talks in New York ended without a breakthrough, and a US counterproposal is on the table that Iran appears unlikely to accept; Iran has offered to transfer its 60% enriched uranium to a third party as part of a phased roadmap. A third US carrier group, the Theodore Roosevelt, is on its way to the region, and US officials met at Camp David on Iran strategy and on the Houthi offensive along Yemen's western coast.
On 4 October Iran's parliament speaker and chief negotiator said the Strait will stay closed until Iran's seven conditions are met and that "the era of wasting time and dictating unilateral demands is over". The foreign minister said Iran is as serious about a diplomatic solution as about defending itself. The dispute is sequencing: Tehran wants US steps first, Washington wants the strait open first.
Oil has gone the other way from the headlines. Brent was above $106 a barrel a week ago and trades at $101 this morning, down 0.86% on the day and up 4.33% on the month. Supply explains it: the G7 agreed to release 100 million barrels from reserves, OPEC+ left quotas unchanged, Gulf crude exports beat pre-war levels on four of seven days in late September, and Saudi-backed forces moved against the Houthi positions on the Bab el-Mandeb strait, where shipping is so far unaffected.
The route into crypto runs through oil, then inflation, then the rate path, and this week it ran in the market's favour: oil down about $5 while hike odds fell to 37%. A resumption of fighting reverses that, putting oil back above $106 into Wednesday's minutes and Friday's inflation-expectations print and firming the October hike again.
Market Movers
Market Performance
Bitcoin was the only major to gain, up 0.51% to $84.5K Friday to Friday, with a Sunday close of $86.5K on top of it. Ethereum lost 0.87% to $2,667.28 and Solana 2.90% to $118.56, giving back part of two weeks of leadership. Hyperliquid was about flat at about 91.5. Total market capitalisation rose to US $2.9T. Bitcoin dominance rose to 59.26% and Ethereum's was broadly unchanged at 11.37%.
ETF Flows
US spot Bitcoin ETFs took in US $82.9M Monday to Friday: US $31.0M on 28 September, US $66.2M on 29 September, minus US $148.7M on 30 September, US $102.7M on 1 October and US $31.7M on 2 October. The outflow on 30 September ended a nine-day run of inflows, and the day of the week's high drew US $31.7M. September as a whole took in about US $2.65B, the second-largest month since October 2025. Thirty days: US $2.0B. Year to date: US $1.1B.
Ethereum ETFs took out US $118.0M, with outflows on four of the five days: US $17.1M in on 28 September, then minus US $2.8M, minus US $59.6M, minus US $55.4M and minus US $17.3M. Thirty days: US $628M.
Stablecoins
Total supply rose by US $3.0B from Friday close to Friday close, to US $311.5B, about 0.97%, the largest weekly rise since August, and reads US $312.2B this morning. USDT supply is US $184.1B, up US $272M on the week. USDC is US $74.1B. USDT traded US $29.7B over twenty-four hours against USDC's US $6.8B. Net issuance over thirty days is US $3.3B. The dollars came in; the spot ETFs have yet to deploy them.
Positioning
Open interest on the largest dollar-margined book fell to US $7.7B during Monday's sweep, closed the week at US $8.3B, up 3.6%, and stands at US $8.5B this morning, up 10.2% from the week's low and 6.2% from the prior Friday, against a price up 0.51% on the week. Standing short stock above spot sits in one pool from 85,750 to 90,250 holding 55.8% of the total, size-summed on the dollar-margined book, centred at 88,013 with its densest band from 87,000 to 87,250; the next pool runs 93,250 to 96,250 with 22.1%. The whole overhead cluster moved up about 2,500 dollars with the price over the week. Aggressive flow told the same story: on Sunday the perpetuals saw US $195M of net aggressive buying on the largest book while spot saw minus US $3.7M, and on Friday's run to the high spot saw minus US $272.8M of net aggressive selling.
Funding
Daily mean funding on the largest dollar-margined book ran 0.0015 per interval on 26 September, 0.0050 on 29 September, 0.0059 on 2 October and 0.0083 today, against a 0.0100 neutral rate, and was negative for 24 of the last 169 hours. Bybit's dollar-margined book settled at neutral today. Longs are paying again, and not yet paying up.
Volume
Weekly traded volume was in line with its trailing average on Bitcoin and 6.3% below on Ethereum.
Sentiment
Fear and greed reads 70 on Bitcoin, down 4 on the week, and 66 on Ethereum, up 14.
Key Headlines
Five payments companies launched a shared dollar stablecoin
Open USD went live on 30 September across Ethereum, Base, Solana and Tempo. The token is issued by Bridge, the Stripe company, and overseen by Open Standard, whose five founding owners, Coinbase, Mastercard, Shopify, Stripe and Visa, hold equal initial stakes and have committed more than US $1B; reserves sit at BlackRock, BNY and Lead Bank, and more than 200 companies have joined, up from 140 when the project was announced in June. The token itself is ordinary. The structure is not: businesses mint and redeem at par without fees or volume caps, Open Standard keeps a small management fee, the partners collect the rest of the reserve yield, and further equity goes to partners according to the supply and volume they bring. That is a bid for the distribution economics that today sit with Tether and Circle, whose two tokens make up the bulk of a US $312B market.
The SEC proposed a custody route for advisers and funds
On 1 October the SEC voted to propose rules under the Investment Advisers Act and the Investment Company Act for how registered advisers and regulated funds may hold crypto for clients. State-chartered trust companies would qualify as custodians, and an adviser could hold assets itself only where it has determined in writing that no qualified custodian will take them, holds the keys alone, and revisits that finding every quarter. Chair Paul Atkins said the rules had not kept pace with a multi-trillion-dollar asset class. It is a proposal with a 60-day comment period, and it widens the set of institutions that can hold the asset directly.
The ECB and Circle asked Brussels for the same change
The European Commission's consultation on its review of MiCA closed on 30 September, and two filings that rarely agree did. MiCA requires stablecoin issuers to hold at least 30% of reserves in commercial bank deposits, 60% for issuers the European Banking Authority deems significant. The European Central Bank asked for the deposit floor to be replaced by a requirement that set shares of reserves mature within one and five working days; Circle asked for the same floor to go, arguing it ties the token's safety to bank credit, and for the 35% single-government and 1.5% single-bank exposure caps to be lifted. The case both point to is March 2023, when USDC briefly lost its peg after Circle disclosed US $3.3B of reserves at Silicon Valley Bank. Hyperliquid's policy group filed in the same review, asking for perpetual futures to be regulated under MiFID II rather than MiCA.
Key Macro Events
Mon 5 Oct — ISM services PMI, consensus 55.1 against 55.4 prior — 14:00 UTC (18:00 Dubai)
Wed 7 Oct — FOMC minutes of the 16 September meeting — 18:00 UTC (22:00 Dubai)
Thu 8 Oct — Initial jobless claims, consensus 200K against 197K prior — 12:30 UTC (16:30 Dubai)
Fri 9 Oct — Preliminary UoM consumer sentiment, consensus 47.6 against 47.8 prior, and one-year inflation expectations, prior 4.6% — 14:00 UTC (18:00 Dubai)
Notable Token Unlocks
5 Oct — CC — about US $20M per period — 0.38% of circulating — a change in the emission rate rather than a lump sum
8 Oct — STABLE — US $24M — 3.30% of circulating
9 Oct — MOVE — US $1.7M — 3.66% of circulating
10 Oct — CARV — US $1.7M — 5.85% of circulating
11 Oct — APT — US $9M — 1.30% of circulating
11 Oct — SOL — about US $49M per period — 0.068% of circulating — an emission-rate change
CARV at 5.85% of circulating is the largest proportional release of the week.
Market Outlook
Bitcoin: into the pool, with the two taps behind it
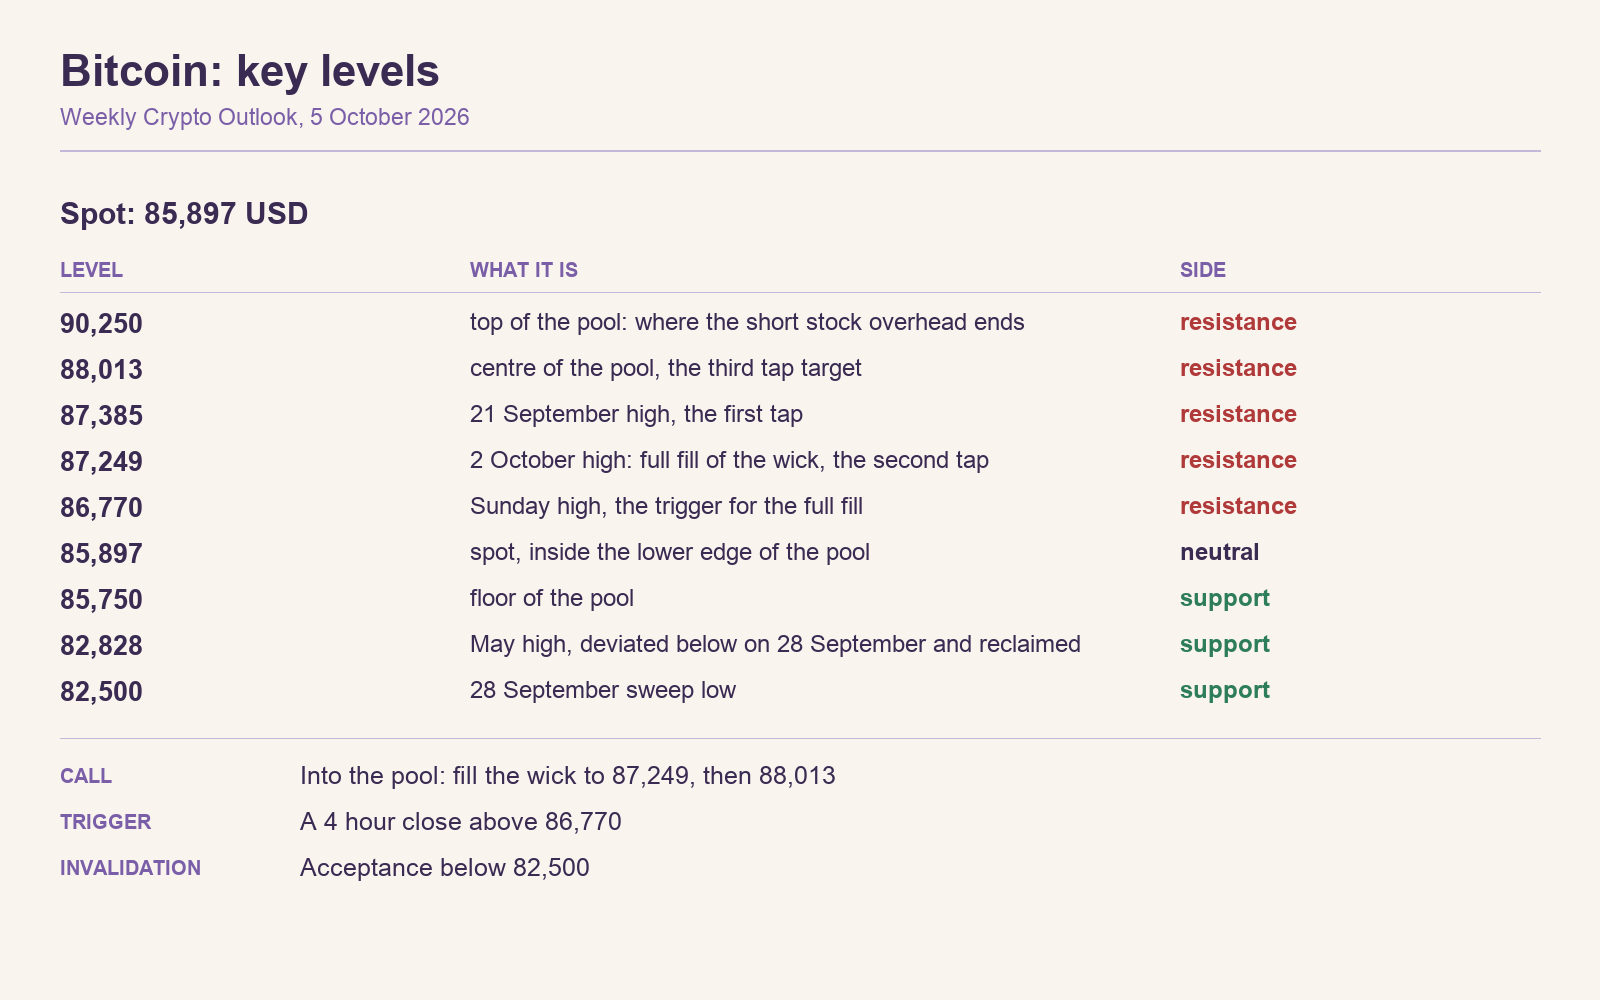
The call is that Bitcoin fills Friday's wick, from the candle's body at 84,829.60 to its high at 87,249, and continues into the centre of the pool of short stock overhead at 88,013. Half the wick was filled on Sunday, when price reached 86,770 and closed at 86,482.80; at the time of writing it trades at 85,897, 147 dollars inside the pool's lower edge at 85,750. The pool runs to 90,250, holds 55.8% of all standing short stock, size-summed on the dollar-margined book, and is densest from 87,000 to 87,250, where Friday's high and the 21 September high of 87,385 both sit. Half of it has been consumed by 88,000.
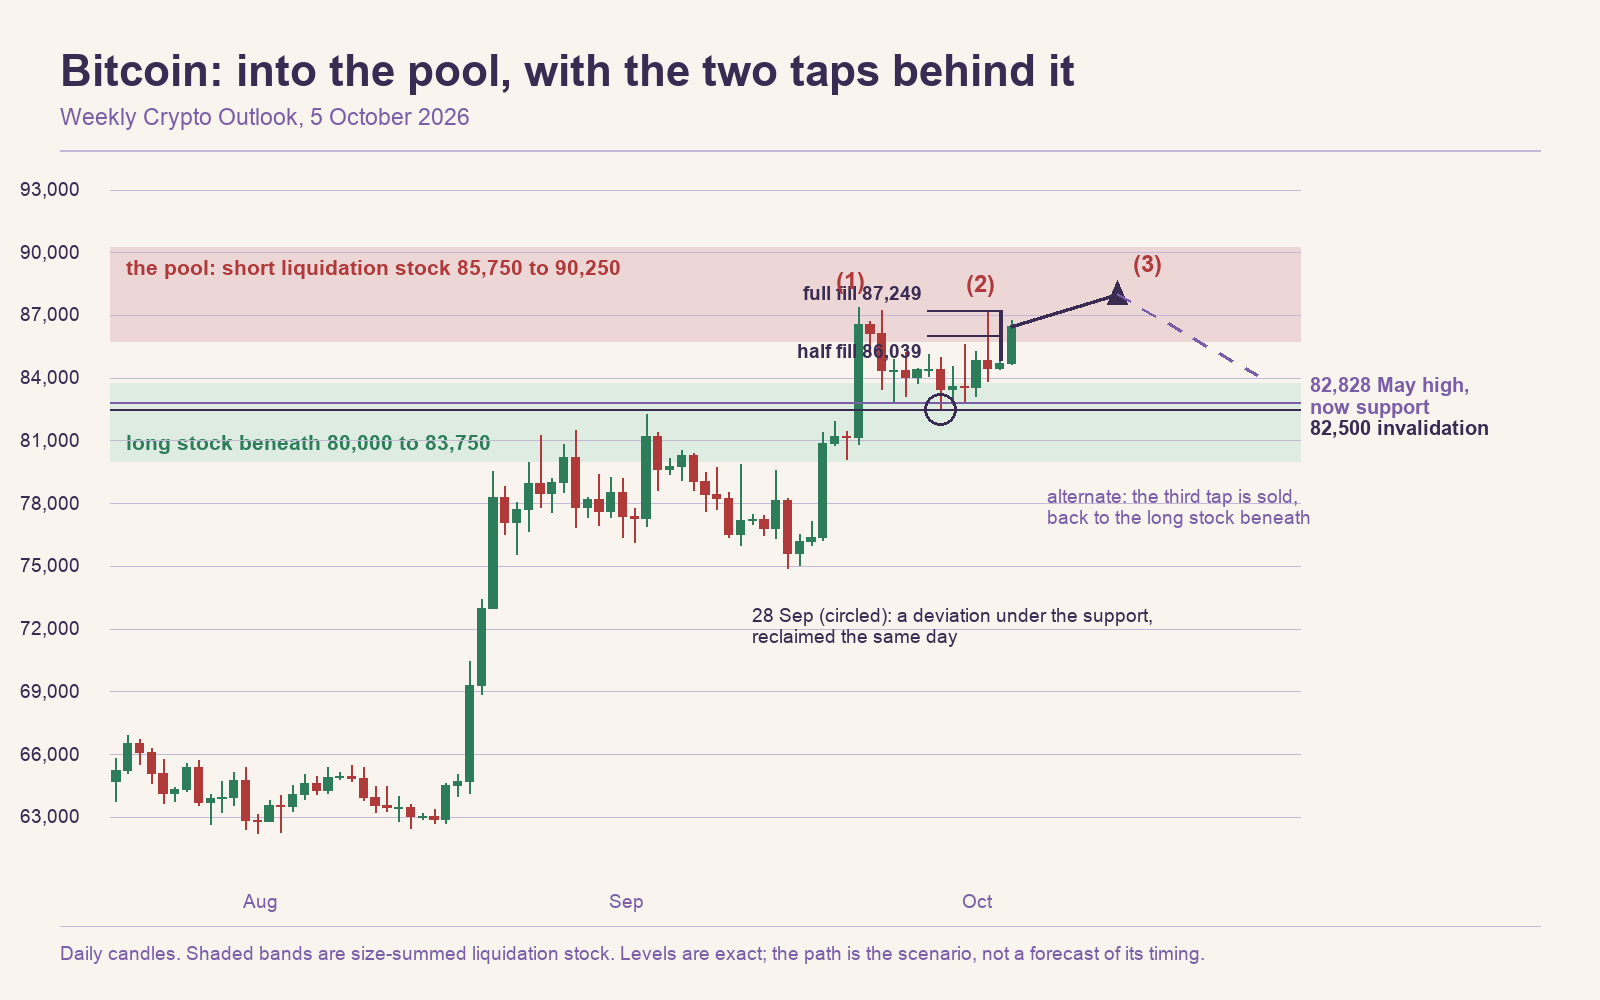
The trigger is one 4 hour candle closing above 86,770, Sunday's high. Acceptance, used below, means three consecutive 4 hour candles closing beyond a level; a wick through it is not acceptance. A clean break of the pool travels: the map is empty from 90,250 to 93,250, and the next cluster is centred at 94,389.
Trigger — one 4 hour candle closing above 86,770
Objectives — 87,249 first, then 88,013, then 90,250
Invalidation: acceptance below 82,500, three consecutive 4 hour candles closing beneath the 28 September sweep low. The May high at 82,828 has absorbed one deviation and been reclaimed, and every daily close since 22 September is above it; a second break that accepts beneath the first one's low is a failure of the support, and the long stock beneath, centred at 81,938 in a shelf from 80,000 to 83,750, is the next magnet.
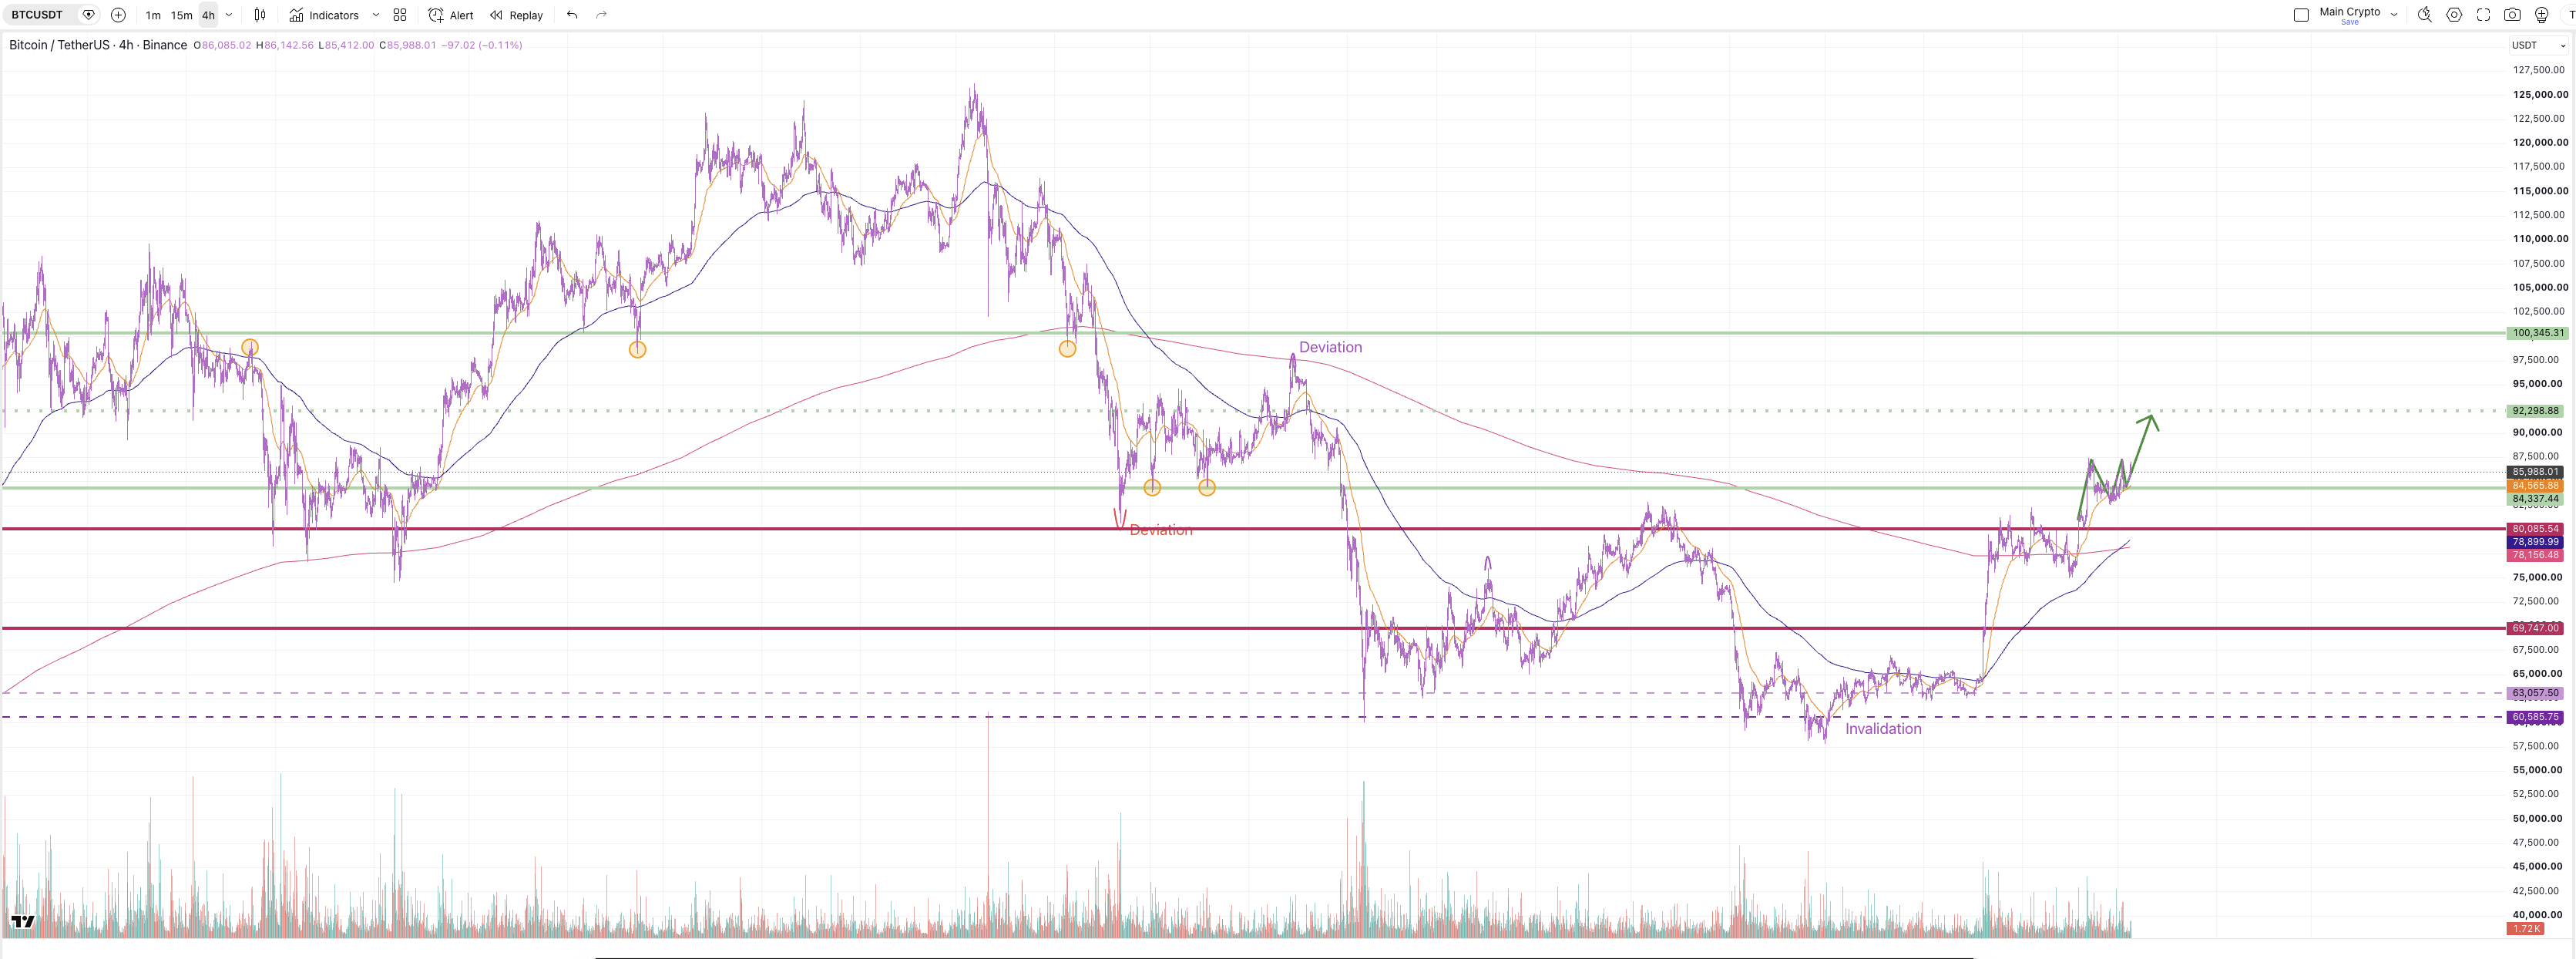
The same shape is on the 4 hour chart and the heatmaps: the reclaim of the May high, three sessions of consolidation above the 3 October low of 84,409.50, and the push into the pool, whose brightest bands sit at 87,000 to 88,000 and again at 89,000 to 89,750, with the long stock beneath concentrated at 82,000 to 83,000 and 80,250 to 81,000.
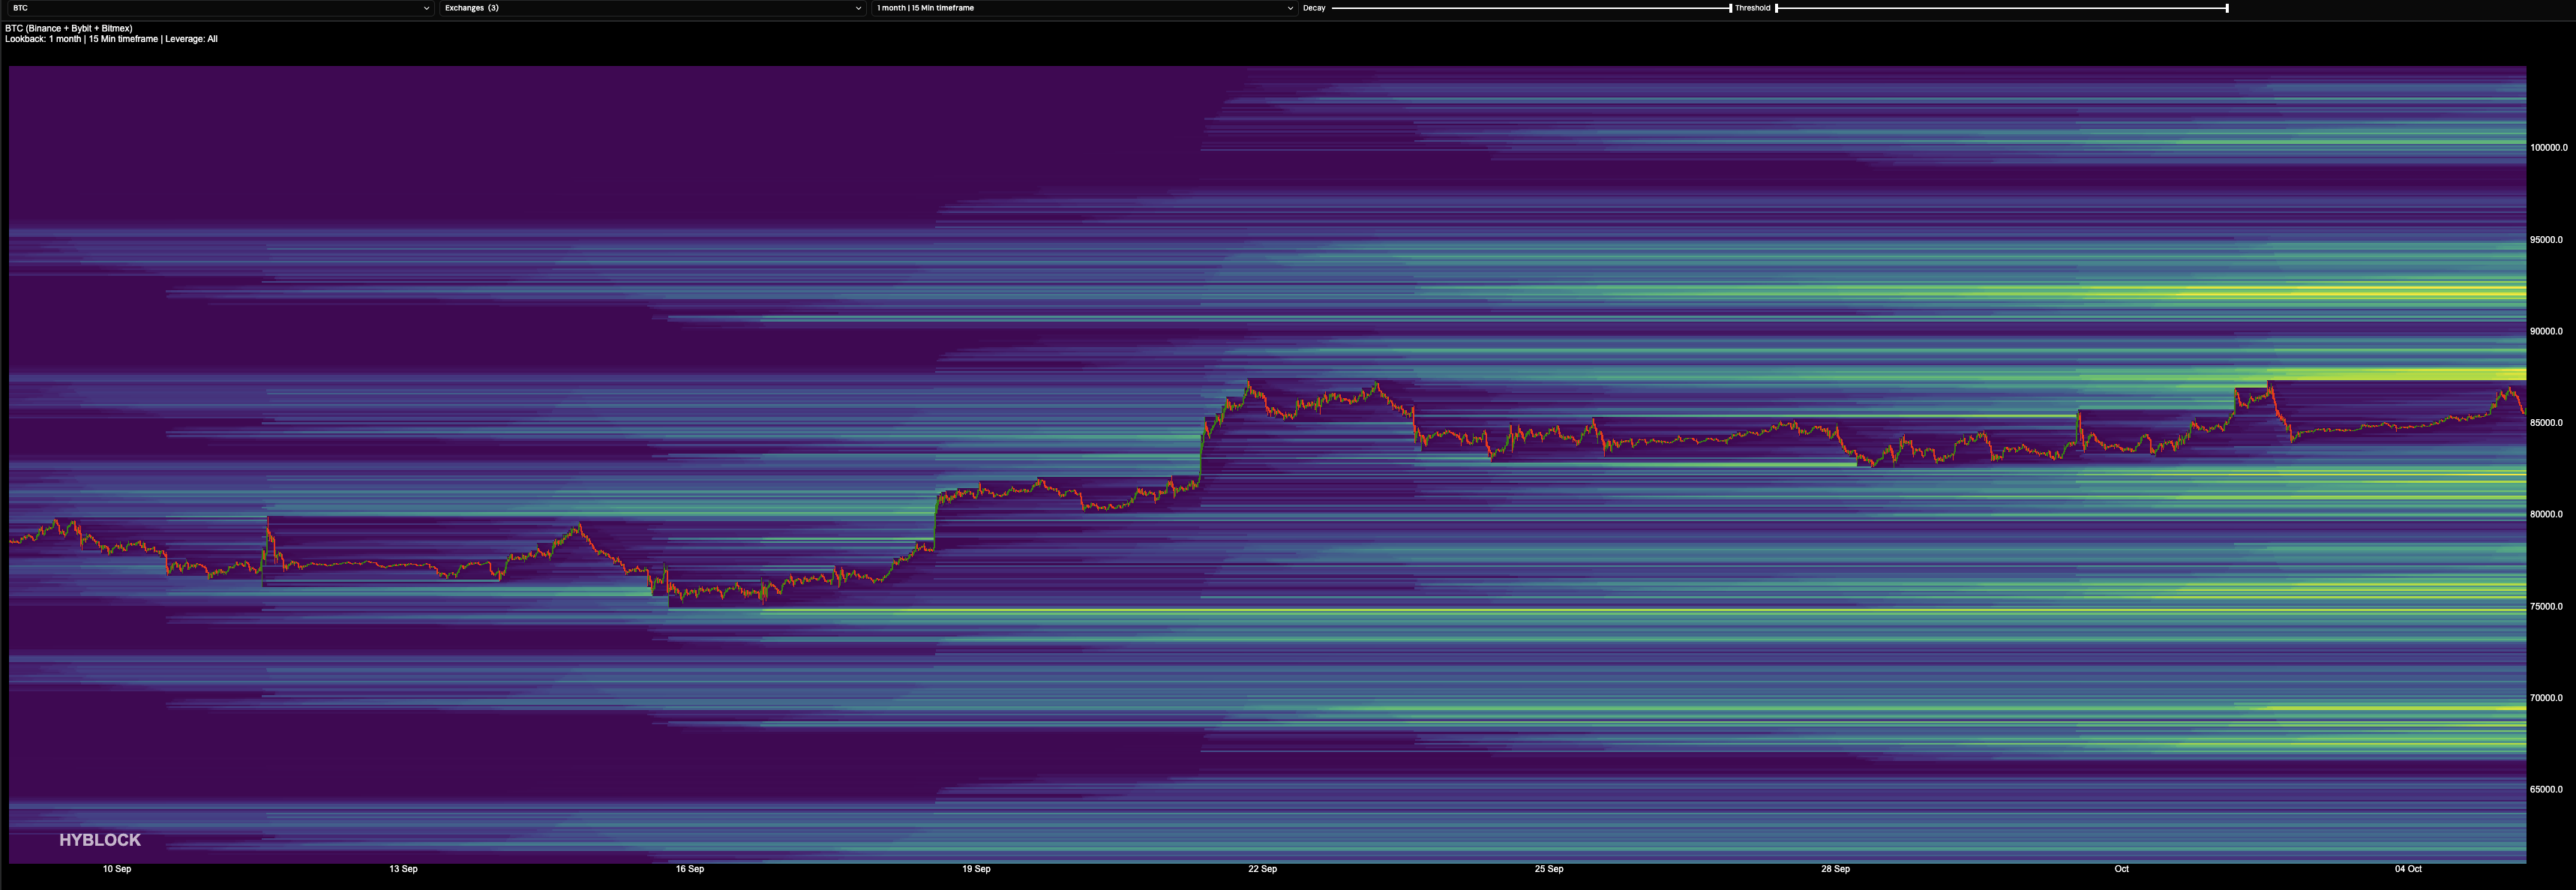
The alternate is the third tap. The 21 September high at 87,385 and Friday's high at 87,249 are two taps on the same area; the pattern completes with a third push above both, into the pool's centre, that is sold. Its trigger is a run above 87,385 followed by a daily close back below 85,750, the floor of the pool. The path from there is back to the long stock from 80,000 to 83,750, with 82,828 the first stop. It is retired by acceptance above 90,250: once the pool's stock is gone there is nothing left to squeeze, and the next stock sits at 93,250.
Why it is live: the move into the pool is being carried by leverage. Open interest is up 10.2% from the week's low, funding has climbed from 0.0015 to 0.0083, Sunday's buying was on the perpetuals, and the spot ETFs bought US $82.9M on the week against US $2.4B the week before. A pool reached on leverage gets filled; staying above it is spot's job, and spot has yet to show up.
Ethereum: at the edge of its own stock
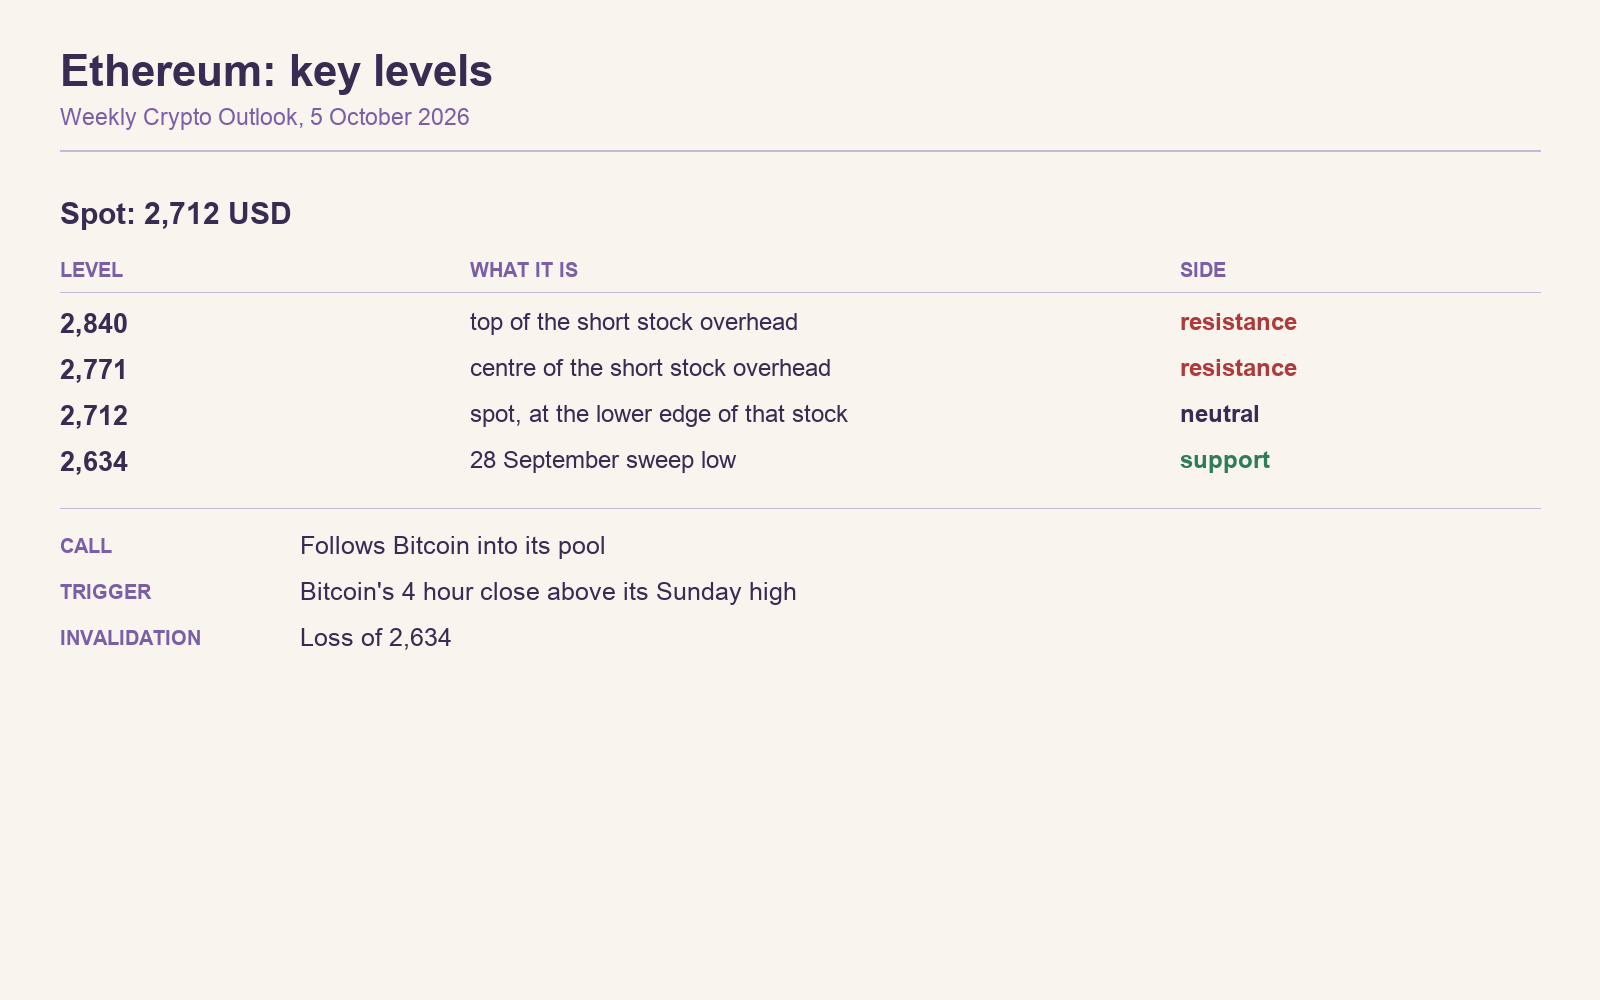
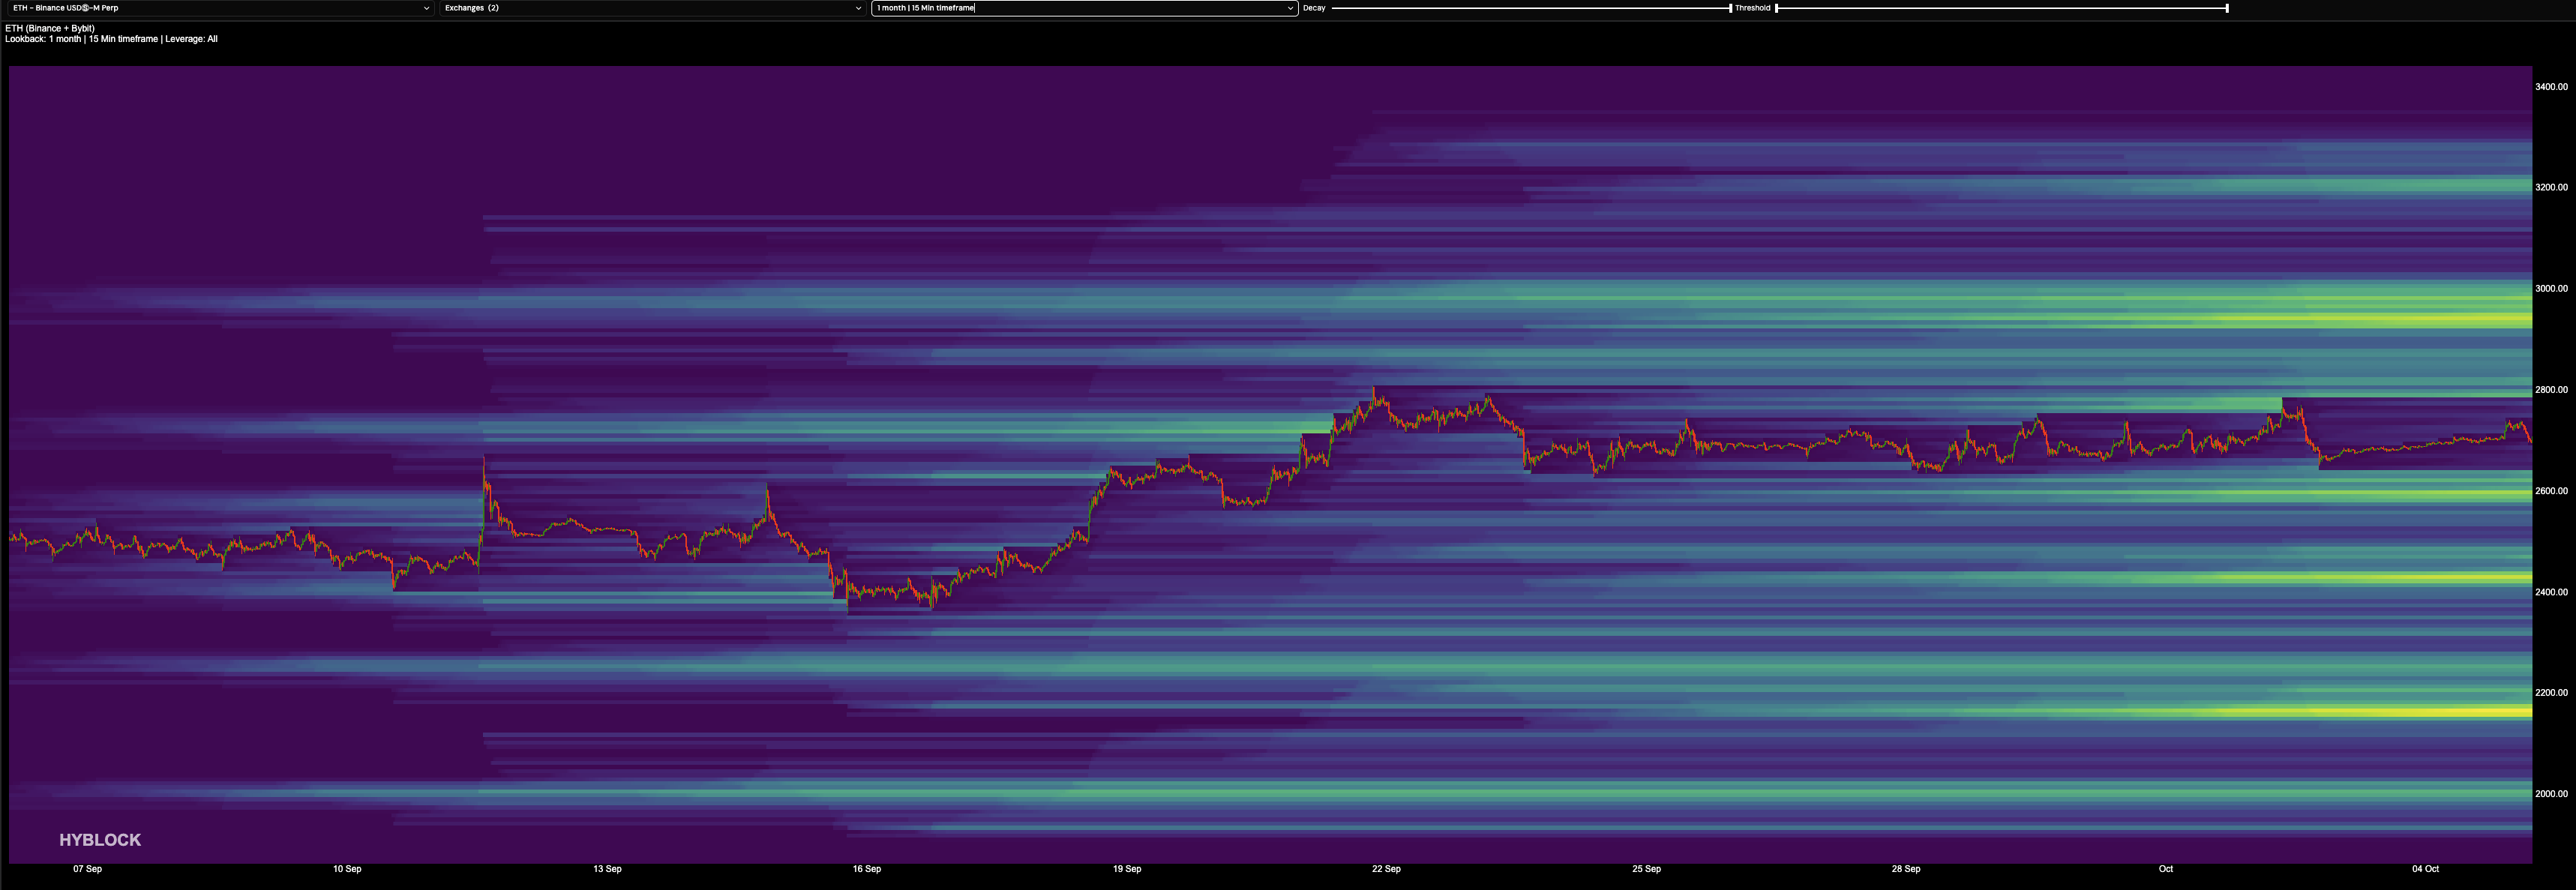
Ethereum trades at 2,712, at the lower edge of the short stock that runs 2,700 to 2,840, centred at 2,771 and densest at 2,740. It lost 0.87% on the week to 2,667.28 while Bitcoin gained, its spot funds took out US $118.0M, and its sentiment rose 14 points: the mood turned before the money did. It follows Bitcoin's trigger.
Trigger — Bitcoin's 4 hour close above 86,770, with Ethereum following rather than leading
Objectives — 2,771, then 2,840
Invalidation: loss of 2,634, the 28 September sweep low, the same mechanism as Bitcoin's: the deviation low that must hold.
Solana: lagged, and follows from here
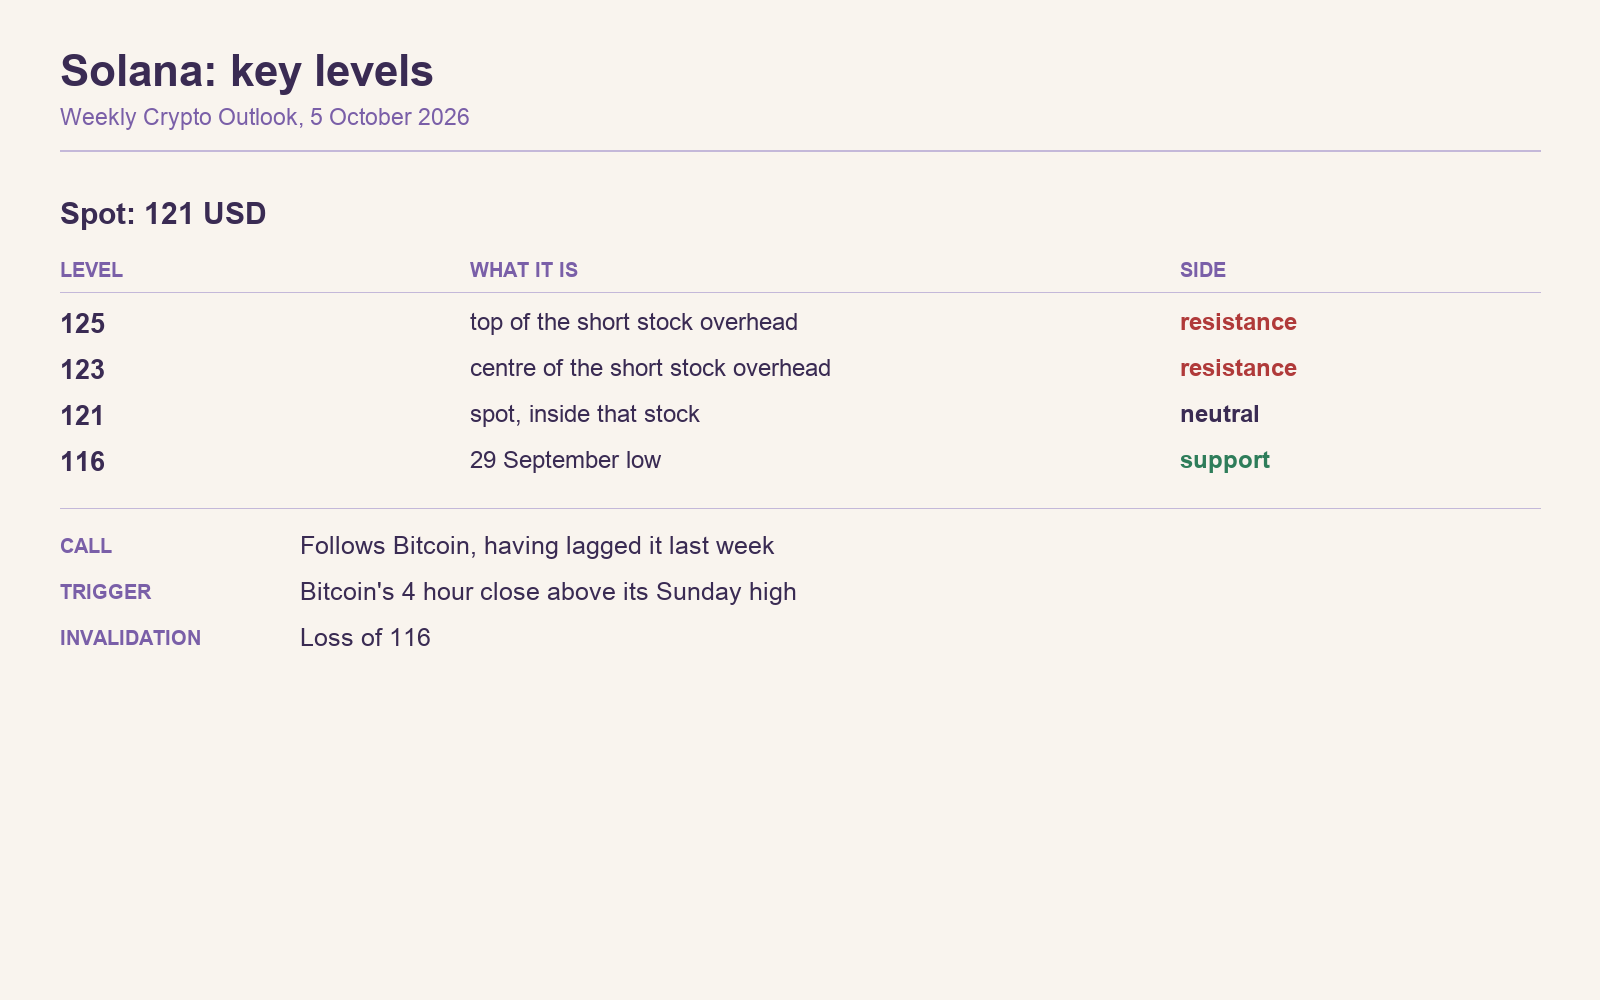
Solana lost 2.90% on the week to 118.56 after two weeks of leading, with a low of 116.25 on 29 September, and trades at 121 inside the short stock that runs 120 to 125, centred at 123. The 11 October unlock is a change in the emission rate, about US $49M per period, 0.068% of circulating.
Trigger — Bitcoin's 4 hour close above 86,770, with Solana following rather than leading
Objectives — 123, then 125
Invalidation: loss of 116, the 29 September low.
Hyperliquid and the broad alts
HYPE is about 91.5, roughly where it was a week ago, at the lower edge of short stock that runs 91 to 97 and is centred at 94. It trades with the market this week.
What decides the week
Whether spot follows the leverage into the pool. The structure points up, the fuel above is in place and half the wick is already filled; the spot bid has yet to arrive, and Wednesday's minutes are the event most likely to bring it back or keep it away. A 4 hour close above 86,770 is the confirmation to wait for, 82,500 is where the support has failed, and a third tap sold back below 85,750 is the alternate to respect until the pool is cleared above 90,250.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.