


Weekly Crypto Outlook – April 20, 2026
Crypto enters the week with improving flows, supported by strong ETF inflows and rising liquidity, but price action remains range-bound. Geopolitical tensions between the U.S. and Iran continue to dominate the macro backdrop, reinforcing inflation risks and delaying rate cuts. While Bitcoin shows relative strength, the broader market setup remains fragile.

TL;DR
Crypto starts the week with a more constructive flow backdrop than last week, but price remains range-bound and the overall setup is still fragile.
The key improvement is in real-money demand. ETF inflows strengthened again, stablecoin minting remains supportive, and Bitcoin whale behavior has turned more constructive after two consecutive weeks of net inflows. This suggests that one of the main structural overhangs on price may be easing.
However, the rally remains narrow. Bitcoin failed to reach the $79K to $80K range top identified last week, reinforcing the view that the market is still trading inside a broader consolidation.
The geopolitical backdrop has deteriorated again and remains the dominant macro driver.
Following the collapse of talks in Islamabad, tensions between the U.S. and Iran escalated sharply after the U.S. seized an Iranian vessel in the Gulf of Oman. Iran has since vowed retaliation and moved to restrict traffic through the Strait of Hormuz.
This matters because it reintroduces immediate energy supply risk, pushes oil back toward the $100 psychological level, and reinforces the same difficult macro regime: sticky inflation, delayed policy easing, and rising risk of a growth shock.
The base case remains range trading.
Bitcoin still has upside magnetism into the $77.3K CME gap while a lower gap remains open at $67.2K, with the market starting the week between the two at the beginning of the week.
From current levels, a push toward the $77.3K CME gap is likely, with failure expected around the $75.3K resistance level, followed by a rotation lower into the $73K to $72K liquidity zone, and potentially extending toward the $67.2K CME gap and the $64.4K HTF liquidation cluster.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Macro Drivers, The Week Ahead
Market Outlook
Macro View
The macro backdrop remains complex and only marginally improved.
PPI came in below expectations last week, offering some short-term relief. However, the recent move in oil has not yet fully flowed through into inflation data, meaning inflation risks remain skewed to the upside in the coming weeks.
At the same time, rate expectations have shifted materially. Markets are now pricing close to zero rate cuts for the remainder of the year, reinforcing the idea that policy easing will be delayed.
Against that backdrop, Bitcoin’s resilience stands out. Since the escalation of the Iran situation, BTC has outperformed both equities and gold, strengthening the case that it is increasingly being treated as a distinct macro asset rather than purely a high-beta risk trade.
Geopolitics remains the primary macro driver
The situation between the U.S. and Iran deteriorated materially over the weekend and is now the key variable for global markets.
The most important developments:
U.S. seizure of Iranian vessel: On April 19, the U.S. Navy intercepted and seized an Iranian-flagged cargo ship in the Gulf of Oman after it allegedly attempted to bypass the naval blockade.
Iran retaliation risk: Iran’s military leadership has signaled that a response is imminent.
Strait of Hormuz disruption risk: Iran has again moved to restrict commercial traffic through the Strait of Hormuz.
Diplomatic deadlock: Talks in Pakistan appear stalled, with no clear path to de-escalation in the near term.
The implication is clear:
elevated energy prices
persistent inflation pressure
delayed policy easing
This reinforces the current macro regime: sticky inflation + geopolitical risk + delayed rate cuts.
Market Movers and Events, Last Week
Market data and flows
Crypto market cap: $2.52T, up 3.7% WoW
Average weekly volume: $132B, 50% above average
Bitcoin weekly volume: $42.1B, 19% above average
Ethereum weekly volume: $20.5B, 20% above average
Ethereum network fees: 0.61 Gwei
Participation improved alongside price, which is a healthier setup than previous weeks.
Futures and positioning
Bitcoin funding rate: -0.1%
Bitcoin open interest: $23.6B
Ethereum funding rate: -4.8%
Ethereum open interest: $12.4B
Funding remains extremely low, suggesting positioning is not crowded.
ETF flows
Bitcoin ETF flows (7 days): +$996M
Bitcoin ETF flows (30 days): +$1.2B
Ethereum ETF flows (7 days): +$276M
Ethereum ETF flows (30 days): -$23M
Flows have now been positive for three consecutive weeks.
Stablecoins and liquidity
USDT market cap: $187B, +1.47% WoW
USDC market cap: $78.2B, -0.5% WoW
Weekly net stablecoin change: +$2.3B
30-day minted: +$3.3B
Liquidity is improving and now supportive.
Dominance
Bitcoin dominance: 59.4%
Ethereum dominance: 10.9%
Market structure continues to favor Bitcoin.
Key headlines
Kelp DAO exploit revives DeFi and bridge risk
Kelp DAO was exploited after a forged cross-chain message drained 116,500 rsETH via its LayerZero bridge, highlighting a critical 1-of-1 validator failure.
The attacker used the assets as collateral to borrow over $200M, triggering stress across lending protocols and a sharp drop in Aave’s TVL. The incident reintroduces bridge risk, restaking fragility, and potential bad debt concerns.
Institutional allocation continues to broaden
Nearly 80% of institutions plan to allocate to crypto, typically in the 2% to 5% range.
Interest is expanding beyond Bitcoin into staking, lending, tokenized assets, and stablecoin infrastructure.
TradFi product expansion continues
Morgan Stanley’s Bitcoin ETF reached $100M in its first week, with Goldman Sachs and Charles Schwab also moving toward crypto offerings.
Institutional infrastructure continues to expand, reinforcing medium-term flow support.
Bitcoin reserve narrative gaining traction
Tennessee is reviewing a bill allowing up to 10% of eligible state funds to be allocated to Bitcoin.
This reflects growing public sector interest in Bitcoin as a reserve asset.
Crypto VC reset continues
Major crypto venture funds saw AUM declines in 2025, but fundraising remains active.
This suggests a more selective capital environment rather than a breakdown in the long-term thesis.
Key Macro Drivers, The Week Ahead
Apr 21: U.S. Retail Sales
This is the most important data point early in the week. A strong print would reinforce resilient consumer demand despite higher energy prices, pushing rate-cut expectations further out and potentially weighing on risk assets. A weaker print would support the narrative of slowing growth, offering short-term relief but reinforcing late-cycle risks.
Apr 23: S&P Global Manufacturing PMI and Services PMI
These releases will help confirm whether the current macro regime remains intact. The key question is whether growth holds while price pressures stay elevated. Strong activity combined with rising costs would reinforce the sticky inflation narrative, while weaker data would shift focus toward growth risks.
Token Unlocks (Most Notable)
Apr 20 – ZRO (LayerZero): $40.4M, 25.71M tokens, 5.34% of circulating supply
Apr 20 – KAITO: $8.1M, 17.6M tokens, 4.93% of circulating supply
Apr 22 – HYPER (Hyperlane): $8.6M, ~89.7M tokens, ~94.37% of circulating supply
Apr 22 – LMTS (Limitless): $8.5M, 85.37M tokens, ~65% of adjusted released supply
Apr 23 – TON (Toncoin): $44.6M unlock, high visibility event
Apr 24 – INIT (Initia): $7.8M, 82.94M tokens, 45.18% of circulating supply
Apr 25 – H (Humanity): $10.8M, 105M tokens, 4.02% of circulating supply
Key takeaway:
HYPER and INIT represent the highest short-term supply risks given their size relative to circulating supply. ZRO and TON also carry elevated importance from a visibility and sentiment perspective.
Market Outlook
Sentiment
Bitcoin Greed & Fear: 60% vs 65%
Ethereum Greed & Fear: 60% vs 70%
Sentiment has cooled slightly.
Bitcoin
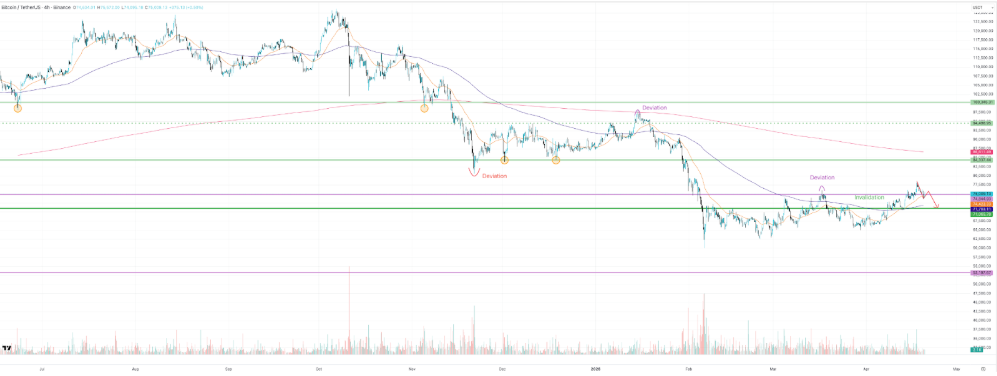
Bitcoin remains range-bound with a constructive but unconfirmed breakout structure.
The key risk remains geopolitical escalation, which could override technical structure.
From current levels, a push toward the $77.3K CME gap is likely, with failure expected around the $75.3K resistance level, followed by a rotation lower into the $73K to $72K liquidity zone, and potentially extending toward the $67.2K CME gap and the $64.4K HTF liquidation cluster.
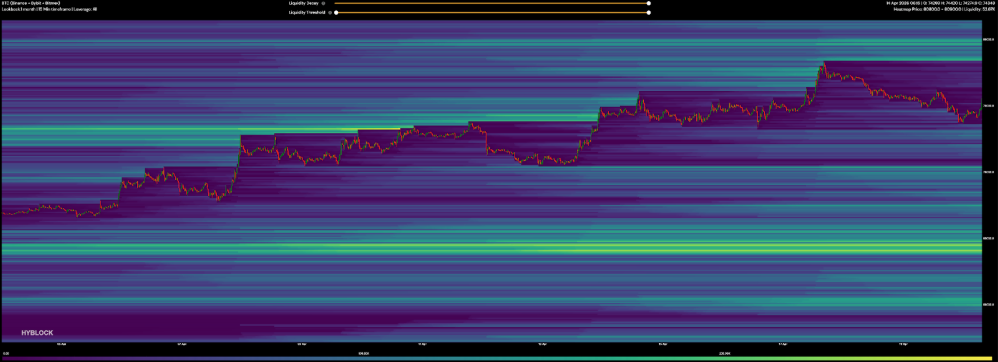
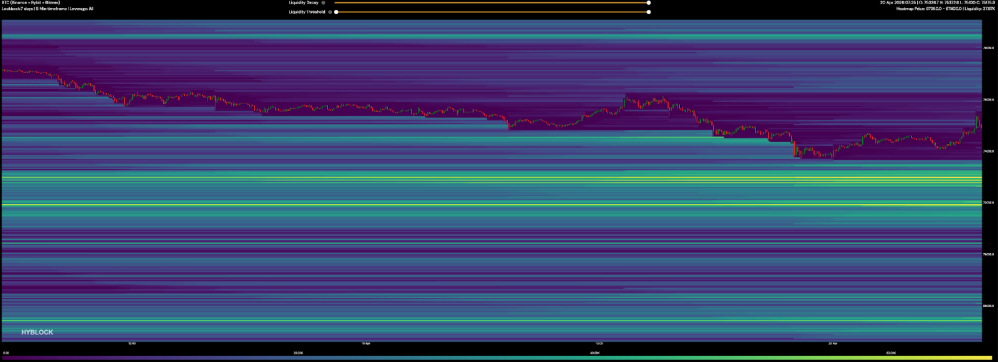
Immediate resistance: $75,300
Upper target: $77,300
Major upside zone: $79,000–$80,000
Critical structure hold: $72,661
First downside target: $73,000–$72,000
Secondary downside: $67,200 CME gap
HTF liquidation cluster: $64,400
Ethereum
ETH has improved on flows but remains structurally weaker.
The Kelp exploit adds additional pressure given ETH’s exposure to DeFi and restaking.
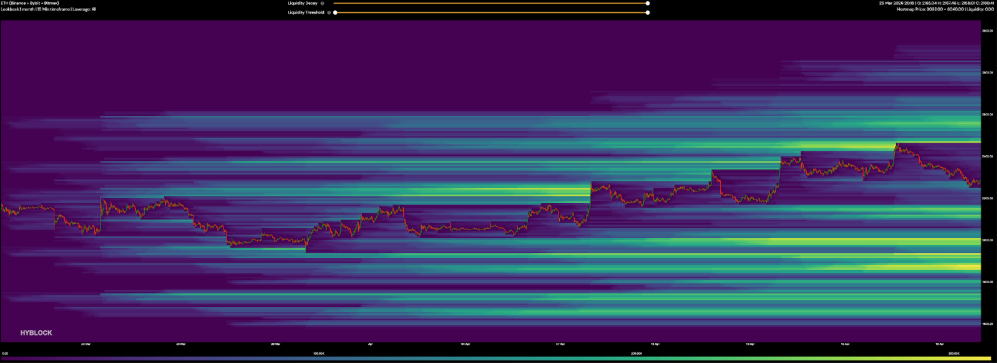
Immediate resistance: $2,300
Critical level: $2,240
First downside target: $2,200
Downside liquidation pools: $2,125 and $1,875
Altcoins
Conditions remain challenging:
strong Bitcoin dominance
weak ETH relative performance
weakened DeFi sentiment
Continue to favor Bitcoin over altcoins.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.