



TL;DR
Crypto markets remain in a fragile, low conviction consolidation, with price action still driven primarily by macro expectations and liquidity conditions rather than internal momentum. The Fed delivered a widely expected 25 bp cut to a target range of 3.50 to 3.75%, but internal divisions and a restrictive dot plot continue to cap risk appetite. Bitcoin remains in a broader downtrend, but after clearing the USD 88,500 liquidation cluster over the weekend, conditions favor a near term relief rally toward the USD 95,200 to USD 95,500 zone, where a large overhead liquidation cluster and the 50 day EMA converge. Ethereum continues to lag, with deeply negative funding and elevated open interest pointing to hedged positioning and heightened two way volatility rather than directional conviction.
Flows have improved modestly, with BTC and ETH ETFs seeing marginal inflows over the past week, but demand remains insufficient to support sustained upside. Stablecoin minting has slowed back to neutral levels, reinforcing the view that liquidity is present but not yet being deployed aggressively into risk assets.
Near term risks remain skewed toward tactical trading rather than trend positioning. US payrolls, US CPI, and the Bank of Japan rate decision remain the key volatility catalysts into year end. Rallies are still viewed as corrective within a broader bearish structure, and positioning should remain disciplined, with an emphasis on capital preservation and selling strength into key resistance.
In this week’s note
Macro View
Market Movers & Events – Last Week
Key Macro Drivers – The Week Ahead
Market Outlook
1. Macro View
A rate cut that highlights Fed division
The Federal Reserve delivered a 25 bp rate cut, bringing the target range to 3.50 to 3.75%. While the decision itself was widely expected, the internal split was notable. Two members dissented in favor of no change, and the dot plot showed a meaningful group of officials viewing the cut as premature. Projections continue to imply only 1 additional cut in 2026, which weighed on risk sentiment and helps explain Bitcoin’s muted to negative reaction following the announcement.
Expectations around the future Fed
Incoming US data remains mixed. JOLTS openings surprised to the upside, particularly in transport, while other growth sensitive sectors showed continued weakness. Market focus is increasingly shifting away from the current committee toward what the Fed may look like by mid 2026. Kevin Hassett remains a leading candidate discussed as a potential successor to Chair Jerome Powell, and has consistently argued that there is room for materially lower policy rates, with levels below 3% framed as plausible over the long term. A shift in Board composition toward more dovish members would tilt medium term risks toward easier policy than currently implied by the dot plot.
Disinflation becoming more visible
Disinflationary forces are increasingly evident. Energy prices have eased, rent inflation continues to slow, and wage growth is drifting lower. The Fed has also acknowledged that recent job gains may have been overstated. At the same time, tariff related inflation pressures are unfolding more slowly than initially feared. Against this backdrop, further policy loosening remains more likely than not over the medium term, even as near term policy remains highly data dependent.
2. Market Movers & Events – Last Week (Dec 1 – 7)
Price action
Crypto market capitalization stands at approximately USD 3.07 trillion, down 1% week on week.
Average weekly volumes were USD 129 billion, down 3% versus average.
Bitcoin weekly volume was USD 63.3 billion, 1% below average
Ethereum weekly volume was USD 24.3 billion, broadly in line with average
Ethereum network fees were around 0.04 Gwei, consistent with very low on chain activity
Flows and positioning
Futures
Bitcoin funding rate increased to approximately 2.1%
BTC futures open interest declined by about USD 0.2 billion to USD 28.2 billion
Ethereum funding remains deeply negative at around minus 11.5%
ETH open interest increased by about USD 1.2 billion to USD 18.6 billion
The combination of deeply negative ETH funding and rising open interest suggests hedged positioning rather than directional conviction, increasing the risk of sharp two way moves.
ETFs
Flows improved modestly in December but remain lackluster.
BTC ETF flows were approximately USD 287 million over 7 days, versus minus USD 2.6 billion over 30 days
ETH ETF flows were approximately USD 211 million over 7 days, versus minus USD 863 million over 30 days
Dominance
Bitcoin dominance: 58.6%, down 0.1%
Ethereum dominance: 12.2%, unchanged
Stablecoins
Minting activity slowed to neutral levels.
USDT market cap: USD 186.2 billion, up 0.32% week on week
USDC market cap: USD 78.4 billion, up 0.4% week on week
30 day stablecoin issuance: approximately USD 5.5 billion
Key Headlines
YouTube enables stablecoin payments
YouTube is allowing US creators to receive payouts in stablecoins using PayPal’s PYUSD, marking another step in the integration of stablecoins into mainstream digital payment infrastructure.
Stripe’s Tempo accelerates
The Tempo blockchain, backed by Stripe and Paradigm, launched its public testnet. The network is designed for stablecoin payments and low fee settlement, with several large financial institutions participating as design partners.
Tokenised stocks approved by the SEC
The US Securities and Exchange Commission issued a no action position allowing DTCC to provide tokenisation services for equities and other real world assets on approved distributed ledger platforms for a period of 3 years.
3. Key Macro Drivers – The Week Ahead (Dec 8 – 14)
Economic data and central bank events
December 16: US jobs report for November (includes delayed October payroll figures)
December 18: US CPI
December 19: Bank of Japan interest rate decision
Token unlocks and market events
December 14: IP USD 127 million unlock
December 15: ARB USD 20 million unlock
December 17: PENGU USD 284 million unlock
December 19: ZERO USD 32 million unlock
December 26: Deribit options expiry
December 29: OP USD 10 million unlock
Lido V3 launch expected in December
4. Market Outlook
Liquidity and Positioning
Bitcoin Fear and Greed Index: 14%, down from 30%
Ethereum Fear and Greed Index: 46%, down from 55%
Sentiment remains weak and consistent with a market still in repair rather than trend resumption.
Bitcoin (BTC)
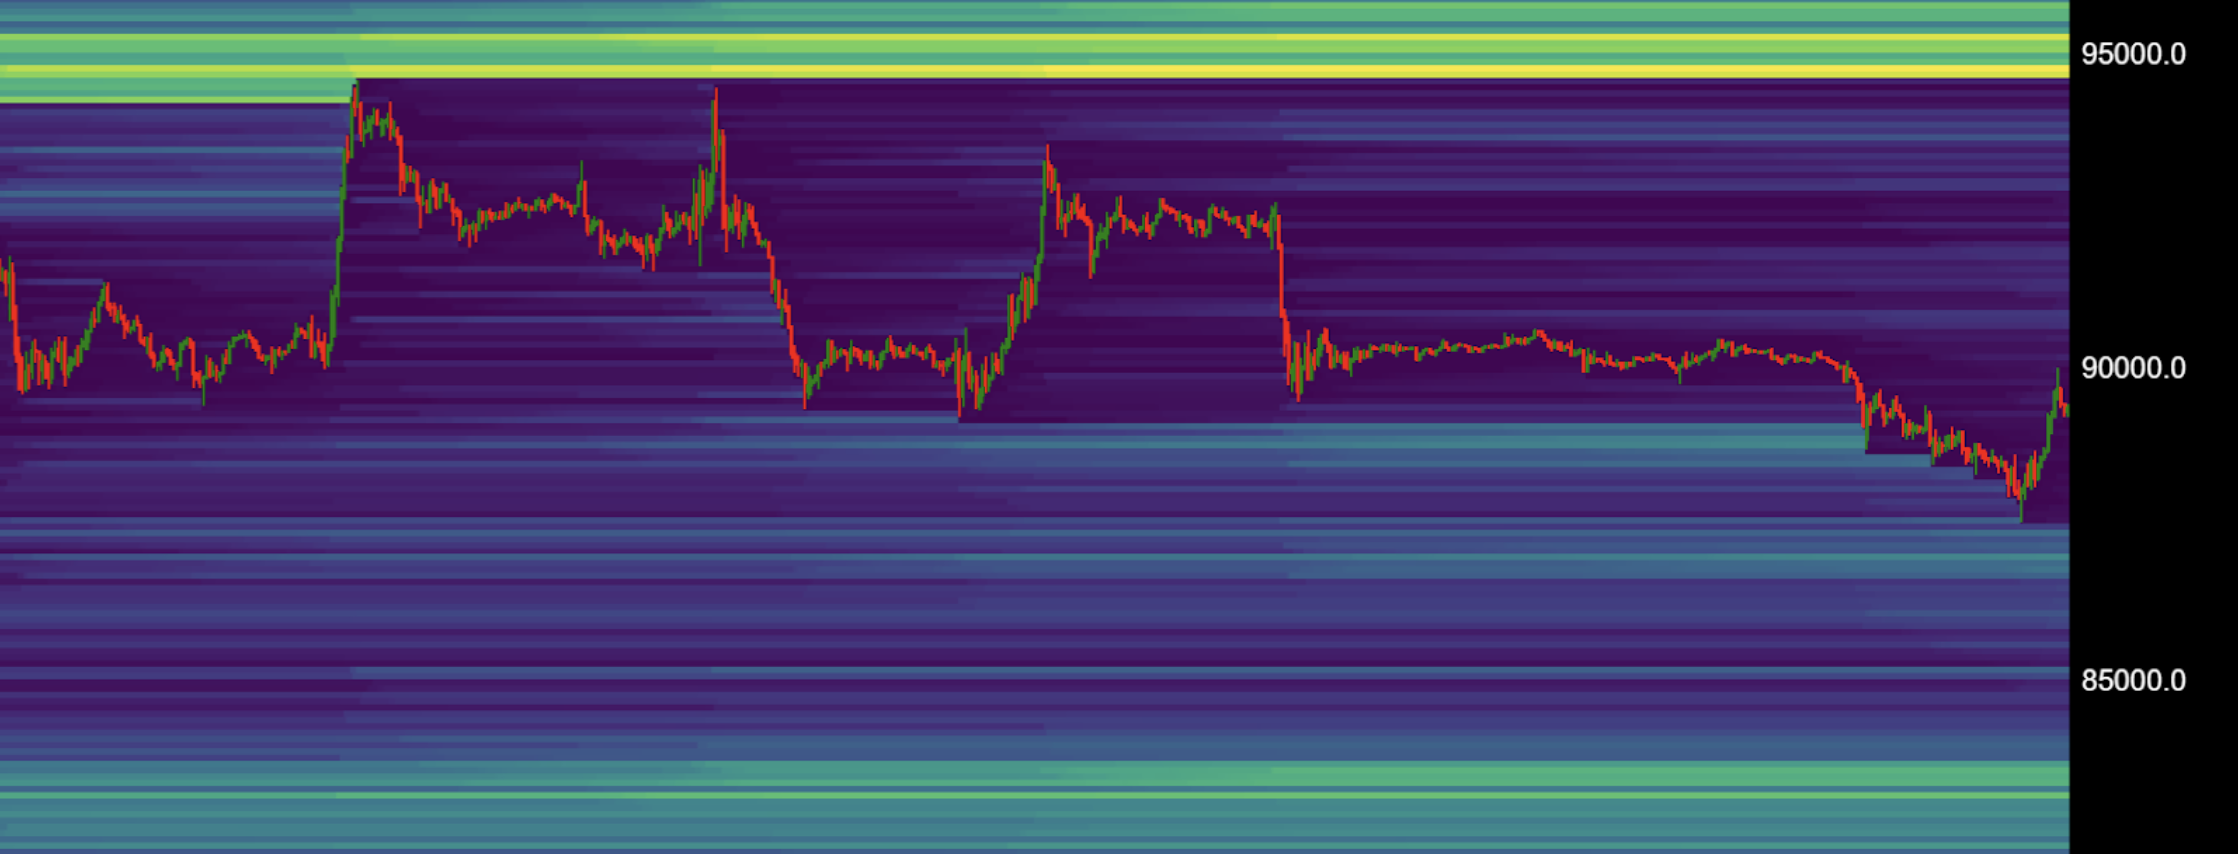
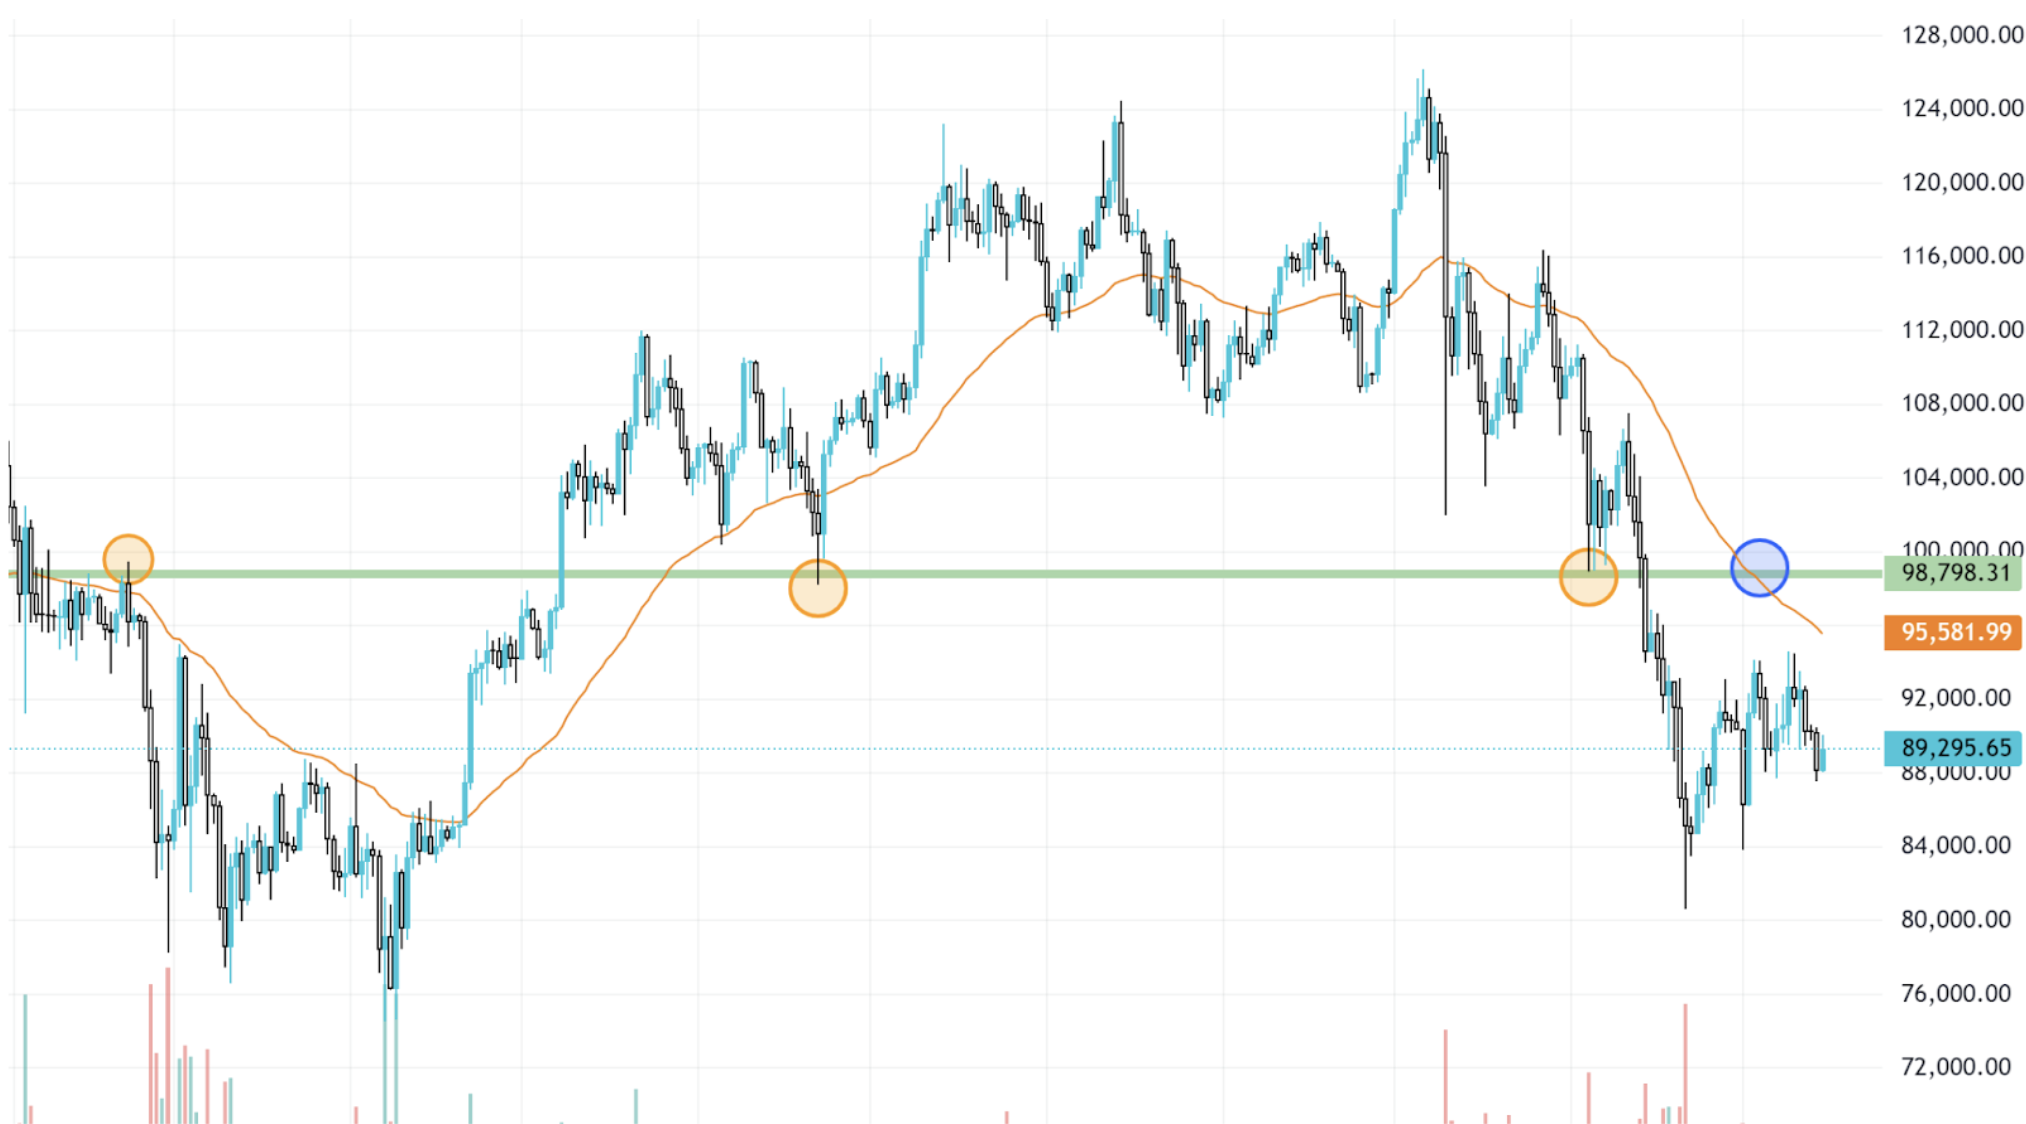
The broader Bitcoin downtrend remains intact, with momentum indicators still reflecting a bearish regime and price vulnerable to liquidity driven moves in thin conditions. However, after clearing the USD 88,500 liquidation cluster over the weekend, the most likely near term scenario is a relief rally toward the USD 95,200 to USD 95,500 zone, where a large overhead liquidation cluster coincides with the 50 day EMA.
Key levels:
Short-term pivot: USD 95,200
Major bull or bear line: USD 100,000
Ethereum (ETH)
Ethereum rebound attempts continue to fail near the top of the downtrend channel. Deeply negative funding alongside rising open interest reinforces the view that current positioning is unstable and volatility prone.
Short term pivot: USD 3,300
Major bull or bear line: USD 3,600
Altcoins
With market capitalization stagnant and dominance not decisively shifting, there is no clear signal supporting broad altcoin beta. Exposure should remain selective and catalyst driven.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.