



TL;DR
Crypto starts the week in a stronger tactical position than last week, but the setup remains fragile.
The market briefly found relief after the April 8 two-week U.S. - Iran ceasefire and temporary reopening of the Strait of Hormuz, which helped Bitcoin reclaim the $72,000 level and print a weekly high at $73,800.
That relief has already faded.
Weekend talks in Islamabad collapsed, and the U.S. subsequently announced a blockade of Iranian ports and coastal areas, pushing oil back toward the $100 psychological level and immediately reintroducing the inflation-shock narrative into global markets.
This geopolitical reversal matters because it reinforces the same difficult macro regime: sticky inflation, delayed policy easing, and rising risk of a later growth shock.
Last week’s data confirmed that the economy is now operating in exactly that regime. CPI surprised to the upside at 3.3%, driven by a 21.2% MoM surge in gasoline prices, while ISM Services continued to show resilient demand but sharply rising input costs.
Crypto’s internal structure improved during the week. Market cap increased to $2.43T, volumes improved, and ETF flows turned positive again, helping stabilize price action even as the geopolitical backdrop worsened.
Bitcoin’s chart is now one of the clearest in weeks:
bullish structure while above $69K
early-week upside magnet at the $73K CME gap
external range high near $76K
HTF liquidation pull around $64.4K
higher-conviction swing-long zone at $61K–$59K
The base case this week remains patience.
There is little edge in the middle of the range, and the preferred strategy is to wait for price to trade into one of the outer liquidity extremes before adding risk.
In This Week’s Note
Macro View
Market Movers and Events, Last Week
Key Macro Drivers, The Week Ahead
Market Outlook
Macro View
Last week confirmed that the macro regime is becoming more complex and less supportive for risk assets.
The key takeaway is not just that inflation surprised higher, but how it is happening.
CPI: 3.3%, driven by energy
Gasoline: +21.2% MoM
ISM Services: expansion continues
Services Prices Index: highest in over 13 years
This combination signals an economy that is still growing, but under increasing cost pressure.
The implication is important.
The market had been expecting a transition toward a growth shock and policy easing. Instead, we are seeing:
persistent inflation driven by energy
resilient service demand
delayed policy relief
FOMC Minutes reinforced this shift, showing:
increasing concern around inflation persistence
openness to further tightening if needed
no near-term path to rate cuts
At the same time, the geopolitical backdrop remains the dominant driver.
The brief ceasefire created a short-lived risk-on rally, but the collapse of negotiations and renewed blockade risk reintroduced volatility:
oil trading just below the $100 psychological level
elevated shipping costs
continued pressure on global supply chains
This keeps the market focused on the risk of a fresh energy inflation spike if the conflict escalates further.
This reinforces the broader macro transition toward: sticky inflation + slowing growth + delayed easing.
That remains a difficult environment for crypto beta.
Market Movers and Events, Last Week
Market data and flows
Crypto market cap: $2.43T, up 4.7% WoW
Average weekly volume: $88B, 15% above average
Bitcoin weekly volume: $35.5B, 15% above average
Ethereum weekly volume: $17.1B, 16% above average
Ethereum network fees: 0.08 Gwei
The key shift versus prior weeks is that volumes have picked up alongside price, suggesting more genuine participation rather than purely mechanical moves.
Futures and positioning
Bitcoin funding rate: 3.3%
Bitcoin open interest: $22.1B
Ethereum funding rate: -1.1%
Ethereum open interest: $12.4B
This reflects dip buying rather than aggressive leverage expansion, with positioning rebuilding but not yet crowded.
ETF flows
Bitcoin ETF flows (7 days): +$816M
Bitcoin ETF flows (30 days): +$982M
Ethereum ETF flows (7 days): +$186M
Ethereum ETF flows (30 days): +$75M
This is a meaningful change.
ETF flows have shifted back into moderately supportive territory, particularly for Bitcoin, helping stabilize the market after several weeks of outflows.
However, the structural divergence remains:
BTC flows positive
ETH flows still weak year-to-date
Stablecoins and liquidity
USDT market cap: $184.3B, +0.11% WoW
USDT trading volume: $74B
USDC market cap: $78.6B, +1.4% WoW
USDC trading volume: $9.6B
Weekly net stablecoin change: +$1.3B
30-day minted: -$200M
Liquidity is neutral, not expansionary, which limits upside continuation.
Dominance
Bitcoin dominance: 58.9%
Ethereum dominance: 11%
Key headlines
Quantum risk narrative softens
Bernstein pushed back against concerns around quantum computing threats to Bitcoin, arguing the risk is manageable rather than existential and should be viewed as part of a broader upgrade cycle affecting all critical digital systems. The key market implication is that the “quantum-safe” narrative is now becoming a selective thematic driver, which explains outsized moves in names like ZEC while reinforcing the idea that Bitcoin’s transparent governance and institutional stakeholder base make long-term mitigation realistic.
Stablecoin regulation debate evolves
The White House Council of Economic Advisers concluded that banning stablecoin yield would have a negligible impact on bank lending, with only a 0.02% modeled increase in lending volumes. This matters because it weakens one of the core political arguments behind stricter stablecoin legislation and supports the view that stablecoin rails are increasingly being treated as complementary infrastructure rather than direct banking disintermediation risk.
Polymarket infrastructure upgrade
Polymarket announced its largest infrastructure overhaul to date, including a rebuilt matching engine, upgraded smart contracts, and the launch of Polymarket USD, a native stablecoin backed 1:1 by USDC. The strategic significance is the reduction of bridge risk, tighter control over settlement liquidity, and further evidence that major crypto platforms are increasingly vertically integrating their execution and settlement stack.
Key Macro Drivers, The Week Ahead
Apr 14: PPI ex Food & Energy (YoY)
A higher print would reinforce the idea that upstream inflation pressures are still building and likely to pass through to consumers in coming months.
Token Unlocks
PUMP: 10B tokens, 1.00% of total supply, $18.0M
ARB: 92.65M tokens, 0.93% of total supply, $10.4M
ZK: 173.44M tokens, 0.83% of total supply, $2.6M
SEI: 55.56M tokens, 0.56% of total supply, $3.0M
HYPE: 9.92M tokens, 0.99% of total supply, ~$374M
TRUMP: 90M tokens, 9.00% of total supply, ~$250M, nearly 45% of circulating supply
ASTER: ongoing unlock, ~$110M, one of the largest weekly inflows
The combination of HYPE emissions, ASTER supply inflow, and TRUMP’s ~45% circulating dilution risk remains the most important source of short-term altcoin pressure.
Market Outlook
Sentiment
Bitcoin Greed and Fear Index: 65% vs 35% last week
Ethereum Greed and Fear Index: 70% vs 50% last week
Sentiment has shifted meaningfully higher and is now entering constructive but not yet euphoric territory.
This week will be a real test of whether sentiment can translate into sustained flows.
Bitcoin
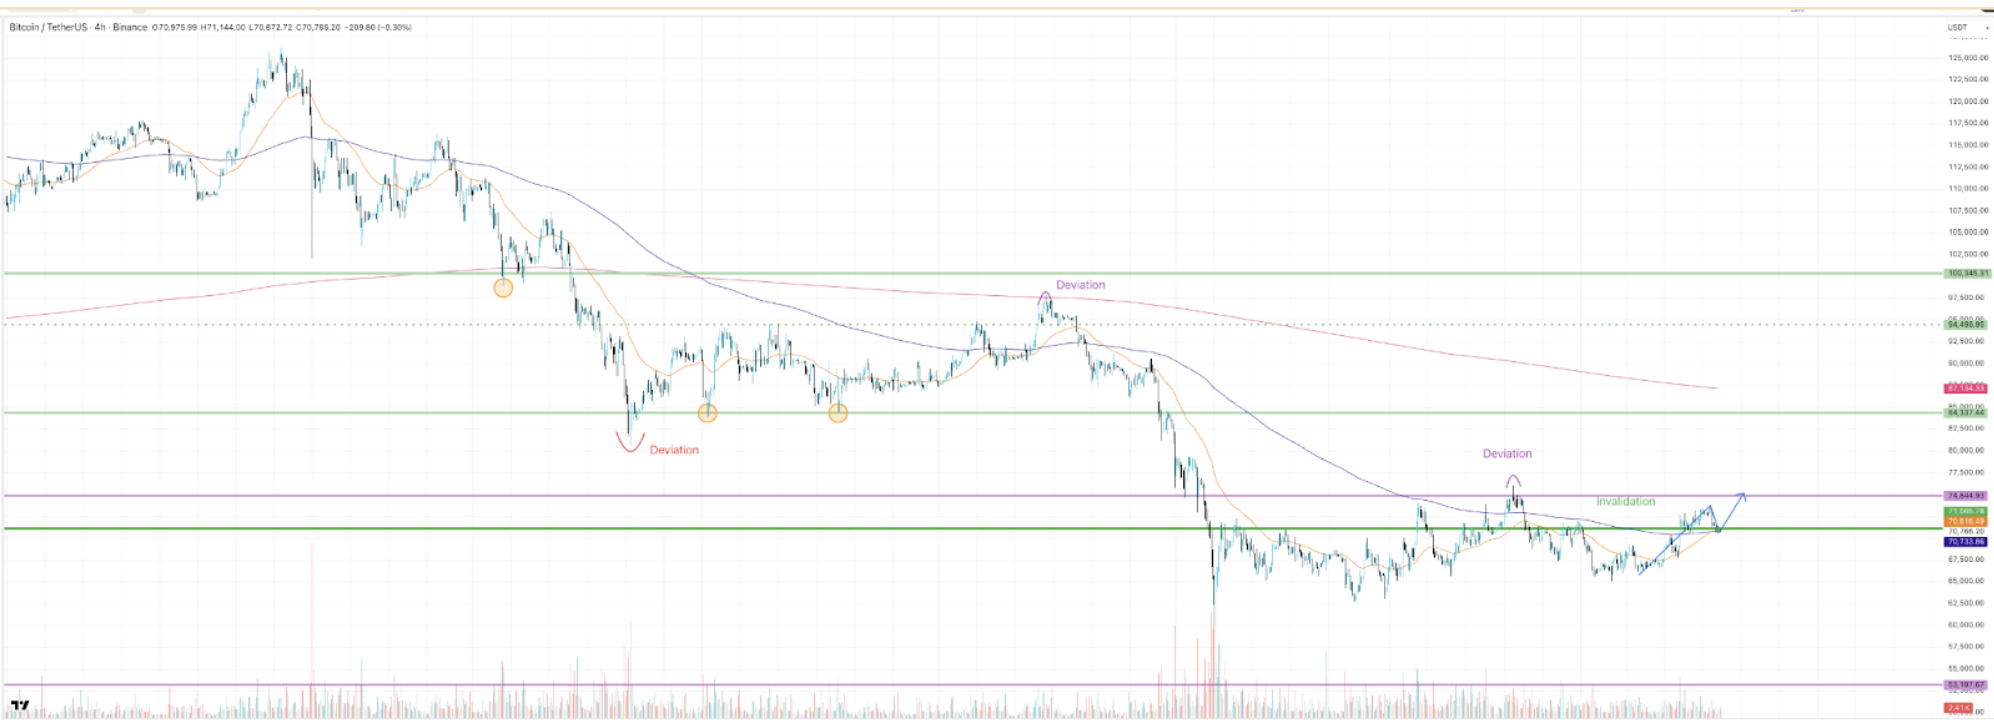
Bitcoin’s structure is cleaner than it has been in several weeks.
Price has now swept 3 key liquidity areas, aggressively clearing short-side stops while forcing a large amount of short covering. The move has been driven more by liquidation mechanics than by a true expansion in organic spot demand.
The tactical focus now shifts to whether BTC can hold bullish structure above the $69K region.
The preferred paths are:
A failure to hold the $69K support would likely trigger:
liquidity sweep of $65K–$66K
HTF liquidation pull toward $64.4K
potential extension lower if macro headlines deteriorate
The upside scenario remains equally clean.
bullish continuation if BTC holds above $69K
early-week push into the $73K CME gap
possible extension toward the external range high near $76K
if $73K fills but fails to hold, the weekly high is likely set early
fading momentum later in the week becomes the preferred path
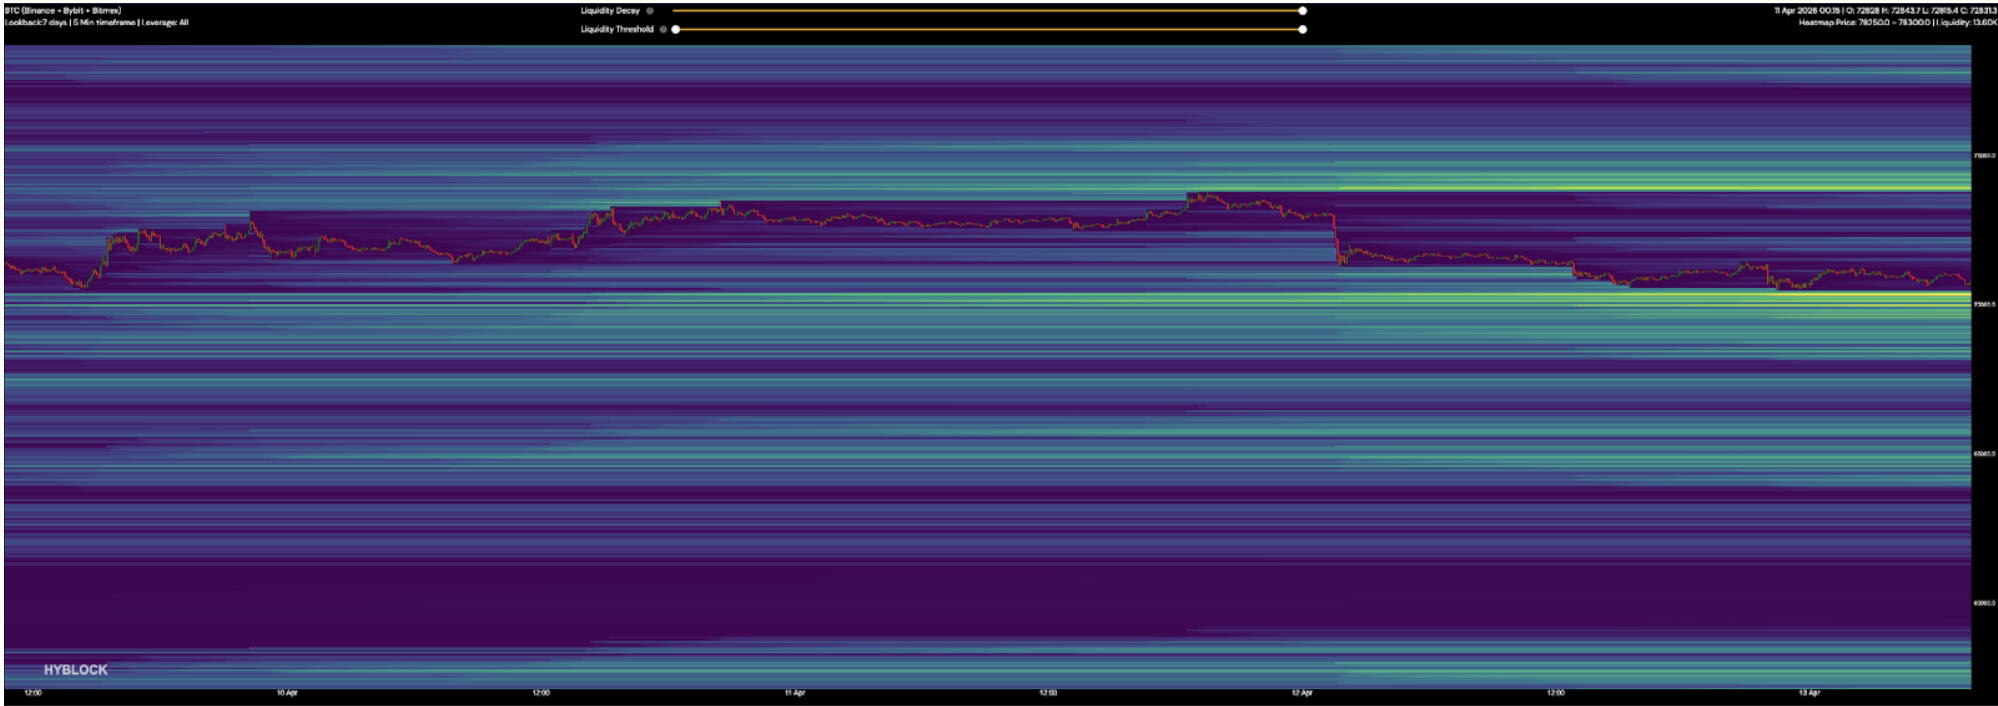
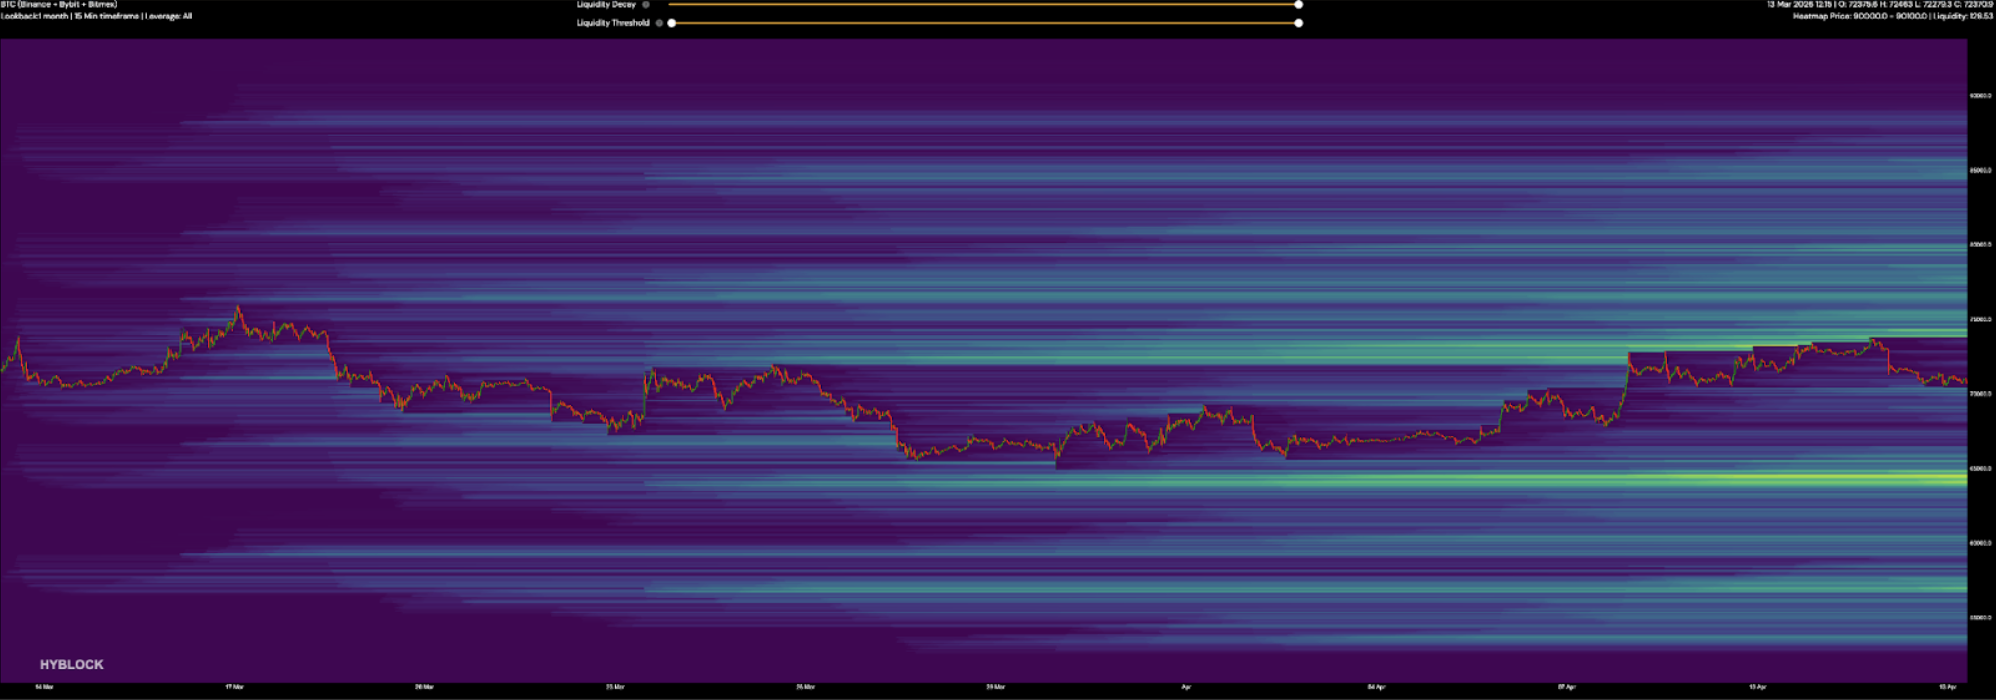
Immediate resistance: $73,000
External range high: $76,000
Critical structure hold: $69,000
First downside target: $65,500
HTF liquidation pool: $64,400
Major downside swing-long zone: $61,000–$59,000
Major upside swing-short zone: $79,000–$80,000
Ethereum
ETH has improved tactically but remains structurally weaker.
ETF flows have turned positive short term, but:
year-to-date flows remain negative
relative performance vs BTC is still weak
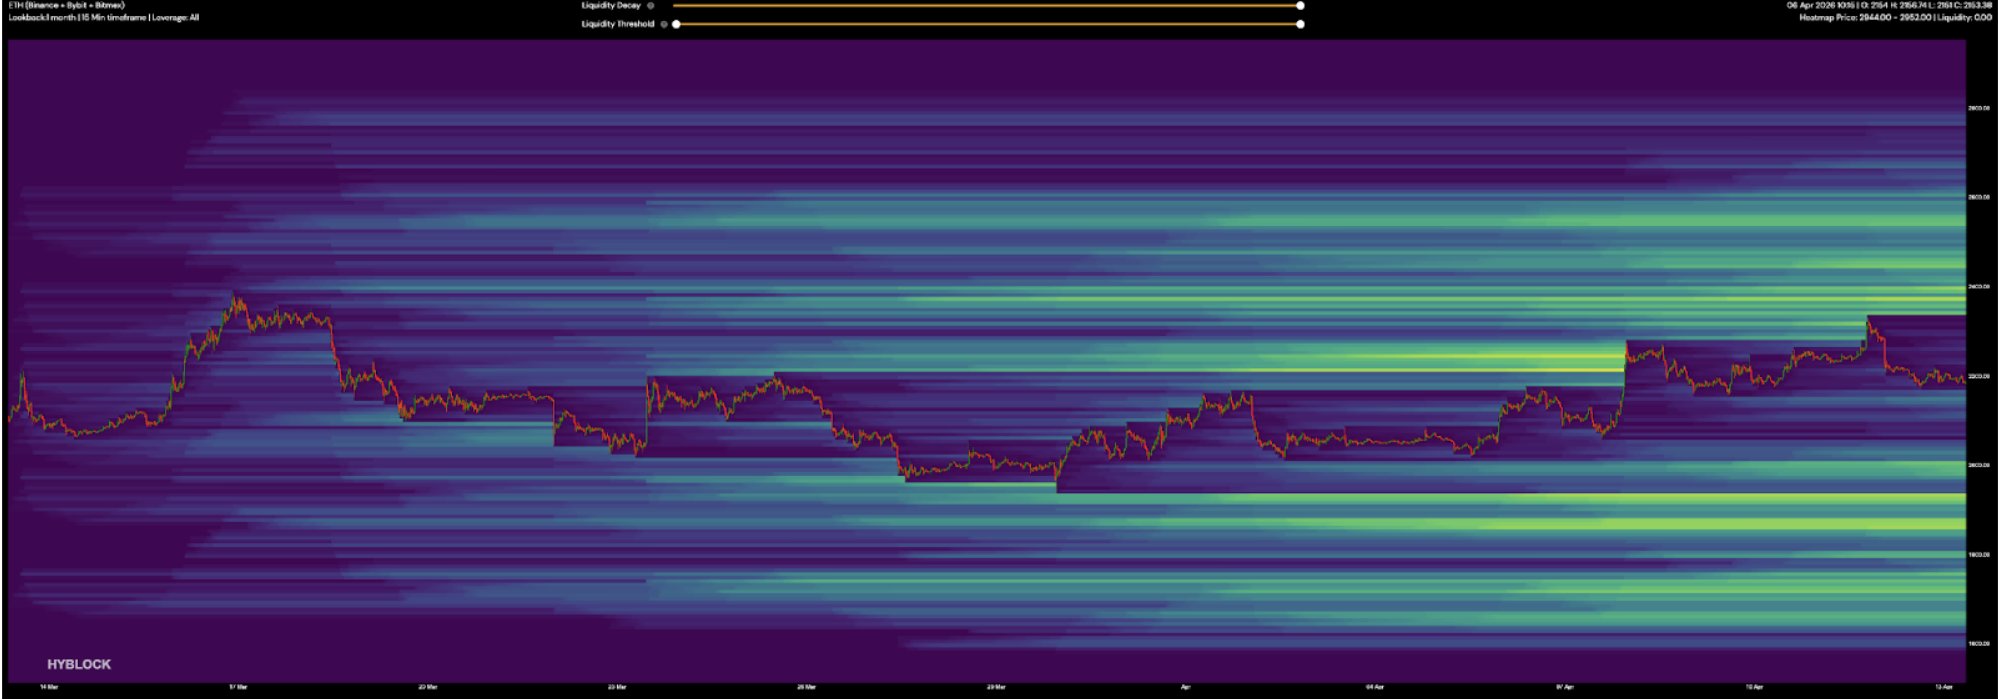
Immediate resistance: $2,275
First downside target: $2,025
Downside liquidation pool: $1,925
Altcoins
Last week saw a clear rotation into higher-beta assets, but this still looks tactical rather than structural.
Key observations:
ZEC outperformance driven by quantum narrative
ARB, PEPE, WLD, TON reflect risk-on rotation
ETH underperformance persists
token unlock pressure remains elevated
Continue to favor Bitcoin over altcoins.
Disclaimer: This content presents objective market data and does not constitute investment advice.

Copyright © 2026 Rain Management W.L.L.